The Dividend Aristocrats Returned 37.4% Over Five Years. Fidelity’s High Dividend Fund Returned 79.93%, Pays More, and Charges 0.15%

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
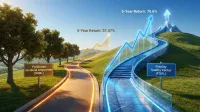
The ProShares S&P 500 Dividend Aristocrats ETF (CBOE:NOBL) is many retirees’ default for reliable dividend income. NOBL holds S&P 500 companies that have raised their dividends every year for at least 25 years. That screen rewards discipline and appeals to anyone who wants rising dividend income. Over the five years starting November 19, 2021, though, NOBL returned 37.4% with distributions reinvested. The Fidelity High Dividend ETF (NYSEARCA:FDVV) returned 79.93%, a gap of 42.53 percentage points.
In dollars, a $100,000 position in the ProShares fund that tracks the Dividend Aristocrats grew to $137,400. The same stake in Fidelity’s fund grew to $179,930. Both windows start on the same date, and both assume reinvested distributions, so the gap shows what each fund actually delivered to a patient holder.
A Decade of Data Points the Same Way
The longer record agrees. Over ten years, FDVV returned 233.94%, and NOBL returned 174.74%, a Fidelity lead of 59.2 percentage points. Both ten-year windows begin on November 18, 2016. Fidelity’s lead holds across two overlapping periods, so it is hard to dismiss as one lucky stretch.
Fidelity’s Fund Paid More Cash on the Same Stake
For an income investor, the higher growth also came with a bigger payout. Over the trailing twelve months, a $100,000 position in FDVV produced $2,864.78 in income. The same position in NOBL produced $1,983.02. Each fund made four quarterly payments. NOBL’s figure is adjusted for its two-for-one share split in May 2026, so its payments before and after the split compare directly.
Fidelity’s payments vary from quarter to quarter. Its September distribution was $0.362 per share, down from $0.519 in June. Anyone relying on a regular quarterly check should plan for that swing.
Fidelity Charges 0.15% a Year
FDVV has an expense ratio of 0.15%. Fund returns are reported after expenses, so that cost already sits inside every Fidelity return figure above.
Recent Returns Favor the Aristocrats
The case for Fidelity’s fund rests on the long run, because the recent record points the other way. Over the past year, NOBL returned 18.22%, and FDVV returned 11.38%, a NOBL lead of 6.84 percentage points. Year to date, NOBL is up 15.44% against 7.93% for FDVV, an edge of 7.51 points.
The past month widened the split. NOBL rose 4.16% while FDVV fell 2.51%, a difference of 6.67 points. In delayed quotes from the Thursday, November 19 afternoon session, NOBL traded at $59.15 and FDVV at $59.83. Anyone who bought Fidelity’s fund a year ago has trailed the Aristocrats fund. A switch now means accepting that another stretch like that can happen.
Two Different Rulebooks for Dividend Stocks
The funds choose stocks in different ways. According to its summary prospectus dated September 28, 2026, the ProShares S&P 500 Dividend Aristocrats ETF tracks an index of S&P 500 companies that have increased dividends every year for at least 25 years. The index holds a minimum of 40 companies, weights them equally, and caps any single sector at 30%.
Fidelity’s fund tracks the Fidelity High Dividend Index, which reflects large and mid-sized high-dividend-paying companies expected to keep paying and growing their dividends. The fund normally invests at least 80% of assets in the index’s securities. Put simply, NOBL picks companies by their long record of raising dividends, while FDVV picks higher-dividend companies by Fidelity’s own rules about where those dividends are going.
Who Has the Stronger Case to Move
Long-term investors who want both more income and more growth, particularly those holding the fund through an IRA or 401(k) where a sale triggers no tax, may find FDVV’s five-year and ten-year record most relevant to their goals. Holders who value the 25-year dividend-raising screen above all else, or who have large gains that would be taxed on sale, may find NOBL’s approach a closer fit. Selling shares subject to capital gains tax can trigger capital gains tax that cuts into Fidelity’s edge. Anyone who switches should expect that Fidelity’s fund can lag for a full year, as it just has.
Contact [email protected] for any questions or corrections.
Ryne Mauck is an investment writer covering exchange-traded funds, retirement planning, and portfolio strategy. Through his work at 24/7 Wall St. and other investment platforms, including Seeking Alpha, he aims to provide clear, research-driven insights that help investors make more informed decisions while maintaining a long-term approach to investing.
Ryne holds a B.Sc. in Finance and an M.A. in Political Science. He is a formerly registered Municipal Advisor Representative and has passed the Series 50, Series 63, and Series 65 exams. His articles are not intended to be, nor should they be interpreted as, financial advice.