A Decade Into Marriage and No Shared Finances: Dave Ramsey Offers His Take
Dave Ramsey's response to a caller who had kept separate finances for ten years of marriage cuts to the core of how couples build wealth. Data from his National Study of Millionaires, surveying more than 10,000 households, shows that 80%…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
I’ve never considered myself a Dave Ramsey loyalist. His guidance is designed for people still learning the basics of money management, and that has never been my core challenge. But writing these columns for 24/7 has pushed me to study his approach more closely. And the more I hear from him, the more I understand why his message connects so strongly with so many Americans.
Ramsey has built his following by doing one thing consistently: cutting through excuses and exposing the quiet habits that drain financial stability over time.
One recent call on his show illustrates this clearly. A woman explained that she and her husband had been married for ten years yet still kept their finances completely separate. She had always viewed herself as the more financially disciplined partner and resisted combining money on those grounds. Then she lost her job. With her income gone, she began questioning for the first time whether separate accounts were helping or hurting their long-term financial outlook.
A skeptical listener could read that arc uncharitably: she protected her financial independence while she was earning, and only reconsidered the arrangement when she needed access to her husband’s income. Ramsey’s response, however, went somewhere more useful. He focused on the structural risks couples take when they operate as financial strangers inside the same household.
The wit and wisdom of Dave Ramsey
Ramsey didn’t assign blame or question his caller’s motives. He didn’t suggest she was revisiting the idea simply because a comfortable arrangement had stopped serving her. Instead, he stepped back and asked a more fundamental question: what did the couple actually want to build together, and was their current financial structure helping them get there?
His answer leaned on data. Ramsey’s company conducted the National Study of Millionaires, which surveyed more than 10,000 millionaire households. Nearly 80% of those millionaires were married, and 80% of them credited working together financially with their spouse as central to how they built that wealth. The conclusion Ramsey draws is direct: if building wealth is the goal, combining financial resources with your spouse gives you a statistically significant advantage.
Why would that be?
The logic follows the same principles investors apply every day. A portfolio built around a single asset is efficient when that asset performs, but catastrophic when it doesn’t. Consider a biotech startup whose entire value rests on one experimental drug. If that drug clears every clinical trial and reaches the market, the payoff is enormous. If it fails at phase two, the investment is wiped out. A household where finances are kept entirely separate faces the same fragility. One job loss, one medical crisis, one income disruption, and the financial plan collapses for the partner who had no backup.
Why diversification works
Investors hedge against that kind of single-point failure through diversification, spreading risk across companies, sectors, and asset classes so that no one loss takes down the whole portfolio. Shared household finances operate on the same principle. When two incomes flow into a unified plan, the disappearance of one doesn’t erase the plan itself. The household still has revenue, still has time to recover, and still keeps its long-term goals intact.
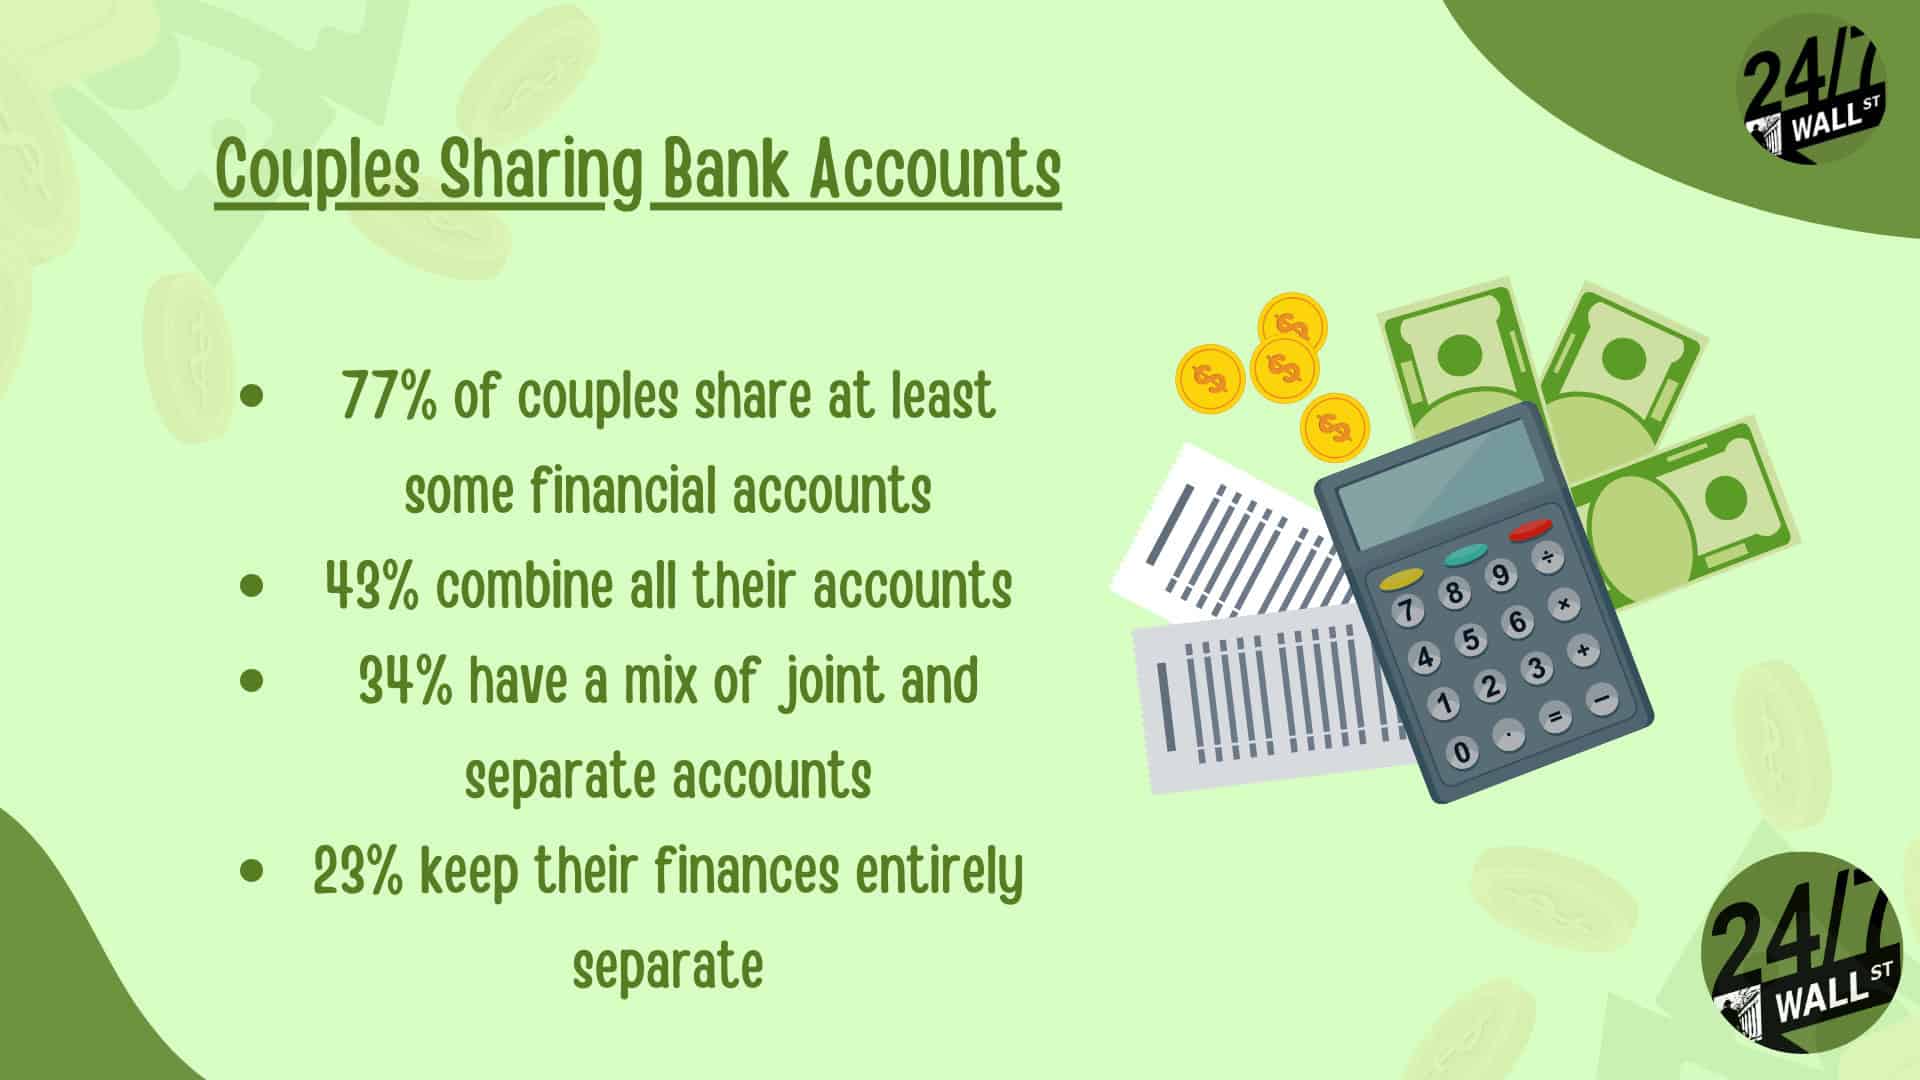
The real-world picture of how couples actually manage money complicates Ramsey’s case, though it doesn’t undermine it. U.S. Census Bureau data from 2023 found that 23% of married couples had no joint bank accounts at all, up from just 15% in 1996. The Census Bureau attributes much of that shift to later marriage: by 2023, the median age at first marriage had climbed to 28.4 years for women and 30.2 for men, up from 24.8 and 27.1 in 1996. Couples who spend their twenties managing their own money naturally resist handing over that independence on their wedding day.
Academic research adds a compelling counterweight. A multi-institution study by researchers from University College London, Notre Dame, and UCLA Anderson found that long-term committed couples who pool all their money into joint accounts report greater relationship satisfaction and are less likely to separate than couples who keep some or all of their money apart. A 2023 study published in the Journal of Consumer Research went further, following 230 engaged or newly married couples over two years and establishing a causal link: couples who were assigned to open joint accounts showed meaningfully higher relationship quality by the end of the study than those who kept separate accounts. That body of evidence broadly supports what Ramsey’s own millionaire data shows.
Not every financial expert agrees with the fully merged approach. Suze Orman has been vocal about maintaining individual accounts within a marriage, warning that complete financial merger can create power imbalances and erode personal autonomy. The debate between Ramsey’s unified-finances model and a hybrid approach (joint accounts for shared goals, individual accounts for personal discretionary spending) is genuine, and couples who married later with established financial lives may find the hybrid structure more practical in the near term.
Returning to the caller’s situation, Ramsey’s guidance was direct. He told the couple to sit down and define their financial goals together first. Once those goals exist on paper, every purchase either partner wants to make can be tested against a shared framework: does this move us closer to where we want to go, or further away? From that foundation, the structure follows naturally. One budget, one set of goals, and whatever incomes the household earns all feeding the same plan rather than two parallel ones running in opposite directions.
That unity of purpose is what separates households that build wealth steadily from those that stall. For the couple on that call, ten years of financial separation hadn’t built a single foundation. It had built two separate ones. The question Ramsey left them with was whether they were ready to replace both with something stronger.
Editor’s note: The Zeta survey figure for couples with separate accounts has been replaced with U.S. Census Bureau data showing 23% of married couples held no joint accounts in 2023, up from 15% in 1996. The UCLA attribution for the joint-finances happiness research has been corrected to reflect the multi-institution study team from University College London, Notre Dame, and UCLA Anderson. A 2023 Journal of Consumer Research study of 230 newlywed couples, which established a causal (not merely correlational) link between joint accounts and relationship quality, has been added.
Contact [email protected] for any questions or corrections.