Married 10 Years, but My Husband Refuses to Combine Finances: Dave Ramsey Responds
Dave Ramsey took a call from a woman who had done everything right, or so she thought. Married ten years, she and her husband still kept their finances entirely separate. She was the responsible partner, and the arrangement had always…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Dave Ramsey took a call from a woman who had done everything right, or so she thought. Married ten years, she and her husband still kept their finances entirely separate. She was the responsible partner, and that arrangement had suited her fine until she lost her job. What came next surprised listeners who expected Ramsey to reach for his usual playbook of pointed financial lectures.
Ramsey skipped the blame entirely and went straight to data. He pointed to a survey his company ran of more than 10,000 millionaire households and to the single financial habit the vast majority of them shared. That finding carries weight well beyond this one couple’s situation, and if your marriage keeps finances separate, here is why Ramsey’s answer is worth understanding.
What the separate-account logic misses
Ramsey’s argument is not that separate finances destroy marriages. His argument is that shared finances build millionaires. The data behind that claim is concrete, and the reasoning holds up well beyond sentiment alone.
The wit and wisdom of Dave Ramsey
Ramsey took a kinder, bigger-picture view of this caller’s situation. He did not assign blame, did not talk down to her, and did not suggest her change of heart was driven by an arrangement that stopped working once she had no income. He focused instead on what the couple hoped to accomplish financially, well beyond this particular setback.
The case he made was statistical. Couples who combine finances tend to report stronger, happier marriages. More striking still, the Ramsey Solutions National Study of Millionaires, which surveyed more than 10,000 millionaire households, found that roughly 80% of those millionaires credited working together financially with their spouse as central to how they built that wealth. Ramsey’s conclusion was direct: keeping finances separate follows a formula with a very low statistical probability of winning at wealth-building or building a high-quality marriage.
Ramsey has been equally plain-spoken on this topic in other settings. “It forces you to set goals together instead of having independent goals,” he told a caller on a separate episode. “Marriages are always growing together or they’re growing apart.” Independent research supports that view. A 2022 study co-authored by researchers at Cornell University and the University of Colorado Boulder, published in the Journal of Personality and Social Psychology, drew on six datasets totaling 38,534 participants and found that couples who pool all of their money report greater relationship satisfaction and are less likely to break up.
Why might combining finances accelerate wealth-building? Consider the analogy of an investor evaluating a single-product company.
If you put money into a biotech startup with one cancer drug in phase 1 trials, that bet might pay off spectacularly if the drug clears later phases and reaches the market. It can also collapse when that single product stumbles, much like a spouse suddenly losing a job. Seasoned investors limit catastrophic risk by spreading capital across companies with multiple products or across a diversified stock portfolio. Diversification may cap some upside (similar to how a spouse with separate finances avoids worrying about the other partner’s spending), but it adds stability. If one revenue stream dries up, another keeps flowing, giving the household time to recover.
Why diversification works inside a household
Diversification of income streams, whether inside a company, a portfolio, or a family, builds the stability that supports consistent long-term wealth growth. The Ramsey Solutions millionaire data makes this tangible. Eight out of 10 millionaires in the study invested in their company’s 401(k) plan, and that step was central to their success. Separately, 89% of those millionaires were first-generation wealth builders who did not inherit their money, and 79% received no inheritance at all from parents or other family members. The path to a seven-figure net worth was a disciplined, decades-long process built on shared effort, not on family money or outsized salaries.
The “roommate” pitfall and the power of one budget
Ramsey’s roommate analogy gets to the structural flaw in the arrangement. When life runs smoothly, separate accounts feel clean and uncomplicated. When a financial emergency arrives, such as a job loss, those clean lines become walls. If one spouse must ask the other for money to cover their share of the bills, the household has effectively split into two financial strangers living under the same roof. Ramsey’s position is that a married couple operating with separate finances functions as roommates with wedding rings, not as a unified team.
The millionaire data reinforces why that dynamic matters. Eight out of 10 millionaires in the Ramsey Solutions study built their net worth through consistent contributions to employer-sponsored 401(k) plans. Separately managed investment paths often produce mismatched risk tolerances, duplicated fees, and gaps in coverage that a jointly managed strategy would close.
Can a hybrid system bridge the gap?
For couples hesitant to give up all financial autonomy, many financial planners suggest a compromise Ramsey typically resists: the “yours, mine, and ours” model. In this approach, all household income flows into a primary joint account to fund bills, savings goals, and investments, while an identical personal allowance goes into each spouse’s individual discretionary account.
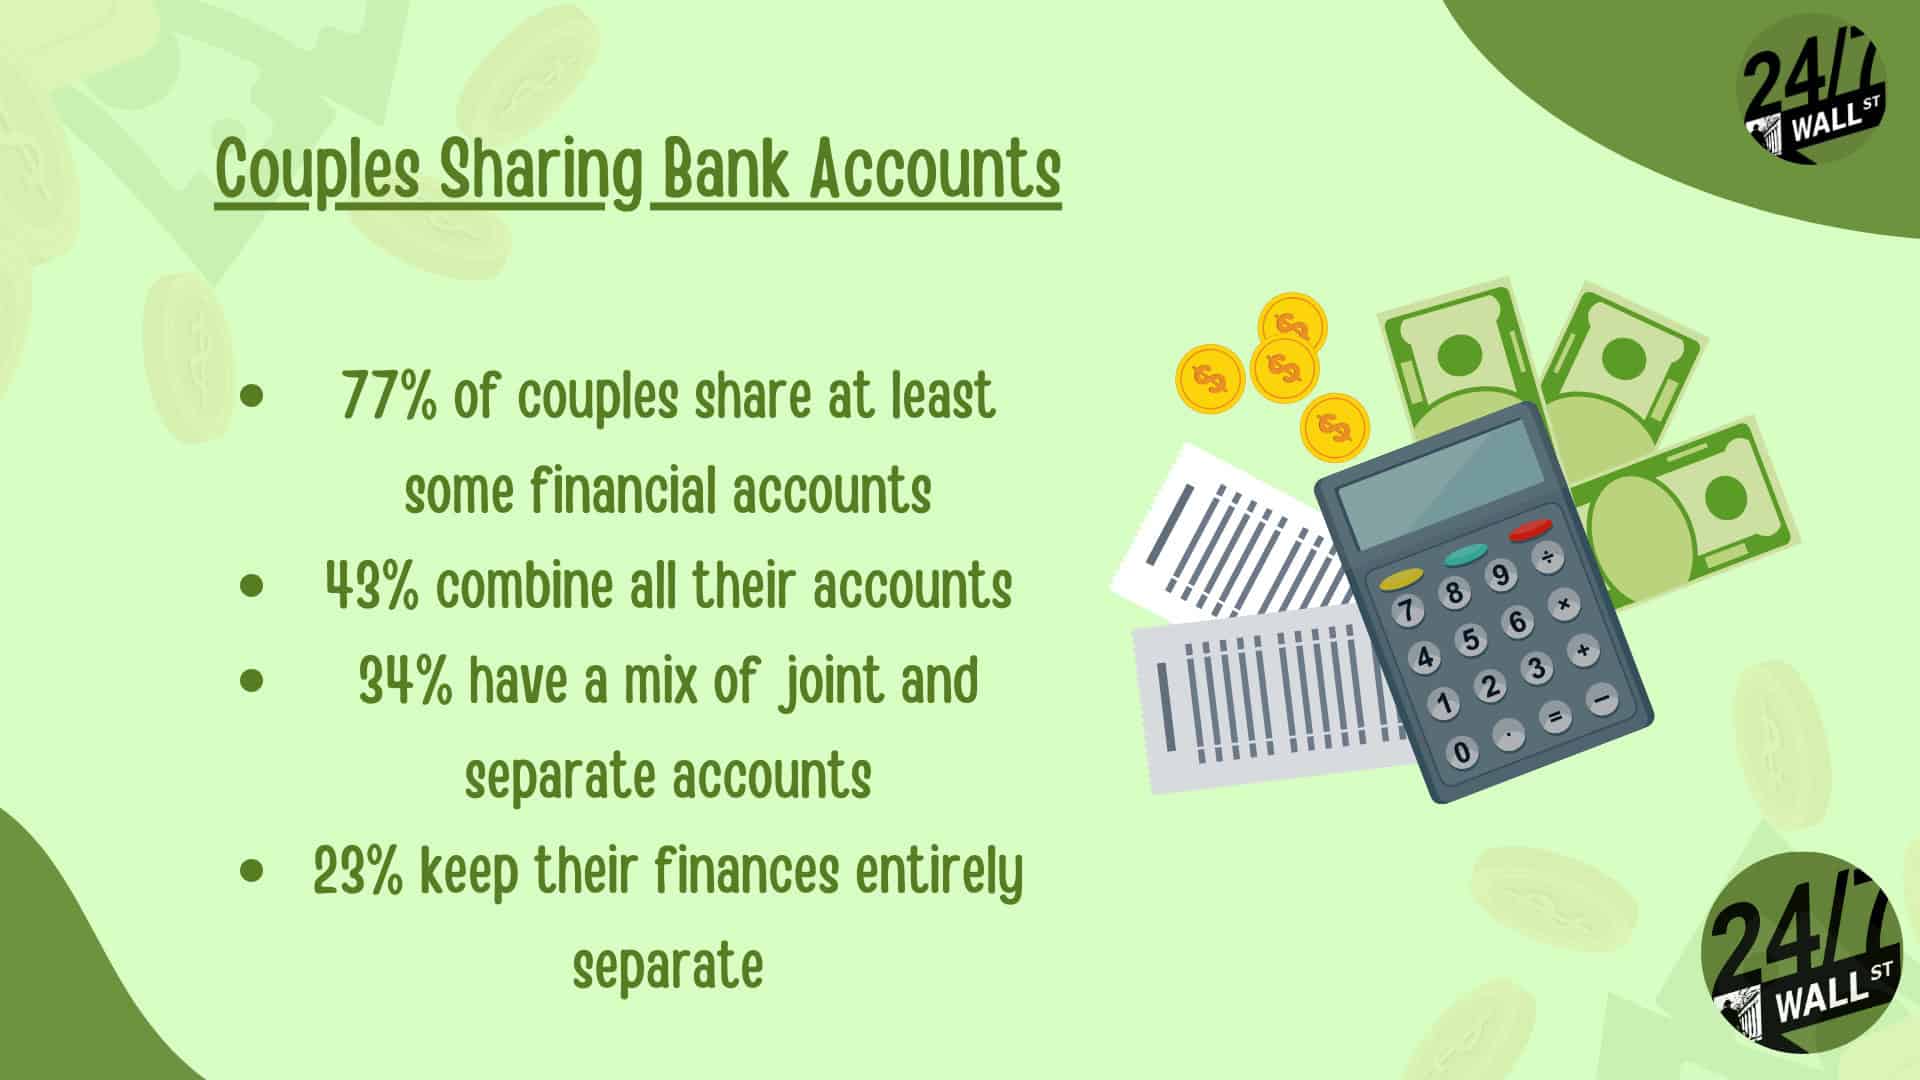
Ramsey warns that separate accounts can breed financial secrecy and what he calls “financial infidelity.” The 2026 WalletHub Money and Relationships Survey found that 26% of Americans have a financial account their partner does not know about, and 72% believe financial disagreements are worse for a relationship than political ones, a reminder that money is rarely just about money. A separate Bankrate survey published in January 2026 found that 45% of Americans in committed relationships say they do not know everything about their partner’s financial situation, and that the secrecy skews younger: 44% of Gen Z respondents lacked full financial transparency with their partner, compared with 64% of Baby Boomers who said they knew everything about their partner’s finances. A TD Bank survey released in August 2026, drawing on 2,000 U.S. adults, added another dimension: 59% of respondents said they had felt scared or embarrassed to discuss finances openly with a partner, and 68% admitted feeling pressure to appear more financially successful than they actually are.
Ramsey’s critics, including financial personality Suze Orman, push back on full consolidation. Orman and her wife KT (Kathy Travis) have never held a joint bank account, and Orman warns that a complete financial merger can create dangerous power imbalances and erode personal autonomy. A fully transparent hybrid system can address both concerns: it keeps the main wealth-building engine unified while preserving a modest lane of individual spending freedom.
Returning to the caller’s situation, Ramsey’s advice was straightforward. The couple should sit down, agree on what they are trying to accomplish financially, and build every spending decision around that shared framework. One checkbook. One budget. One set of goals. One or two incomes feeding the same plan.
Whatever challenges arise along the way, that unity of purpose and pooled income gives a household its strongest shot at reaching long-term wealth targets. As practical financial advice goes, it is hard to argue with the numbers.
Editor’s note: This pass corrects the attribution of the joint-finances study from Cornell University alone to Cornell and UC Boulder (Joe Gladstone, Emily Garbinsky, and Cassie Mogilner), updates the participant count to 38,534 across six datasets, revises the WalletHub hidden-account figure from “more than 1 in 4” to the precise 26%, and updates the Bankrate financial-secrecy statistic to the verified January 2026 figure of 45% of committed partners who say they do not know everything about their partner’s finances, replacing the unverified 42% from an earlier survey.
Contact [email protected] for any questions or corrections.
Joel South covers large-cap stocks, dividend investing, and major market trends, with a focus on earnings analysis, valuation, and turning complex data into actionable insights for investors.
He brings more than 15 years of experience as an investor and financial journalist, including 12 years at The Motley Fool, where he served as an investment analyst, Bureau Chief, and later led the Fool.com investing news desk. He has also co-hosted an investing podcast and appeared across TV and radio discussing market trends.