Jack Bogle’s Money Smart Advice for Anyone Nearing Retirement
The late John C. Bogle built a legacy around a simple but powerful idea: investors don't need to be market experts to succeed; they simply need to minimize costs, stay disciplined, and let compounding do the majority of the work.…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.

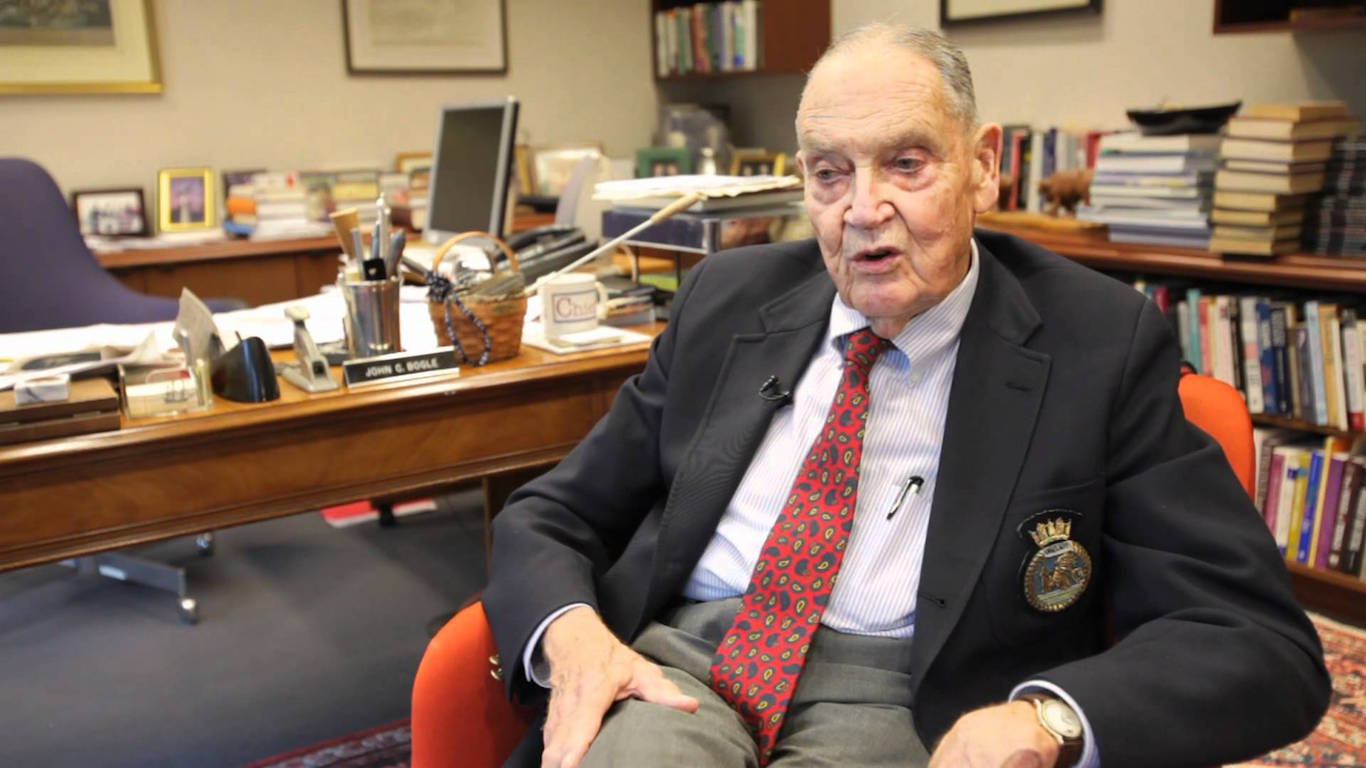
The late John C. Bogle, who died in January 2019, built a legacy around a simple but powerful idea: investors do not need to be market experts to succeed. They simply need to minimize costs, stay disciplined, and let compounding do the heavy lifting. As the founder of The Vanguard Group, which now manages approximately $12 trillion in assets globally, Bogle helped popularize low-cost index investing. His philosophy continues to guide millions of investors today, especially those nearing retirement. Investors who embrace Bogle’s principles of low-cost index funds, diversification, and long-term discipline are affectionately known as Bogleheads.
At its core, Bogle’s counsel emphasized maintaining an appropriate asset allocation and avoiding excessive risk. That may not sound groundbreaking, but a surprising number of retirees shoulder more risk than they can actually afford. After three consecutive years of exceptional gains, markets entered a period of heightened volatility in 2026. Corrections at the individual stock level have tested investor resolve even as major indexes have largely held up.
Both the Vanguard S&P 500 ETF (NYSEARCA:VOO) and the Vanguard Total Stock Market ETF (NYSEARCA:VTI) have weathered periods of turbulence this year, prompting some soon-to-be-retired Bogle followers to wonder whether their equity allocation runs too hot. VOO, the flagship index product Bogle’s philosophy inspired, reached its own landmark on June 2, 2026, when it became the first ETF in history to cross $1 trillion in assets under management, a milestone that underscores just how deeply the low-cost indexing movement has taken hold. How much equity exposure is too much for a retiree? Can you take excessive risk even in the supposedly safer world of bonds?
These questions deserve careful answers, and Bogle’s cautious but optimistic investment beliefs offer a useful framework for thinking through them.
The stock market may deliver lower returns going forward. Accept that reality
The S&P 500 delivered total returns of roughly 26% in 2023, 25% in 2024, and 18% in 2025, a three-year run that set a high bar for expectations. Before that streak, three consecutive years of 15%-plus returns had occurred only a handful of times in the past century. Goldman Sachs (NYSE:GS | GS Price Prediction | GS Price Prediction) raised its year-end S&P 500 target from 7,600 to 8,000 on May 26, following an exceptionally strong first-quarter earnings season in which roughly 85% of index companies beat expectations. The bank’s revised forecast projects S&P 500 earnings per share of $340 for 2026, representing 24% annual growth, with AI infrastructure beneficiaries expected to account for roughly half of that gain.
Even so, the core message for retirees remains unchanged: returns are moderating from the blockbuster gains of the prior three years. Chasing above-average results means accepting above-average risk. A heavy bet on concentrated tech positions might outpace the broader market over some stretch of time, but if that trade sours more sharply than the S&P 500, a portfolio can end up trailing even a modest benchmark. Unless you have decades remaining in your investment timeline, settling for market returns at market risk makes far more sense than reaching for excess gains. Elevated valuations leave little margin for error, particularly for investors who cannot afford to wait out a prolonged recovery.
Bonds carry risk, too
Retirees should aim for an asset allocation that matches their risk tolerance. The classic 60/40 or 40/60 stock-to-bond splits remain popular starting points, though the right mix varies widely by individual circumstances. Either way, bonds are not foolproof safe havens. The 2022 stock and bond market selloff was a stark reminder: both asset classes declined together for the first time since 1977, driven by the Federal Reserve’s aggressive rate-hiking campaign. Stocks and bonds have historically moved in opposite directions, providing genuine diversification benefits, but inflationary conditions can push them into the same downward spiral simultaneously.
Fixed income carries its own hierarchy of risk. Some bonds offer greater safety than others, and the safer ones typically deliver lower yields. Retirees who chase yield in the bond market may believe they are capturing better returns within a conservative asset class, but in practice, higher-yielding bonds carry significantly more credit and duration risk. During downturns they can behave much like equities, defeating the entire purpose of holding them in the first place.
Bogle emphasized keeping an appropriate asset allocation and avoiding excessive risk, particularly in retirement. For retirees seeking to follow that advice, a low-cost basket of high-quality bonds is the most sensible approach. The Vanguard Total Bond Market ETF (NASDAQ:BND) is a widely used core fixed-income holding that tracks the broad U.S. investment-grade bond market at an expense ratio of just 0.03%. The goal is to keep fees low and the investment plan as simple as possible, two enduring pillars of the Bogle philosophy.
The bottom line
Bogle’s philosophy makes the point plainly: investors nearing retirement must stop accepting undue risk in pursuit of better returns. Risking a comfortable retirement for the chance at a great one makes no sense if it means potentially working several more years. If market returns moderate in the years ahead, the right response is to accept the returns that come with an appropriate level of risk and adjust the retirement plan accordingly. Save more if needed, or work a bit longer if the numbers demand it, but keep your nest egg positioned for sustainability rather than speculation.
Editor’s note: This update raises Vanguard’s assets under management to approximately $12 trillion, reflecting 2026 estimates that follow the confirmed $11.6 trillion figure reported as of September 2025. It also adds the June 2, 2026, milestone in which VOO became the first ETF in history to surpass $1 trillion in assets under management, and specifies that Goldman Sachs raised its S&P 500 year-end target to 8,000 on May 26, 2026, following a quarter in which approximately 85% of index companies beat earnings expectations.
Contact [email protected] for any questions or corrections.
Joey is a 24/7 Wall St. contributor and seasoned investment writer whose work can also be found in publications such as The Motley Fool and TipRanks. Holding a B.A.Sc in Computer Engineering from the University of British Columbia (UBC), Joey has leveraged his technical background to provide insightful stock analyses to readers.
Joey's investment philosophy is heavily influenced by Warren Buffett's value investing principles. As a dedicated Buffett disciple, Joey is committed to unearthing value in the tech sector and beyond.