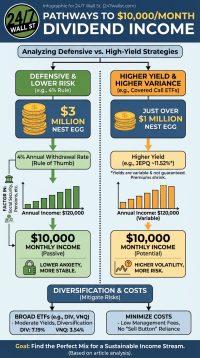
A $1.5 Million Portfolio That Quietly Pays You $83,400 a Year, No Job Required
An $83,400 annual paycheck sits comfortably above the U.S. median household income of roughly $83,730. Replacing that income with a portfolio, no employer required, is the question this article answers. The basic formula is income target divided by yield equals…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
An $83,400 annual paycheck sits comfortably above the U.S. median household income of roughly $83,730, the most recent figure reported by the Census Bureau. Replacing that income with a portfolio, no employer required, is the question this article answers. The basic formula is income target divided by yield equals capital required. The more important issue is what changes across three yield tiers, and why the lowest-yielding option often comes out ahead over time.
Use the roughly 5.6% blended yield implied by the headline as the anchor. $83,400 divided by 0.0556 equals roughly $1,500,000. Lower the yield and the capital requirement rises. Raise the yield and the required capital falls, but the risks change. Here is what each tier actually buys you.
The Conservative Tier: 3% to 4% Yield
This is the dividend-growth-and-blue-chip range. Capital required to generate $83,400 sits at $2,085,000 at 4% and roughly $2,382,857 at 3.5%. The flagship example is the Schwab U.S. Dividend Equity ETF (NYSEARCA:SCHD), a broad dividend-growth fund that tracks the Dow Jones U.S. Dividend 100 Index. After its Q2 2026 rebalance, the fund’s top holdings are led by UnitedHealth, Merck, Abbott Laboratories, and Amgen, with healthcare now accounting for roughly 21% of assets. Chevron and ConocoPhillips are both near 4% and together represent much of the energy sleeve. The expense ratio remains just 0.06%, and total fund assets have grown to approximately $104 billion.
The trade-off is clear: this tier requires the most capital upfront, but the principal is more likely to appreciate and the dividend is more likely to grow. SCHD has returned approximately 28% year to date through mid-August 2026, outpacing the S&P 500 by a wide margin as the market rotated toward value and quality dividend names. That kind of run is not guaranteed to repeat, but it illustrates the compounding power of dividend-growth investing. This is the sleep-at-night tier.
The Moderate Tier: 5% to 7% Yield
Here the capital requirement drops sharply: about $1,191,429 at 7% and roughly $1,635,000 at 5.1%. This is the home of net lease REITs, preferred shares, covered call funds, and high-dividend equity funds. Realty Income (NYSE:O | O Price Prediction) is the standard-bearer, with a dividend yield of approximately 5.2%, an annualized payout of $3.252 per share, and a record of uninterrupted monthly dividends stretching back decades. In June 2026, the company announced its 115th consecutive quarterly dividend increase, which is also the 135th increase since its NYSE listing in 1994.
The updated 2026 AFFO guidance of $4.44 to $4.45 per share, raised from the prior range of $4.41 to $4.44, implies approximately 4% growth at the midpoint. That is a meaningful improvement from earlier in the year and signals management’s confidence in the portfolio’s momentum. Even so, the trade-off versus the conservative tier remains. REIT distributions are taxed as ordinary income rather than qualified dividends, which matters significantly in a taxable account at higher brackets.
The Aggressive Tier: 8% to 14% Yield
Capital required falls to $834,000 at 10% and $695,000 at 12%. This is the territory of business development companies, mortgage REITs, leveraged covered call funds, and high-yield bond funds. The income is real, but principal erosion is common. Distributions get cut. Many of these instruments pay you out of capital rather than earnings, and the price chart often slopes down even as the checks arrive. The result is spending down the asset rather than living off its growth.
Why Lower Yields Often Win
A 3.5% yield that grows 8% annually doubles the income in roughly nine years. A 12% yield with no growth stays flat, or shrinks. With the 10-year Treasury yielding approximately 4.72% as of late August 2026, the opportunity cost of leaving money in cash is real, but so is the inflation drag on fixed income streams. Purchasing power preservation is the real game. Starting at $83,400 with 8% income growth gets you to roughly $166,800 within a decade. Starting at $83,400 flat keeps you at $83,400 while prices continue to rise.
Three Things to Do This Week
- Calculate actual spending, not gross income. If you net roughly $80,100 after federal tax on a qualified-dividend-heavy mix, your real replacement number is lower than $83,400.
- Compare 10-year total returns of a dividend-growth ETF against a high-yield product. Total return, not just yield, is what funds retirement.
- Model REIT distribution taxes in your bracket. Net lease REIT income is ordinary, not qualified. The same headline yield can produce very different after-tax results depending on account type.

Editor’s note: This update corrects the U.S. median household income to $83,730 (2024 Census Bureau data, up from the 2023 figure of $80,610 used previously), refreshes SCHD’s net assets to approximately $104 billion and top holdings to reflect the post-Q2 2026 rebalance (UnitedHealth, Merck, Abbott, Amgen, Chevron now lead the fund), updates Realty Income’s consecutive quarterly dividend increase count to 115, raises its annualized payout to $3.252 per share and 2026 AFFO guidance to $4.44-$4.45 per share at roughly 4% growth, updates the dividend yield to approximately 5.2%, and revises the 10-year Treasury yield reference to approximately 4.72% as of late August 2026.
Contact [email protected] for any questions or corrections.
Drew Wood has edited or ghostwritten nine books and published more than 1,500 articles on investing, business, politics, travel, world cultures, wildlife, and earth science. He holds a doctorate and four master's degrees and has nearly 30 years of college teaching experience. His travels have taken him to 25 countries, including three years living in Ukraine.