Millions of Retirees Could See Their Social Security Increase if This Bill Passes

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
For millions of older Americans, Social Security is the foundation of retirement income. The average retired worker was collecting about $2,076 per month as of February 2026, and for most people that amount is far less than their monthly retirement expenses. Many retirees now keep working to close that gap, whether through part-time shifts or full-time jobs.
That pressure helps explain why a growing number of retirees return to work after they begin collecting benefits. Some take on part-time work to cover the shortfall, while others go back to full-time positions because their budgets cannot absorb the difference.
A February 2026 AARP survey found that 7% of retirees had reentered the labor force in the prior six months, up from 6% in the summer of 2025. Nearly half (48%) named money as their primary reason for returning to work, while 14% said they wanted to stay active.
Financial strain also shows up in the Schroders 2026 US Retirement Survey, fielded from March 20 to April 15, 2026, among 1,500 US investors including 382 retired Americans. Nearly one in five retirees describe themselves as struggling financially, and 49% say their retirement expenses are higher than they expected.
The same survey found that more than half of retirees (58%) do not know how long their savings will last. Retirees also devote an average of 16% of their monthly income to healthcare, covering premiums, prescriptions, and out-of-pocket costs. Those figures explain why supplemental work income has become a necessity for many households.
Retirees who claim Social Security before full retirement age (FRA) run into the retirement earnings test when they work. Companion bills in both chambers of Congress would eliminate that test entirely.
How the earnings test works and why critics want it repealed
For 2026, beneficiaries who are under FRA for the full year lose $1 in benefits for every $2 they earn above $24,480. In the year they reach FRA, a higher limit of $65,160 applies, and $1 is withheld for every $3 earned above it, counting only earnings before the month they reach FRA.
The withholding is not permanent. After a beneficiary reaches FRA, the Social Security Administration recalculates the benefit and credits back the months when checks were reduced. For retirees on tight budgets, though, smaller monthly checks can still cause real hardship even when the money eventually returns.
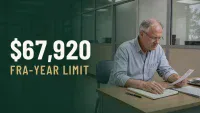
The limits rise for 2027. The Social Security Administration set the lower exempt amount at $25,560 for people under FRA all year, and the higher amount at $67,920 for those reaching FRA during 2027.
Lawmakers introduced companion bills to repeal the test. Sen. Rick Scott (R-FL) introduced S.4184, the Senior Citizens’ Freedom to Work Act of 2026, on March 24, 2026, with Sen. Tommy Tuberville as cosponsor. The bill was referred to the Senate Finance Committee. Rep. Greg Murphy (R-N.C.) introduced the House version, H.R. 8344, on April 16, 2026, and it was referred to the House Ways and Means Committee. Scott presented the Senate proposal at a Senate Special Committee on Aging hearing on older Americans in the workforce.
The earnings test dates to the original Social Security Act of 1935. Supporters of repeal argue that a rule rooted in that era no longer fits an economy where experienced workers are in demand and many people work well past the ages earlier generations did.
Critics also point to a transparency problem. Although withheld benefits are eventually returned, many retirees do not fully understand how the adjustment works, so they may cut back on hours or turn down wages they could have earned without any lasting cost to their benefits.
Why supporters see a larger payoff
Backers of the legislation argue that the earnings test penalizes work at a time when the economy needs experienced employees and many retirees need extra income. Repeal would let beneficiaries accept more hours or return to full-time jobs without tracking their wages against a federal threshold each year.
The proposal also carries a long-term argument for Social Security’s finances. More older Americans in the labor force means more payroll tax contributions flowing into a program that relies heavily on that revenue to meet its scheduled benefits.
On October 14, 2026, the Social Security Administration announced a 3.6% cost-of-living adjustment for 2027, which will apply to benefits for 76 million Americans. It is the largest annual increase since 2023, and it adds an average of $75 per month for retirees. Even so, the increase is still not enough for many retirees to keep pace with rising food, energy, and healthcare costs.
Both bills remain in committee. Congress.gov still lists the Senate bill’s latest action as its March 24 referral, and GovTrack gives it a 0% chance of enactment. Neither bill has passed its chamber, so early claimants still follow the current 2026 limits until Congress acts.
Repeal would be one of the more substantial changes to Social Security’s work rules in years. For now, retirees who claim early should plan around the existing limits, which rise to $25,560 in 2027.
Editor’s note: The article now reflects the 3.6% 2027 COLA that the Social Security Administration announced on October 14, 2026, along with the 2027 earnings test limits of $25,560 and $67,920. It also confirms that both repeal bills remain in committee, and it replaces the earlier 2026 average benefit figure with the February 2026 amount.
Contact [email protected] for any questions or corrections.
Maurie Backman has more than a decade of experience writing about financial topics, including retirement, investing, Social Security, and real estate. Her work has appeared on sites that include The Motley Fool, USA Today, U.S. News & World Report, The Washington Post, and Kiplinger.
Prior to becoming a full-time financial writer, Maurie worked in the financial industry trading distressed debt. She then changed course and spent a few years designing electronic toys. After a stint in content marketing and UX, she shifted back into writing and has since covered everything from the housing market to estate planning to Medicare.
When she's not busy writing, Maurie can be found hiking, walking her dogs, driving her kids to their various sports practices and games, and curling up with a good book. She cooks on occasion and bakes way too often.