Leave Your Kids a Roth Instead of a Traditional IRA and They Get 10 Extra Years of Tax-Free Compounding plus a $0 Tax Bill at the End

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
If you own a Traditional IRA and plan to leave it to your children, the IRS may be waiting for a share of it. Convert the account to a Roth first, and your children can receive roughly a decade of tax-free compounding inside an inherited Roth IRA, then withdraw the money without owing federal income tax on qualified distributions. That is the lesser-known advantage tucked inside the SECURE Act‘s 10-year rule, a provision most estate plans gloss over.
The Buried Rule Nobody Explains at Account Opening
Under the SECURE Act, a non-spouse heir who inherits an IRA generally has to empty the account within 10 years of the original owner’s death. Heirs of a Traditional IRA owe ordinary income tax on every dollar they withdraw. Heirs of a Roth generally owe no federal tax on qualified withdrawals. An inherited Roth also carries no annual required minimum distribution during that decade, so the money can stay invested and compound for the full window before a single lump sum is taken in year 10.
The gap widens for a Traditional IRA. If the original owner died after the required beginning date, which is age 73 under SECURE 2.0, heirs must take annual distributions and still empty the account by year 10. Each withdrawal is taxed at the heir’s own marginal rate, and that yearly tax bill chips away at the balance over the full decade.
Where the Rule Actually Lives
The 10-year rule sits in Section 401(a)(9) of the Internal Revenue Code. The SECURE Act of 2019 rewrote that section, and the IRS followed with final regulations, Treasury Decision 10001, in July 2024 to explain how the rule operates. Those regulations took effect for distributions beginning in 2025. The IRS had waived penalties for missed distributions from 2021 through 2024, so 2025 marked the first year the rules were fully enforced. IRS Publication 590-B covers the distribution mechanics for both Traditional and Roth inherited accounts.
Who Gets the 10-Year Clock (and Who Doesn’t)
The 10-year rule applies to “non-eligible designated beneficiaries,” the IRS term for adult children, grandchildren, nieces, nephews, and most other non-spouse heirs. Five categories of “eligible designated beneficiaries” keep the life-expectancy payout option: a surviving spouse, a minor child of the owner, a disabled individual, a chronically ill individual, and someone no more than 10 years younger than the owner.
A minor child keeps that treatment only until age 21. The IRS set 21 as the age of majority nationwide, regardless of state law, and the 10-year clock then starts, leaving the account empty by age 31. A healthy 40-year-old adult child, by contrast, falls straight into the 10-year window without any of those protections.
How the One Big Beautiful Bill Changes the Math
The conversion calculus shifted when the One Big Beautiful Bill Act (OBBBA) was signed into law on July 4, 2025. The legislation made the lower individual rates from the 2017 tax law permanent, which removed the threat of a bracket increase that had pushed many IRA owners toward rushed conversions. It also created a $6,000 deduction for taxpayers age 65 and older, which applies for tax years 2025 through 2028. That deduction phases out above $75,000 of income for single filers and $150,000 for joint filers, so the benefit shrinks for higher-income conversion years.
The OBBBA also raised the state and local tax (SALT) deduction cap. It rose from $10,000 to $40,000 for 2025 and $40,400 for 2026, increases 1% a year through 2029, and then reverts to $10,000 on January 1, 2030. For 2026, the phase-down begins once modified adjusted gross income exceeds $505,000 (the 2025 threshold was $500,000). Above that level, the cap shrinks by 30 cents per dollar of income, but it never drops below $10,000. A large Roth conversion can push income past that line, so the timing of the conversion matters for itemizers in high-tax states.
Conversions remain open to owners of any age, and no ceiling limits the amount converted. What the law changed is the urgency. Before its passage, owners feared a rate spike after 2025. With rates now set for longer, the decision depends more on bracket management, the likely tax bracket of your heirs, and how many years remain for the Roth to compound.
How to Actually Pull This Off
- Convert Traditional IRA dollars to a Roth in years when your taxable income is unusually low, such as after retirement but before Social Security starts, or during a gap between jobs.
- Pay the conversion tax from a taxable account rather than from the IRA itself. Paying from the IRA shrinks the balance your heirs eventually inherit.
- Name beneficiaries directly on the account. A will does not override an IRA beneficiary form.
- Start the Roth’s 5-year clock early. Opening and funding a Roth, even with $100, years before a large conversion starts that timeline.
- Tell your heirs about the deadline. Missing a required withdrawal can trigger a 25% excise tax on the shortfall, which drops to 10% if it is corrected within the window.
The Rate Backdrop
Interest rates are part of the planning picture. The Federal Reserve raised its target range to 3.75% to 4.00% in September, its first increase in over three years. The Fed’s October statement kept that range in place, with two officials dissenting in favor of another hike. The 10-year Treasury yield reached 4.98% on November 10, 2026, after briefly topping 5% during trading, as hotter-than-expected inflation data drove bonds lower. Rising yields make the investment return on an inherited account more important, but the tax treatment remains the main reason a Roth can outperform a Traditional IRA for heirs.
The Catch Nobody Mentions
Roth conversions cannot be undone. Federal law no longer allows recharacterization, so once you convert, you owe the tax at your current bracket. If your children sit in much lower brackets than you do, converting could cost the family more in total than letting them inherit the Traditional IRA and pay tax over 10 years. Run the numbers in both directions before you commit.
Two more traps deserve attention. First, the Roth’s own 5-year rule has to be satisfied at your death for earnings to pass to heirs tax-free. If you open a new Roth through a conversion and die three years later, earnings withdrawn before that account reaches its fifth anniversary are taxable to your heirs, while contributions and converted principal still come out tax-free. Second, state income tax on conversion income varies widely. Some states add a meaningful surcharge, while Florida and Texas levy no state income tax at all. Confirm your state’s treatment before you convert.
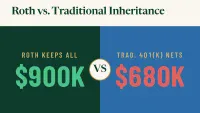
The core trade is simple. You pay tax now so your children get 10 years of untaxed compounding and no federal bill at the end. With a Traditional IRA, the IRS takes a share of the ending balance. With a Roth, your children keep all of it.
Editor’s note: This update refreshes the 10-year Treasury yield to 4.98% as of November 10, 2026, and confirms the Fed funds target range at 3.75% to 4.00%. It also adds the 2026 SALT phase-down threshold of $505,000, the income phaseouts for the $6,000 senior deduction, and the 25% excise tax on missed inherited IRA distributions, which falls to 10% if corrected.
Contact [email protected] for any questions or corrections.
I am a long time investor and student of business, and believe finding good companies that can become great investments is the best game on earth. After 20 years of writing and researching the public markets it is clear that individuals have never had more tools and information to take control of their financial lives. From ETFs and $0 commissions to cryptos and prediction markets there has never been a greater democratization of access to investing.
I write to help people understand the investments available to them so they can make the best choice for their portfolio, whether they're starting out or looking for income in retirement.