Nursing Homes Run Nearly $10,000 a Month. A Federal Rule Called “Spousal Impoverishment Protection” Lets the At-Home Spouse Keep the House, the Car, and Six Figures of Savings
Most couples burn through their life savings before anyone tells them the federal government already built a financial firewall for exactly this situation. What it protects, and the traps that cancel it out, depend entirely on decisions made before the…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
If one spouse is heading into a nursing home and the other is staying put, the federal government has a rule most families never hear about until they have already burned through savings. It is called Medicaid spousal impoverishment protection, and it lets the at-home spouse (the “community spouse”) keep the house, a car, personal belongings, and a protected slice of the couple’s cash, all while the other spouse qualifies for Medicaid long-term care coverage.
Skilled nursing care now runs roughly $9,581 a month for a semi-private room and about $10,978 a month for a private room, according to CareScout’s 2026 Cost of Care Survey. Private-pay stays at either price point wipe out ordinary households with startling speed. The U.S. personal savings rate stood at 2.8% in Q2 2026, according to the Bureau of Economic Analysis, and the average American household carries far less cushion than a single year of nursing home bills would require. That is exactly the gap this federal rule was designed to address.
What the Rule Actually Does
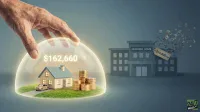
Two protections do the heavy lifting. The Community Spouse Resource Allowance (CSRA) lets the at-home spouse keep a protected share of the couple’s countable assets, rather than spend down to the single-applicant limit. In 2026, the federal framework sets a CSRA floor of $32,532 and a ceiling of $162,660; states can place their own standard anywhere within that band, and some simply adopt the full federal maximum. The Minimum Monthly Maintenance Needs Allowance (MMMNA) addresses income: when the community spouse’s own monthly income falls below a set floor, income from the institutionalized spouse (Social Security, pension, or other sources) is redirected to the at-home spouse before any of it flows to the nursing home. The 2026 federal MMMNA floor is $2,705 a month for most states, with a ceiling of $4,066.50.
Several asset categories are excluded from the countable pool altogether: the primary residence (subject to a home equity limit), one vehicle, personal belongings and household goods, and certain prepaid burial arrangements.
The Statute Behind It
This protection is federal law: Section 1924 of the Social Security Act (42 U.S.C. §1396r-5), enacted through the Medicare Catastrophic Coverage Act of 1988 and administered through Centers for Medicare and Medicaid Services (CMS) guidance updated annually. The CMS Informational Bulletin issued April 27, 2026, set the current CSRA and MMMNA figures. Because those numbers move every year and vary by state, always verify current amounts with your state Medicaid agency or an elder law attorney before planning around a specific dollar figure.
Who Qualifies, Who Doesn’t
Eligibility applies when a married couple faces institutionalization: one spouse is entering (or applying to enter) a nursing facility, or is receiving Medicaid home- and community-based waiver services, typically for a stay expected to last at least 30 consecutive days. The community spouse is not required to be sick, elderly, or applying for Medicaid themselves. Unmarried individuals, same-household non-spouse caregivers, and adult children living in the home receive no CSRA or MMMNA protection, though separate, narrower provisions can sometimes protect a caretaker child.
How to Actually Put It to Work
- Order a “snapshot” assessment. On the date the ill spouse first enters a medical facility for 30 or more consecutive days, the state freezes a picture of all countable assets. That snapshot date determines the CSRA calculation.
- Separate exempt from countable assets. The home, one car, household goods, and prepaid burial arrangements are set aside. Everything else (bank accounts, CDs, brokerage accounts, and most retirement accounts, depending on the state) enters the countable pool.
- Calculate the community spouse’s share. The at-home spouse retains the protected portion up to that year’s applicable CSRA cap. The applicant spouse must generally spend down remaining countable assets to the individual limit, which is $2,000 in most states.
- Run the income test. If the community spouse’s own monthly income falls short of the MMMNA floor, income from the institutionalized spouse is redirected to close the gap before any of it is paid to the nursing home.
- Deploy the protected cash. Even conservatively invested, six figures of protected savings generates real income. The FDIC national average 12-month CD yield was 1.68% APY as of July 2026, a baseline that competitive online banks typically exceed by a wide margin, with top rates near 4.50% APY as of mid-August 2026.
The Traps That Sink People
Three stand out and deserve serious attention before any planning begins.
First is the five-year lookback. Medicaid reviews asset transfers made in the 60 months before the application date. Gifts to children, transfers at below-market value, or funding a trust at the last minute can all trigger a penalty period during which Medicaid pays nothing, even if the nursing home bill is already arriving.
Second is state variation. The CSRA can be calculated as half of countable assets (subject to the federal floor and ceiling) or as the full state maximum. Income rules also differ. Some states are meaningfully more generous than the federal baseline, while others hew closely to the minimum. Knowing which method your state uses changes the math considerably.
Third is Medicaid estate recovery. After both spouses have died, the state can file a claim against the estate, including the home that was shielded during life, to recoup what Medicaid paid for care. The protected residence is not exempt from recovery; it is only deferred.
This is one of the least DIY-friendly corners of personal finance. Before retitling a single account or writing a check to a child, sit down with a certified elder law attorney licensed in your state.
Editor’s note: This article was updated to reflect 2026 nursing home cost figures from CareScout’s Cost of Care Survey, which show semi-private rooms averaging approximately $9,581 a month and private rooms approximately $10,978 a month, and to add the specific 2026 federal CSRA limits ($32,532 minimum and $162,660 maximum) and the 2026 MMMNA range ($2,705 to $4,066.50 per month) from the CMS Informational Bulletin issued April 27, 2026.
Contact [email protected] for any questions or corrections.
Jake has been been working in financial media for almost 15 years. He focuses on all things personal finance for 24/7 Wall St. with high hopes to educate and entertain. Most recently, Jake spent 12 years working various roles at The Motley Fool. He started copy editing fool.com content, worked on premium and marketing campaigns, and helped launch The Ascent, a personal finance brand.
His work has been featured on platforms like MSN, Yahoo Finance, USA Today, and more. He's written about credit cards, social security, ETFs, savings accounts, and just about anything else you can imagine when thinking about money. Jake love to cook, play golf, and tell people he's never had a cavity. (It's true!)