Dave Ramsey Warns About a $10 Million Family Financial Disaster: “He Dumped His Kids on the Railroad Track”
A woman signed a few documents for her father-in-law as a family favor, and Dave Ramsey says she may have just handed a lender the legal right to come after everything she has.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
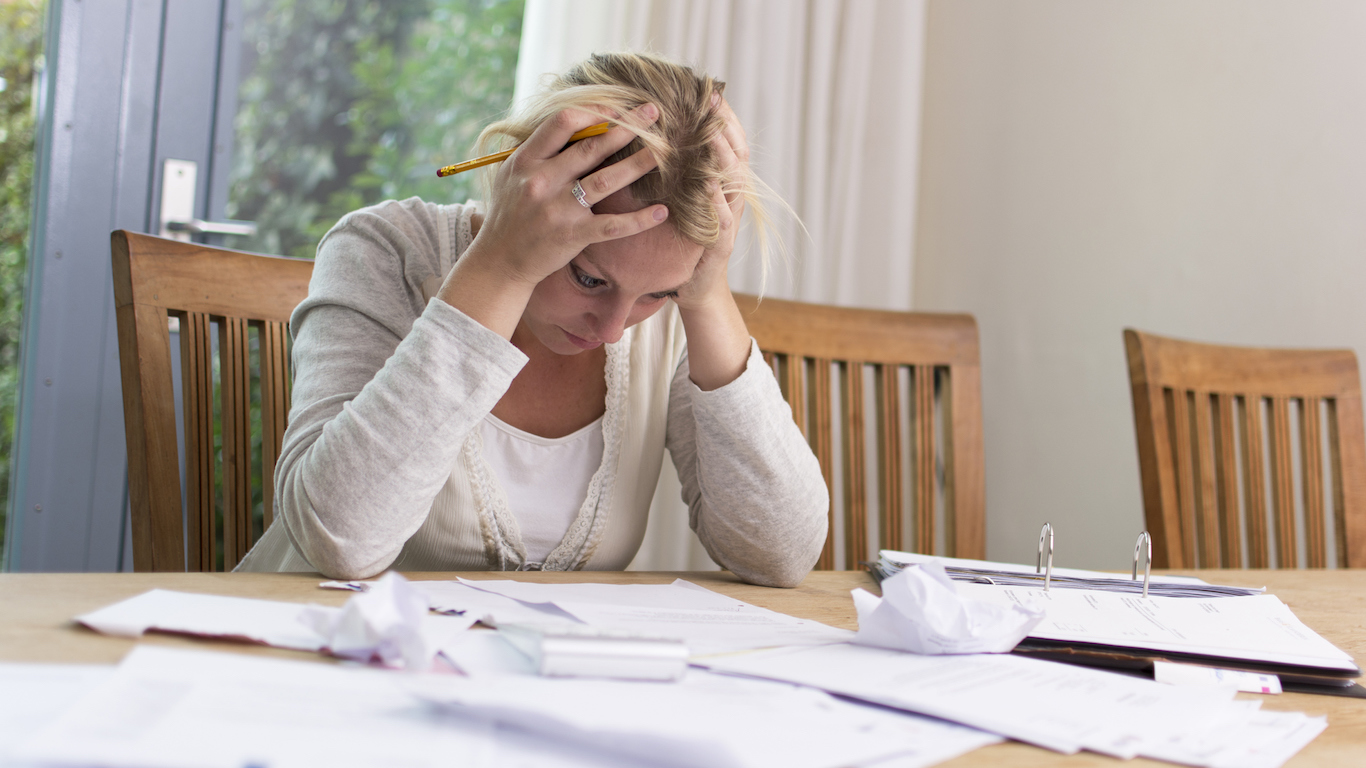
Signing a few documents for a family member can feel like a harmless act of loyalty. For one woman, Dave Ramsey says that instinct may have cost her everything: her signature on documents for her father-in-law put her on the hook for a $10 million loan.
The caller, Robert, age 34, from Philadelphia, explained that his father-in-law got into a “giant mess with the IRS” back in 2015 or 2016 and now owes several hundred thousand dollars in back taxes. To shield real estate from that liability, the father transferred commercial properties into the names of his wife and her two adult daughters, including Robert’s wife.
Robert’s wife personally guaranteed a $10 million loan tied to those properties. Robert told Ramsey the properties are appraised at $7 million and are now heading to a sheriff’s sale. After sitting down with a bankruptcy attorney, Robert put his wife’s net worth at just $29,000.
“He dumped his kids on the railroad track and here comes the train,” Dave Ramsey said after hearing the situation laid out in full. He called the father a “shyster” and made clear that affection for family does not cancel legal liability.
Signing Put Her on the Hook for $10 Million
Robert explained how his wife ended up exposed: “She kind of preemptively just said, hey, you know, it’s my father, he asked me to sign some documents.” That single act of trust carries an enormous legal consequence. A signature on a personal guarantee makes the signer individually liable for the entire debt obligation, regardless of whether she ever touched a dollar of the loan proceeds.
Ramsey called the father’s arrangement fraud and did not soften his assessment: “He is arrogant enough; he thought this was all going to work out. He probably did not set out to harm his children, but he’s just an idiot.” The legal exposure runs deeper than just the lender. When a debtor transfers assets to family members specifically to put them out of reach of creditors, courts and the IRS can use fraudulent transfer law to unwind those moves and pull the recipients into the mess. Under the Uniform Fraudulent Transfer Act, a transfer made with the intent to hinder, delay, or defraud any creditor can be set aside entirely. The IRS has its own tools on top of that, using transferee liability to pursue the people who received the assets as if the original debtor still held them.
With the $10 million loan sitting against a $7 million appraisal, the family is already $3 million underwater before a single bid is placed at the sheriff’s sale. When a commercial property sells at foreclosure for less than the outstanding loan balance, the lender generally has the right to pursue guarantors for the remaining deficiency. Robert’s wife and her sisters did not create this problem, but their names on those guarantee documents mean they own it legally.
Dave Ramsey Says Not to File Bankruptcy Yet
The family may still escape the worst of this, but only if the lender decides the guarantors are not worth chasing. Even though Robert’s wife and her two sisters are technically liable, a bank’s legal team calculates whether the expected recovery justifies the cost of pursuit. Three guarantors with modest assets and the credible threat of a bankruptcy filing are not an attractive collection target.
“If I’m the banker, I’m looking at this, I’m going, whatever I’m going to get out of this deal, I’m going to get out of these properties because these three kids are all filing BK,” Ramsey said. “Filing today is premature. They may never come after her just because they know she’s not a rich target.“
If the bank does make a demand, Ramsey floated a symbolic settlement offer of $20,000 as a way to close the file cleanly rather than drag the family into a prolonged bankruptcy. The logic is straightforward: if the lender refuses that offer, it collects nothing, because the guarantor has no meaningful assets to seize. Suing someone with a $29,000 net worth can easily cost the bank more in legal fees than it recovers. Filing for bankruptcy protection before anyone has actually demanded payment would burn an option that might never need to be used.
Anyone actually facing a personal guarantee claim or IRS exposure should consult a qualified bankruptcy and tax attorney before taking any action. This article does not constitute legal, tax, or bankruptcy advice.
The Takeaway
Ramsey summed up the family’s immediate future with characteristic bluntness: “Thanksgiving’s gonna be weird.”
The broader lesson is one Ramsey returns to repeatedly: never put your name on a loan, guarantee, property deed, or any other financial document, even for someone you love, until you understand exactly what happens if everything goes wrong. Good intentions do not override contract law, and courts do not make exceptions for family loyalty.
Editor’s note: This revision added legal context on fraudulent transfer law and IRS transferee liability tools that can reach family members who receive moved assets, as well as the deficiency judgment risk guarantors face when a commercial property sells at sheriff’s sale below the loan balance. Ramsey’s characterization of the father as a “shyster,” confirmed in multiple sources, was also incorporated.
Contact [email protected] for any questions or corrections.
Thomas Richmond is a financial writer and content strategist with 5+ years of experience covering stocks and financial markets. He has published over 500 articles focused on individual stock analysis, helping investors better understand business fundamentals, stock valuations, and long-term opportunities.
Thomas previously served as a Content Lead at TIKR, a stock research platform, where he helped scale the company’s blog to hundreds of articles per month and contributed to a weekly newsletter reaching more than 100,000 investors.
Outside of work, Thomas enjoys weight lifting and soccer.