A West Texas Ranch Got $1.3 Million for Water Rights. For a Medicare-Age Landowner, the Premium Bill Can Arrive Two Years Later
A seven-figure water rights deal sounds like a windfall, but for a Medicare-age landowner the bill that matters most shows up two years after closing, long after the money is gone.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
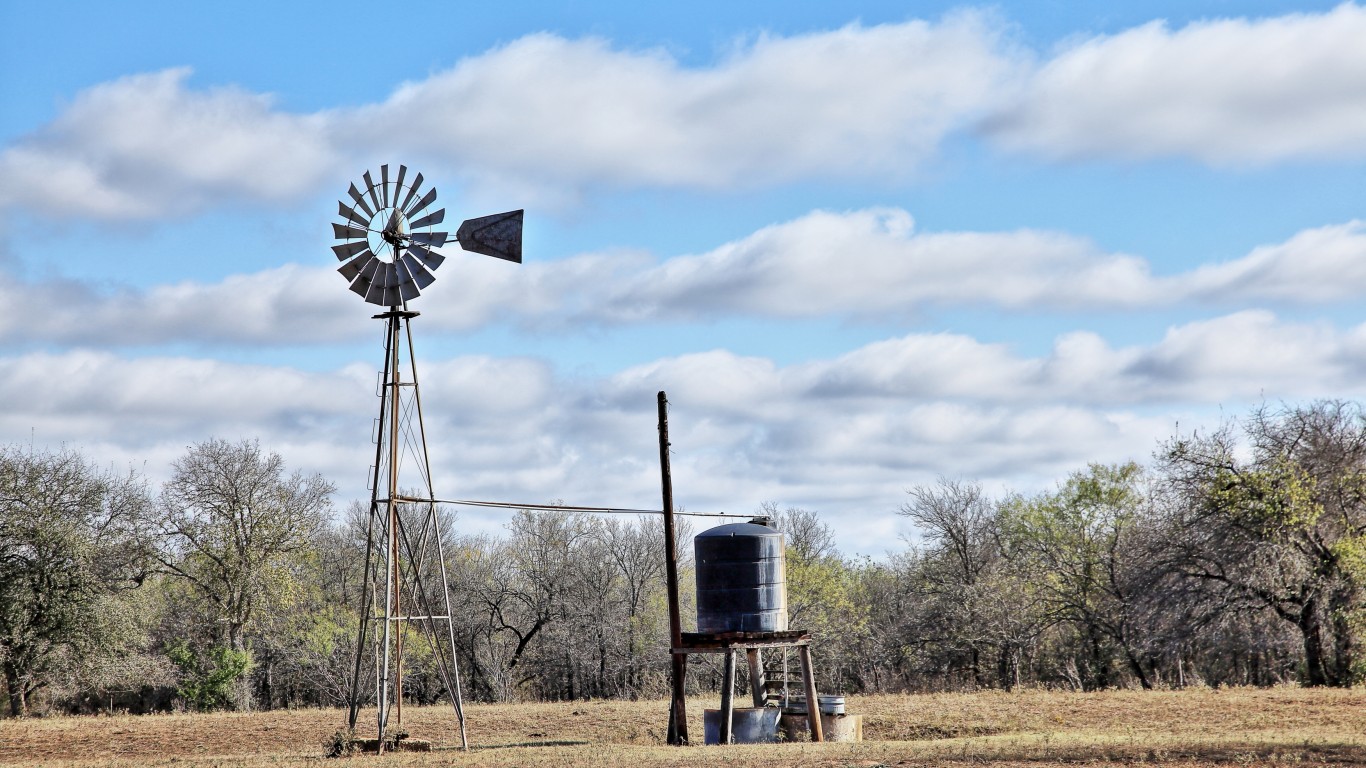
The Colorado River Municipal Water District, a utility based roughly 150 miles away that supplies Abilene, Midland, and Odessa, has paid La Escalera Ranch $1.3 million for what the Houston Chronicle describes as a kind of hold on the water. Under the groundwater option agreement, if and when the utility begins pumping, it will pay at least another $2 million annually. The deal was finalized last year and made public this summer.
It made news as a water story. For a landowner on Medicare, or approaching 65, a deal shaped like this one is also a premium story.
Say a hypothetical rancher in his mid-sixties signs an option like that one. He holds the land personally rather than through a corporation, he is two years into Medicare, and his wife enrolls next year. What happens to his Medicare premium turns less on the size of the check than on when the income is recognized and how it’s characterized. Neither answer arrives quickly.
Why the Premium Arrives Late
IRMAA, the Income-Related Monthly Adjustment Amount, reaches roughly 8% of people with Medicare Part B. If household modified adjusted gross income (MAGI) sits well under $109,000 single or $218,000 joint, none of this reaches you either.
The Social Security Administration normally sets IRMAA from the tax return filed two years earlier. It can reach back further when necessary, and it can use more recent information after certain appeals. But the working rule is a two-year lag, which means a large income event does not surface in a Medicare premium until two calendars later, long after the money has been spent or reinvested.
MAGI here is adjusted gross income (AGI) plus tax-exempt interest. Municipal bond coupons that feel tax-free still count. A landowner who parks a large check in a muni-portfolio to hold down taxable income will still watch that interest appear inside the number Medicare uses.
So he cashes the check and nothing happens. His next Medicare premium looks exactly like his last one. So does the one after that. The bill for this check is two years out, and by the time it lands, the money is spent, invested, or both.
Not Every Dollar Is Income
How much of that $1.3 million reaches his AGI is a different question from how much he received, and this is where a seven-figure headline misleads. Only the resulting taxable income or gain reaches AGI, not the gross payment.
Treatment depends on whether a payment is option consideration, lease income, proceeds from a sale of water rights, or something else, and on basis and entity structure. An option payment is not automatically taxable on receipt. A sale generates gain measured against basis. Recurring per-acre-foot payments may look more like rent or royalty income. Which one applies determines how much, if anything, lands in the IRMAA calculation.
That same uncertainty is why installment-sale treatment under IRC Section 453 is not a strategy to assume. It requires a qualifying disposition of property. An option or lease payment does not automatically qualify, and IRS Publication 537 lays out the conditions. Whether it is available is a question for a tax advisor reading the actual agreement.
What the Surcharge Costs
If the taxable portion carries him into the top tier, here is what a year costs. The 2026 figures are useful illustratively, though thresholds and premiums for later years have not been published.
The first surcharge tier, above $109,000 single or $218,000 joint, adds $81.20 per month in Part B and $14.50 in Part D, per person. The top tier, at or above $500,000 single or $750,000 joint, adds $487.00 per month in Part B, bringing the total Part B premium to $689.90, plus $91.00 per month in Part D on top of the plan’s own premium. For a married couple both on Medicare, those are per-person amounts.
The cliffs are what hurt. Crossing a threshold by a single dollar adds the entire tier for 12 months.
Surcharges like these, and the other coverage traps retirees walk into, are mapped in our free Medicare guide.
SSA-44 Will Not Rescue a Voluntary Sale
Form SSA-44 lets a beneficiary appeal an IRMAA determination, but only after a qualifying life-changing event: marriage, divorce, death of a spouse, work stoppage or reduction, loss of income-producing property through disaster or condemnation rather than sale, loss of a pension, or an employer settlement.
A voluntary asset sale, a water-rights deal, or a Roth conversion does not qualify. The surcharge stands.
Watch the survivor situation too. If he dies before the premium year arrives, his wife files single, and single thresholds sit below joint thresholds at every tier. The published top tier begins at $500,000 for a single filer against $750,000 for a couple, so income the two of them would have absorbed together can land on her alone.
The Window That’s Still Open
Here’s what to do before the brackets that will govern that premium are even published:
- Model the two-year window before closing, not after. Income recognized in one calendar year drives the premium two years out. A closing moved from late December into January shifts the entire consequence a year down the road, including for a spouse who will be newly enrolled by then.
- Ask the tax advisor how the payment is characterized before assuming anything about Medicare. The structure determines whether a surcharge is even in play.
- Price the cliff, not the bracket. If projected MAGI lands near a threshold, deferring a Roth conversion or harvesting a capital loss can keep a household on the cheaper side. Ordinary itemized charitable deductions generally do not reduce AGI and will not help here, though a qualified charitable distribution can, as can a properly structured gift of appreciated property made before a binding sale.
He will not feel the water check as a Medicare event for two years. By the time he does, every decision that could have shaped it is already behind him.
Contact [email protected] for any questions or corrections.
Gerelyn Terzo is the author of dividend investing handbook "Dividend Investing Strategies: How to Have Your Cake & Eat It Too." A veteran financial journalist, she covers agri-finance for outlets like Global AgInvesting and the broader stock market and personal finance for 24/7 Wall Street. She began at CNBC and later helped launch Fox Business in New York. Gerelyn currently resides in Woodland Park, Colorado and dabbles in nature photography as a hobby.