She Inherited Her Sister’s $200,000 IRA at 61. Their Younger Brother Inherited the Same Amount at 48. Only One of Them Has to Empty It in 10 Years
Two siblings inherited identical IRAs from the same person, yet one faces a brutal 10-year drain during peak earnings while the other stretches withdrawals for decades. The difference comes down to a single age-based rule buried in the tax code…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
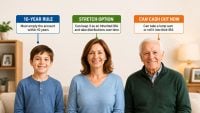
Two siblings inherit identical $200,000 traditional IRAs from the same older sister, who died at 65. The 61-year-old inheriting sister can spread withdrawals across her remaining life expectancy. The 48-year-old brother must drain his entire account by the end of the tenth year after their sister’s death. The decedent, the dollar amount, and the account type are identical, yet the tax outcomes diverge completely. One provision buried in the Eligible Designated Beneficiary rules, which almost no account owner reads before dying, explains the whole difference.
Two Siblings, One IRA, Two Deadlines
The SECURE Act of 2019 ended the old stretch IRA for most non-spouse beneficiaries. Anyone inheriting a retirement account from an owner who died after December 31, 2019 generally has to empty it within 10 years. That is the default. The exceptions are narrow and collectively called Eligible Designated Beneficiaries.
Five categories qualify: a surviving spouse, a minor child of the account owner, a disabled individual, a chronically ill individual, and any individual not more than 10 years younger than the decedent. That final category is the sibling rule. The test compares each beneficiary’s age to the person who died, not to any fixed cutoff, so the same beneficiary can qualify under one relative’s account and fail under another’s. The deceased sister was 65. Her 61-year-old sister is four years younger and clears the bar. Her 48-year-old brother is 17 years younger and does not.
Why One Path Stretches and the Other Compresses
Congress wrote the 10-year rule to accelerate tax collection on inherited retirement accounts. The old stretch let a young beneficiary draw tiny required distributions across decades while the untouched balance kept compounding tax-deferred. An eligible beneficiary who uses the life expectancy method takes the first distribution in the year after the owner’s death, using a divisor from the IRS Single Life Table based on her age that year. The divisor drops by one each subsequent year. The account can last for decades.
For a beneficiary subject to the 10-year rule, whether annual withdrawals are also required during that window depends on whether the original owner had already started their own required minimum distributions before dying. Under SECURE 2.0, the required beginning date is currently age 73 for most retirees (rising to 75 for those born in 1960 or later). If the original owner died before reaching that threshold, the beneficiary can defer and take the entire balance in a single withdrawal on the last day of year 10. If the owner had already begun RMDs, annual distributions must continue throughout the 10-year window, and the balance must still be zero by the deadline. The IRS resolved years of uncertainty by issuing final regulations in July 2024 (Treasury Decision 10001), with full enforcement beginning in 2025 after penalty waivers covered 2021 through 2024.
Tax Bill Hidden Inside the 10-Year Window
Every dollar coming out of a traditional inherited IRA is taxed as ordinary income. The 48-year-old brother is deep in his peak earning years, and draining $200,000 over a decade adds tens of thousands of extra taxable dollars to his annual income. If the account grows during the payout period, the later withdrawals will be even larger.
That additional income can push him into a higher federal bracket than the original owner ever reached. It can also trip income-based thresholds like IRMAA surcharges once he approaches Medicare age. The 61-year-old sister, spreading withdrawals across her own life expectancy and likely retiring sometime during that payout stretch, controls her marginal rate year by year. Her brother has no such flexibility.
Edge Cases Every Account Owner Should Know
A minor child of the account owner receives life expectancy treatment only until age 21, at which point the 10-year clock starts. A disabled or chronically ill beneficiary keeps the stretch for life. An eligible beneficiary who dies midway through her stretch hands the remainder to a successor beneficiary, who must then finish emptying the account within 10 years of that second death. The penalty for missing a required distribution fell from 50% of the shortfall to 25% under SECURE 2.0, further reduced to 10% if corrected within a two-year window. One rule applies universally: a non-spouse beneficiary cannot roll an inherited account into their own IRA under any circumstance.
What to Check on Your Beneficiary Form This Month
Beneficiary designations override wills, and most people fill in the form once and never revisit it. A Roth conversion during the owner’s lifetime does not remove the 10-year rule for a non-eligible beneficiary, but it makes eventual withdrawals generally tax-free, which neutralizes the bracket problem entirely. Naming a trust as beneficiary triggers a separate set of see-through rules that genuinely require a specialist to navigate.
A careful review of the beneficiary designations on file with the IRA custodian can reveal heirs who are more than 10 years younger than the account owner. Those beneficiaries will inherit under the 10-year rule, with the resulting tax bill landing squarely in their working years. The account owner can address this during their lifetime. Once they are gone, that option closes permanently.
Editor’s note: This article was updated to specify that the minor child’s eligible designated beneficiary status ends at age 21 (not simply at “the age of majority”), to note that the IRS issued final regulations in July 2024 (Treasury Decision 10001) resolving long-standing uncertainty about annual RMDs during the 10-year window, and to add that penalty waivers covered 2021 through 2024 with full enforcement beginning in 2025. The current required beginning date of age 73 under SECURE 2.0, rising to 75 for those born in 1960 or later, was also added as relevant context for determining whether annual distributions are required within the 10-year window.
Contact [email protected] for any questions or corrections.
David Beren has been a Flywheel Publishing contributor since 2022. Writing for 24/7 Wall St. since 2023, David loves to write about topics of all shapes and sizes. As a technology expert, David focuses heavily on consumer electronics brands, automobiles, and general technology. He has previously written for LifeWire, formerly About.com. As a part-time freelance writer, David’s “day job” has been working on and leading social media for multiple Fortune 100 brands. David loves the flexibility of this field and its ability to reach customers exactly where they like to spend their time. Additionally, David previously published his own blog, TmoNews.com, which reached 3 million readers in its first year. In addition to freelance and social media work, David loves to spend time with his family and children and relive the glory days of video game consoles by playing any retro game console he can get his hands on.