A Couple Who Retires at 60 With $700,000 in Two 401(k)s and Lives on His Pension for 13 Years Will Meet About $50,000 of Required Withdrawals at 73, on Top of the Pension

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Picture a couple who retire at 60. His pension pays the bills, so their two 401(k)s, worth $700,000 combined, stay put. For 13 years, nothing about their money feels urgent. Behind that calm, two things grow quietly: the account balances and the tax bill that shows up once required withdrawals start at 73. Here is how a pension changes the usual advice for those in-between years, and which strategies suit a pension household instead.
A Pension Fills the Brackets Conversion Advice Assumes Are Empty
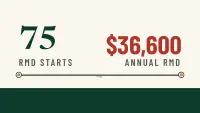
Required minimum distributions, or RMDs, are the annual withdrawals the IRS forces you to take from traditional retirement accounts. Under current rules, they start at age 73 for anyone born between 1951 and 1959. Those born in 1960 or later face the same obligation but not until age 75, a distinction that matters for couples planning a long pre-RMD window. Standard advice says to use the quiet years before that threshold for Roth conversions, meaning you pay tax now so later withdrawals are tax-free while your income is low. That plan assumes your taxable income is low, and a pensioner’s isn’t.
According to IRS Publication 554, pension income is generally fully taxable when no after-tax money went into the plan. Assume his pension pays $100,000 a year. After the 2026 joint standard deduction of $32,200, that leaves $67,800 of taxable income before anyone touches a 401(k).
Couples filing jointly see the 10% bracket end at $24,800 and the 12% bracket end at $100,800. The pension has already consumed the bottom bracket and most of the next one, leaving just $33,000 of room at 12%. It reclaims that space every year, whether the couple needs the income or not.
A cost-of-living adjustment changes how this plays out. Some pensions raise payments periodically, while others pay a flat amount. Because brackets are indexed to inflation, a flat pension slowly loses ground against them and gradually frees up conversion room. A pension that grows with inflation, by contrast, keeps filling the same space for life.
What 13 Untouched Years Build
Assume a 5% annual return and no withdrawals. At that rate, the $700,000 grows to about $1.32 million by age 73. Divide that by the IRS Uniform Lifetime Table factor of 26.5, and the first RMD comes to roughly $49,810.
Social Security benefits then stack on top. Assume the couple’s combined benefits are $40,000 by then. Once a joint filer’s combined income passes $44,000, up to 85% of Social Security becomes taxable, and a six-figure pension crosses that line on its own. The pension, the RMD, and the taxable portion of Social Security add up to about $183,810 in gross income.
Using today’s figures, the extra standard deduction of $1,650 per married spouse age 65 or older brings taxable income to about $148,310. That places the top of the RMD squarely in the 22% bracket, which runs to $211,400 for joint filers. Their pension already spent the lower brackets before the first withdrawal ever arrived.
Medicare Surcharges Can Bind Before the Brackets Do
Medicare’s income-related monthly adjustment amount, or IRMAA, adds to Part B and Part D premiums once joint modified adjusted gross income exceeds $218,000 in 2026. The first surcharge tier alone can cost each spouse an extra $81.20 to $487 a month on Part B, and the charge is based on your tax return from two years earlier. Each spouse enrolled in Medicare pays it separately, which doubles the household’s exposure.
In this model, the couple’s income sits about $34,190 below the IRMAA line before any conversion. A bigger conversion, or several years of pension raises, could push them over. For a pension household, the surcharge may simply be part of the cost of having steady guaranteed income. A spouse’s death can later reduce income significantly. Social Security Form SSA-44 lets you request a premium reduction after such a life-changing event.
When One Spouse Is Left
Many pensions pay a reduced benefit to the surviving spouse, typically under a joint-and-survivor option, and spouses generally must give written consent to waive their rights to that protection. A widow files as single, with a 2026 standard deduction of $16,100.
Her 24% bracket starts at $105,700, and her IRMAA surcharge line is $109,000. Her pension may shrink under the survivor option, but the RMDs on the combined account balance stay just as large. The gap between those two lines is narrow enough that even a modest RMD could push her into both.
Moves That Still Work for Pensioners
- Qualified charitable distributions. From age 70½, IRA owners can send up to $111,000 to charity in 2026, up from $108,000 in 2025. The gift counts toward the RMD and is excluded from income entirely, though 401(k) money must first be rolled into an IRA to use this route.
- Spend from the accounts early. Living partly on 401(k) withdrawals in your 60s, even without converting, shrinks the balance the first RMD is calculated on.
- Convert into 22% on purpose. That makes sense when the alternative later is 22% plus a Medicare surcharge, or 24% as a widow.
- Coordinate both accounts. Each spouse’s RMD depends on their own age and balance, so decide whose account to draw down first.
- Rethink the Social Security claiming date. Delaying keeps benefits out of your 60s brackets, but larger checks later add pressure to an already full income picture.
The Calculation to Run Each Autumn
A pension provides steady, predictable income, and that is precisely what makes standard Roth conversion advice a poor fit for a pension household. Each fall, add up all income sources, subtract the standard deduction, then see how much room remains under your target bracket and the IRMAA line that will apply two years out. If the answer is close to zero, plan around the coming RMDs. If there’s room, you can use that space until December 31.
Editor’s note: This update adds the SECURE 2.0 clarification that the RMD starting age rises to 75 for those born in 1960 or later, notes the 2026 QCD limit of $111,000 (up from $108,000 in 2025), and includes the IRMAA Part B surcharge range of $81.20 to $487 per month per person at the first surcharge tier.
Contact [email protected] for any questions or corrections.
David Beren has been a Flywheel Publishing contributor since 2022. Writing for 24/7 Wall St. since 2023, David loves to write about topics of all shapes and sizes. As a technology expert, David focuses heavily on consumer electronics brands, automobiles, and general technology. He has previously written for LifeWire, formerly About.com. As a part-time freelance writer, David’s “day job” has been working on and leading social media for multiple Fortune 100 brands. David loves the flexibility of this field and its ability to reach customers exactly where they like to spend their time. Additionally, David previously published his own blog, TmoNews.com, which reached 3 million readers in its first year. In addition to freelance and social media work, David loves to spend time with his family and children and relive the glory days of video game consoles by playing any retro game console he can get his hands on.