She Will Hire the Aide Her Neighbor Recommends at $28 an Hour. The Long-Term Care Policy She’s Paid Into for 18 Years Will Pay $0 if the Contract Requires an Agency
After 18 years of premiums, a widow assumes her long-term care policy will cover the aide her neighbor swears by. Then she reads two words in the definitions section that could make every dollar of coverage disappear.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
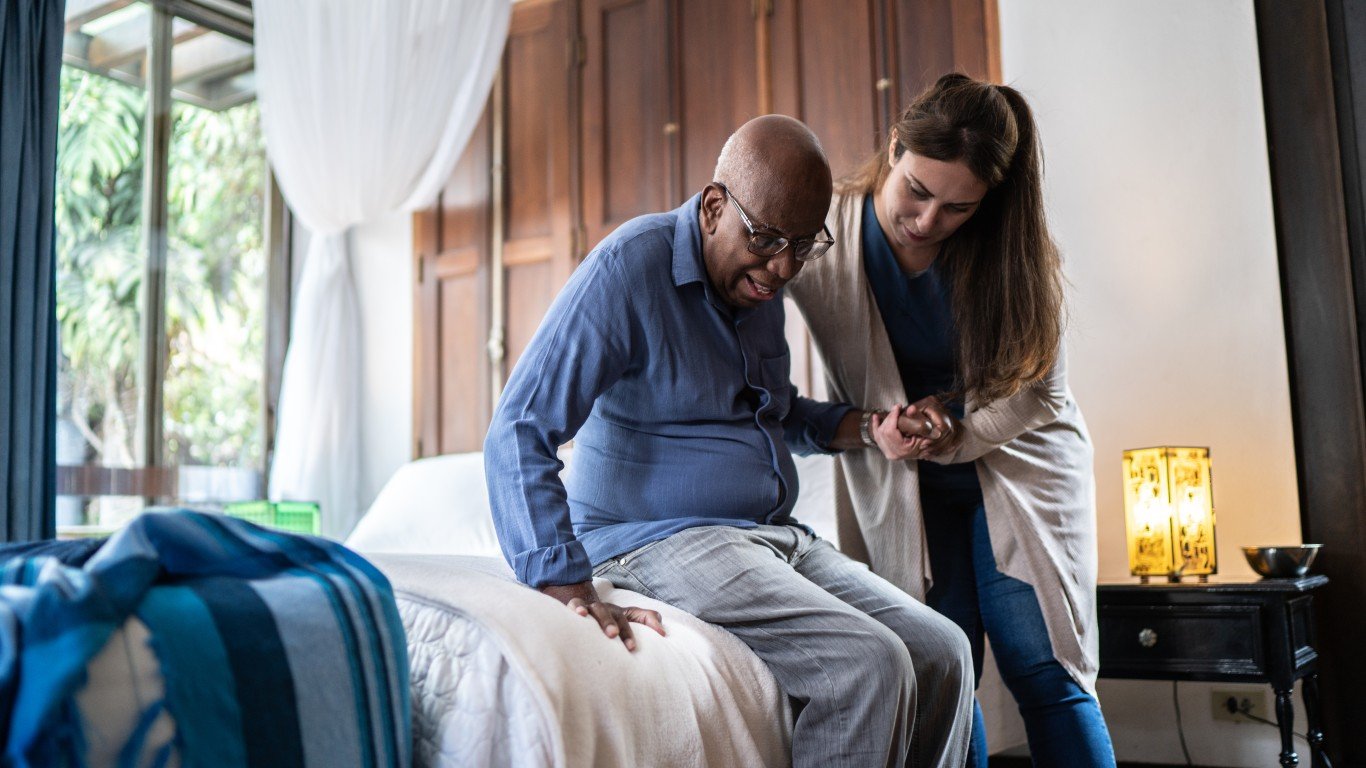
Picture a widow who needs help getting through the day. Her neighbor swears by the aide who cared for her own mother. The aide shows up on time, already knows where the coffee filters live, and charges $28 an hour. The widow wants that arrangement: one familiar person in her house every morning, with no rotation of agency strangers.
She pulls out the long-term care policy she’s paid into for 18 years, sure it’ll cover the bill. Then she reads the home-care definition. The policy pays for services from a qualifying, licensed home health agency. The neighbor’s aide could give her exactly the care she needs, and the policy could still pay $0.
How a Licensed-Agency Clause Stops a $28-an-Hour Aide From Being Covered
Long-term care policies have two requirements. First, she has to qualify for care. Second, the care has to come from a covered provider. Most families focus on the first gate and never read the definitions section behind it.
In her contract, the provider definition decides everything. If it says home care must come from a licensed agency, an independent aide falls outside it, no matter how skilled, kind or affordable she is. The insurer checks whether the person who gave the care fits the contract’s wording, regardless of the care’s quality.
That’s why the neighbor’s recommendation, reasonable as it is, can leave the widow paying the full $28 an hour herself while the policy sits unused in a drawer.
Why the Policy’s Definition of a Covered Caregiver Matters
State insurance rules put limits on how home-care coverage can be written, but they don’t guarantee that every person a family hires will qualify. The National Association of Insurance Commissioners (NAIC) model regulation lets policies define providers by licensing, certification or registration requirements, while also placing limits on how narrowly home-care benefits can be restricted. The policy and the law in the state where it was issued have to be read together.
The model also allows policies to exclude services provided by a member of the covered person’s immediate family. So the daughter who moves back home to help can run into the same wall as the neighbor’s aide.
Each state’s version differs. If the state doesn’t license or certify that kind of caregiver, the policy may have to spell out what the provider must meet instead. That’s why the answer lives in both her contract and the rules where it was issued, not in a general promise that the policy “covers home care.”
Why an 18-Year-Old Policy Is Stricter
The age of the policy matters. A contract written 18 years ago reflects the care market and policy language of its time, and its definitions may not match the way families hire caregivers today. The coverage she remembers buying and the contract sitting in the filing cabinet can feel like two different things. Only the contract decides what gets reimbursed.
Meeting the Benefit Trigger Doesn’t Release the Money on Its Own
Policies measure need through activities of daily living. For tax-qualified contracts, federal law lists six: eating, toileting, transferring, bathing, dressing, and continence, and the insurer must consider at least five of them when deciding whether someone is chronically ill. Cognitive impairment, such as dementia, can also trigger benefits.
Suppose she clearly qualifies. She can’t bathe or dress without help, and a doctor documents it. She passes the first gate. If her chosen aide fails the provider definition, she still gets nothing for that aide’s hours. Families often find this split during the first claim, after weeks of care they assumed was covered.
Get the Insurer’s Answer in Writing Before the Aide’s First Shift
The fix requires a phone call and some patience, and it works best before anyone is hired. Families who handle this well ask the insurer to confirm in writing which caregivers qualify under the contract:
- An independent aide hired directly
- A family member, paid or unpaid
- A worker placed through a caregiver registry
- Only a licensed home health agency
They also ask whether the insurer needs preapproval or a formal plan of care before benefits start. Missing a paperwork step can delay or reduce payments even when the caregiver qualifies.
A written answer gives the widow real options. If only agencies qualify, she can ask whether the aide she trusts works through an agency, or could, so she keeps the familiar face and stays inside the contract. If independent aides qualify with conditions, she learns those conditions before the first bill arrives instead of after the denial letter.
Why a $0 Benefit Costs More Than the $28 Rate
The $28 hourly rate is the number she’ll notice. The bigger number is the $0 reimbursement she could get after 18 years of premiums, all because one hiring decision didn’t match one definition.
The contract can’t be rewritten once care begins, but the choice of caregiver can still change. Reading the provider definition before hiring anyone can be the difference between an aide the policy helps pay for and a $28-an-hour bill the widow carries herself.
Contact [email protected] for any questions or corrections.
Gerelyn Terzo is the author of dividend investing handbook "Dividend Investing Strategies: How to Have Your Cake & Eat It Too." A veteran financial journalist, she covers agri-finance for outlets like Global AgInvesting and the broader stock market and personal finance for 24/7 Wall Street. She began at CNBC and later helped launch Fox Business in New York. Gerelyn currently resides in Woodland Park, Colorado and dabbles in nature photography as a hobby.