A Dad Bought His Kids a House and Had $6,000 Left. Dave Ramsey Had a Warning
When a father called Dave Ramsey carrying two mortgages and only $6,000 in savings, the answer he got was blunt enough to rattle every parent who has ever tried to give their kids a financial head start.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
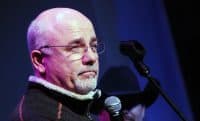
A father named James called The Ramsey Show with two mortgages and shrinking savings. One loan was on his own home in Missouri. The other was on a house he had bought for his children to live in. The kids had since moved out, and he was still paying it. His savings were down to $6,000.
Dave Ramsey, the debt-free radio host, didn’t soften his answer on the October 15 episode, titled “Build A Life That Doesn’t Depend On Debt”: “Buying your kids a house to live in is causing you to face bankruptcy. I want everybody to hear that out there.”
If you’re near retirement, this mistake costs you the years when your savings should grow fastest. Every dollar that goes to a child’s mortgage is a dollar your own retirement never gets.
Ramsey Gets This One Right, and the Math Shows Why
James makes $6,900 a month from his main job. Since January, he has added roughly $2,000 a month from a second job. Ramsey’s answer: “8,900 bucks is not enough to cover all the bills and both mortgages.” His way out was to have an agent get an offer on the house. James should bring any offer below the loan balance to the lender as a short sale.
Ramsey is correct. A house you buy for your kids belongs on your balance sheet. Your paycheck is the only payment source the lender can count on.
Here is a simple example using hypothetical figures. Say a parent carries a $2,000 monthly payment on a child’s house for 10 years. That adds up to $240,000 out of pocket.
Putting the same $2,000 a month into a retirement account earning 7% a year grows to about $346,170 after a decade.
Take 4% of that, and it pays roughly $13,847 a year in retirement income. That income is what the house really costs you.
The timing hurts too. In 2026, workers aged 60 to 63 can put up to $35,750 into a 401(k). A $24,000 annual house payment uses up most of that room.
Many older families can’t spare it. Those led by someone aged 55 to 69 already hold 24% of all U.S. home mortgage debt.
Can the House Cover Its Own Costs Without Your Paycheck?
One question decides whether a house for the kids is risky or catastrophic: does the property pay for itself?
In the first case, the kids pay rent that covers the full $2,000 payment. The parent’s out-of-pocket cost is near zero, and the parent owns property in a rising market. The Case-Shiller national index is up 2% over the past year. The risk remains, though. Your name is on the loan, so a missed rent check means you owe the payment.
In the second case, the kids move out, and nobody pays rent. Now $24,000 a year comes straight out of your cash flow. Property taxes, insurance, and repairs add to that. This is where James ended up. One family’s income is carrying two mortgages, and a $6,000 emergency fund is the only backstop.
The first case can turn into the second with one phone call from your kid. When you run your numbers, plan for the empty-house version.
Ways to Help Your Kids Without Draining Your Retirement
- Fund your own retirement first. In 2026, the standard 401(k) limit is $24,500. Workers 50 and older can add $8,000, and workers 60 to 63 can add $11,250. Only money left over after those contributions is safe to give away.
- Give a fixed gift toward a down payment. Pick a dollar amount, write one check, and put the loan in your child’s name. A gift has a limit. A mortgage keeps billing you every month for decades.
- Keep your name off their loan and title. Ramsey gave the same warning to an earlier caller who was still on an ex-spouse’s mortgage: “It’s all nice until it’s not.” If the person living in the house misses a payment, your credit takes the hit.
- If you’re already in James’s position, set a deadline. Get a market value from an agent this month. Write down your monthly shortfall and divide your savings by it. The answer is how many months you can keep going. If your kids won’t take over the loan and rent won’t cover the payment, sell. If you owe more than the house is worth, ask your lender about a short sale.
A gift you can afford ends when you write the check, but a mortgage you can’t afford follows you into retirement.
Contact [email protected] for any questions or corrections.
Chris Lange is a financial and geopolitical writer with more than a decade of experience covering a myriad of topics. He has published thousands of articles for 24/7 Wall St., with past coverage focused heavily on stocks, IPOs, healthcare, defense, global affairs, and technology.
His work has been quoted, or referenced by a number of outlets including Business Insider, USA Today, Yahoo Finance, MSN, The Motley Fool, and many other publications. A graduate of Southwestern University, he studied business with a focus on investments and has previous experience in banking and startups.
When not reading or writing the news, he is following his passion for Lacrosse, playing chess, or building solar projects with his dad.