‘It’s a House of Cards, Literally’: Dave Ramsey Show Host to Flipper Who Bought at $400K and Owes His Dad $250K
A 30-year-old contractor in Milwaukee thinks he is sitting on a fortune in real estate equity, but one Ramsey Show host compared his financial setup to a house of cards and meant it literally.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
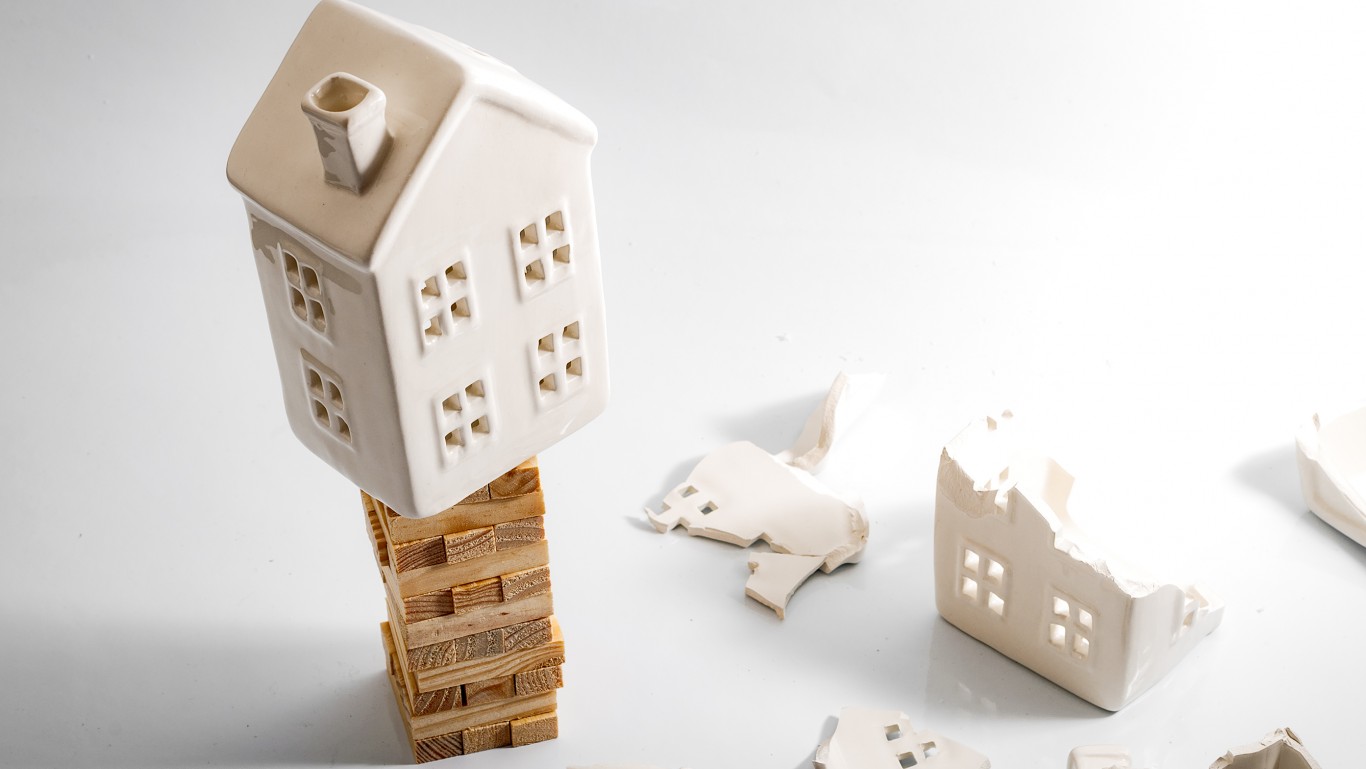
“Right now it’s a house of cards. Literally,” Jade Warshaw told a caller on The Ramsey Show. She co-hosted the episode with George Kamel. The caller, John, is a 30-year-old general contractor in Milwaukee. He has a six-month-old son, and his balance sheet looks rich while his checking account runs on empty.
Here are his numbers. He pays $2,000 a month for an apartment. His wife takes home $60,000 a year after taxes. A $2,100 rental mortgage is covered by $3,100 in rent.
He also owes his father “about 250, probably 300 after the rest of the renovation” on the house he plans to move into when his February lease ends. “We bought this house for four. It’s going to be worth eight,” he said. Meanwhile he works “14, 16 hour days and then every two years I get paid.”
Why Warshaw Is Right: Equity Can’t Pay a Bill
The hosts got this one right. John’s problem is timing, and he named it himself: “I’ll make whatever equity this year, but I can’t make a monthly payment.”
Equity is just an estimate until a buyer or an appraiser signs off on it. Debt payments are due every month no matter what. Start with the rental. The gap between rent and the mortgage is $1,000 a month, and that is before repairs, turnover or property tax increases. If the unit sits empty for two months, he owes $4,200 with no rent coming in, and that $1,000 monthly buffer is gone.
The flip is fragile too. Say agent and closing costs run 6%, which is a common example. On an $800,000 sale, that takes $48,000 off the top.
If the price comes in just 10% short, another $80,000 disappears. The debt to his father remains the same whatever the house sells for.
A Frozen Resale Market Is the Hidden Risk
Everything in John’s plan depends on a buyer at the top of the market. Right now, that buyer is hard to find. Existing home sales ran at a 3.99 million annual rate in September, down 2% from a year earlier. August’s 3.93 million was the lowest reading of the past year. Bloomberg reported that pending home sales fell to a record low in September.
Prices aren’t rising fast enough to bail anyone out. The Case-Shiller national index is up only 2% year over year. The 10-year Treasury yield, which mortgage rates follow, is 5.1%, up from 4.0% in February. An $800,000 house needs a buyer who can handle an $800,000 mortgage at those rates.
One Variable Decides This: Can the Equity Become Cash on Schedule?
Warshaw’s plan turns his equity into cash he can count on. Sell the rental when the tenants leave. Use that equity to pay back his father. Put the rest on a 15-year fixed mortgage, take regular contracting work, and pay cash for the next flip.
John put the rental’s equity at “probably a buck 50, maybe 120 after taxes.” That would leave somewhere between $100,000 and $180,000 still owed.
Assume a 6.5% rate for illustration. The 15-year payment would land between about $871 and $1,568 a month.
Either payment is lower than the $2,000 rent he pays today. Both fit inside his wife’s $5,000 monthly take-home pay. Under his current plan, the bills only get covered if the house sells quickly and at full price.
Kamel put it bluntly: “The risk is all on you and you don’t have income until the project’s done and things sold and it all works out perfectly.”
Steps to Take Before Signing a Leveraged Flip
- Cover the bills without the flip. Add up every fixed monthly payment. Then check whether a regular paycheck, not a future sale, can cover all of it.
- Stress-test the sale price. Cut your target price by 10%, then subtract 6% for selling costs. If what’s left can’t clear every loan, the deal is too thin.
- Plan for a vacancy. Multiply your rental mortgage by two months. Keep that much cash on hand before considering any rent as profit.
- Put family loans in writing. Set a repayment date and a rate. An open-ended loan from a parent is still debt that needs a plan.
Warshaw also pointed out that Ramsey’s company “was built on Dave doing that the wrong way.” Two days earlier, Yahoo Finance had run a headline saying Ramsey is “probably a billionaire” because his real estate has no debt. “But you couldn’t pay me enough to do it,” Kamel said, and Warshaw agreed.
A flip only works if the bills can be paid every month while you wait for the sale.
Contact [email protected] for any questions or corrections.
Jake has been been working in financial media for almost 15 years. He focuses on all things personal finance for 24/7 Wall St. with high hopes to educate and entertain. Most recently, Jake spent 12 years working various roles at The Motley Fool. He started copy editing fool.com content, worked on premium and marketing campaigns, and helped launch The Ascent, a personal finance brand.
His work has been featured on platforms like MSN, Yahoo Finance, USA Today, and more. He's written about credit cards, social security, ETFs, savings accounts, and just about anything else you can imagine when thinking about money. Jake love to cook, play golf, and tell people he's never had a cavity. (It's true!)