Big RSU Vest Coming? How Maxing Your 401(k) and HSA Can Shrink the Tax Bill
A large RSU vest lands in your brokerage account, then the pay stub arrives and rewrites the celebration. Two accounts buried in your benefits portal could quietly pull thousands of dollars back from the IRS before the year closes.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Picture a senior engineer at a public tech company, 58 years old, opening the pay stub for the period when a large block of restricted stock units finally vested. The shares look good in the brokerage account. The stub tells a different story. The vest shows up as wages on top of salary, and federal income tax, Social Security and Medicare come out of it.
No legal move stops the tax on the vest itself. A pre-tax 401(k) and a health savings account can still lower taxable wages down somewhere else on the return. With the final paychecks of 2026 approaching, the window to use them is closing.
Why RSU Income Gets Taxed Like a Paycheck
IRS Publication 525 says that when property received for services becomes substantially vested, you must include its FMV, minus any amount you paid for it, in your income for that year. Publication 17 (TY2025) applies the same rule.
NOTE: Section 83(b) election sometimes is unavailable for RSUs, but if the award actually transfers restricted shares before they vest, rather than merely promising future shares, the arrangement may instead be restricted stock, for which a timely election may be available. However, if this is a true restricted stock unit (RSU) which is a promise to deliver stock later, not a stock transferred to the employee at grant, then Section 83(b) election does not apply to RSUs.
Pre-Tax 401(k) Deferrals Shrink Your Taxable Wages
Traditional elective deferrals stay out of the “Wages, tips, other compensation” box of Form W-2, though they are included in wages for social security, Medicare, and FUTA taxes. For 2026, the deferral limit is $24,500. Workers 50 and older can add an $8,000 catch-up, and SECURE 2.0 raises that to $11,250 for participants who turn 60, 61, 62, or 63 during the year.
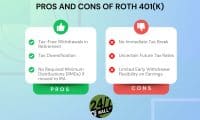
Here’s the catch for RSU earners. Starting in 2026, employees 50 and older who earned more than $150,000 in 2025 must make their catch-up contributions to a Roth 401(k), as The New York Times reported. Roth contributions are included in your wages in box 1 of Form W-2, so they lower nothing today. For most people with big vests, the pre-tax option tops out at the base limit.
Many plans also won’t let you defer directly from RSU income. The practical move is to raise your deferral percentage on the regular paychecks left in the year. Check how your plan sets compensation and how many pay cycles a change takes to kick in.
HSA Contributions Stack a Second Deduction
You can fund an HSA only while you’re covered by a high-deductible health plan. For 2026, Publication 969 caps contributions at $4,400 for self-only coverage and $8,750 for family coverage. Owners 55 and older get an additional contribution of $1,000. Once you enroll in Medicare, your contribution limit is zero.
The path matters. Salary reductions run through a cafeteria plan are treated as employer contributions, and those aren’t included in your income. Money you deposit yourself gets claimed as a deduction on Form 8889.
The newest Publication 969 allowed 2025 contributions through April 15, 2026. The same rule points to an April 2027 deadline for 2026 money. Confirm the exact date once the 2026 edition is out.
What Maxing Both Accounts Is Worth in 2026
Go back to the 58-year-old engineer and assume a joint return, family HDHP coverage and 2025 Social Security wages above the Roth catch-up line. The vest pushes taxable income past the 32% line, which starts above $403,550 for married couples in 2026.
| Item | Amount |
|---|---|
| Pre-tax 401(k) deferral | $24,500 |
| Family HSA plus age-55 add-on | $8,750 + $1,000 |
| Total pre-tax room | $34,250 |
| Federal tax saved at 32% | $10,960 |
| Federal tax saved at 35% | $11,987.50 |
Only dollars you haven’t already contributed add new savings. State treatment of HSA contributions varies, so check your state’s rules.
Workers 63 and older get a bonus, since Medicare sets premiums from income two years earlier. In 2026, surcharges start above $109,000 of MAGI for single filers and $218,000 for joint filers, and Part B tops out at $689.90 a month.
Only a Few Paychecks Left to Act
- Count the paychecks left in 2026 and spread your remaining 401(k) room across them.
- Submit the new deferral election now, before your plan’s cutoff.
- Choose your HSA path: payroll if your employer allows mid-year changes, or a direct deposit before the filing deadline.
Withholding Gap These Moves Leave Open
Publication 505 (2026) says employers can withhold on supplemental wages at a 22% flat rate under certain circumstances. If the vest lands in the 35% bracket, about 13 cents of every vested dollar goes unwithheld. Some larger payments fall under a 37% mandatory flat rate.
Neither account fixes that shortfall. Close it with extra withholding on a new Form W-4 or an estimated payment on Form 1040-ES.
Who Gains Most Before Year-End
Employees the vest has already pushed into the 32% or 35% bracket who still have unused 401(k) and HSA room come out ahead. Each pre-tax dollar comes off income taxed at the top of their rate. Before your final paychecks, log into your benefits portal and raise your deferral percentage, then run the withholding numbers with a CPA.
Contact [email protected] for any questions or corrections.
Vilma Rios is a tax professional and tax content contributor with more than 15 years of experience in tax and accounting. She specializes in federal tax research, tax education, and translating complex tax rules into clear, practical information for individuals, families, and small-business owners.
Vilma is a Content Tax Contributor II with the National Association of Tax Professionals (NATP), where she contributes to tax education and professional content. She has also presented tax information through webinars, including Spanish-language tax education, and has appeared on Telemundo 47 discussing tax topics and helping viewers understand important tax-filing requirements.
Her experience also includes tax and accounting work, tax research, IRS-related matters, and public tax education. While in college, Vilma volunteered in an IRS-sponsored tax assistance program and was recognized for her community service by local and state officials.
Known as “Your Tax Geek,” Vilma is passionate about making taxes easier to understand and helping people navigate an increasingly complex tax system.