At 25, She’ll Move to South Carolina on $15,000 a Year. Her Medicaid Coverage Won’t Follow Her, and the Same Paycheck Could Leave Her Uninsured
Moving from California to South Carolina on a $15,000 salary sounds like a smart financial reset, but one coverage detail most movers never check can turn a fresh start into a medical bill crisis before the boxes are unpacked.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
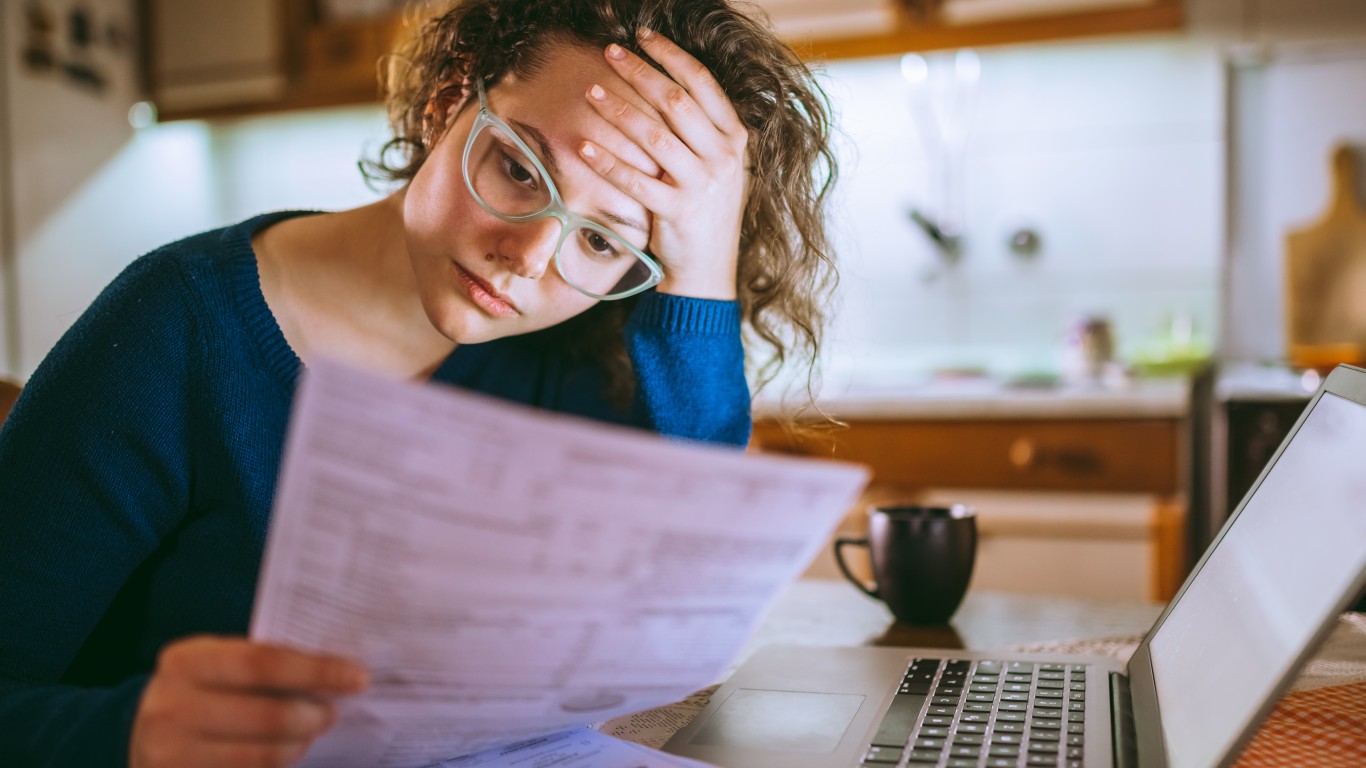
Picture a 25-year-old with no kids, no qualifying disability, a part-time retail job and $15,000 a year in income. She’s enrolled in Medi-Cal, California’s Medicaid program, and she packs for South Carolina assuming her coverage comes along because her paycheck stays the same. Once she lands, she finds out South Carolina has no full Medicaid category that fits her.
She’s got plenty of company on the road. A LendingTree (NASDAQ:TREE) analysis of Census Bureau data found South Carolina posted the largest net gain of Gen Z adults in 2024, at 22,843. California lost a net 58,109 after 186,827 left and 128,718 arrived.
Medicaid Eligibility Resets at the State Line
Medicaid is federally supported, but each state runs its own program and sets its own eligibility categories. Coverage depends on where you live. When she gives up her California residence, her Medi-Cal ends, and South Carolina reviews her from scratch under its own rules.
That means Medicaid can change even when her income does not. California and South Carolina use different eligibility pathways, so the same $15,000 paycheck can qualify her for full coverage in one state and leave her without it in the other.
California expanded Medicaid under the Affordable Care Act. Adults 19 to 64 qualify with income up to 138% of the federal poverty level. For a single person, the 2026 poverty guideline is $15,960, so her $15,000 income falls below the poverty line and well inside Medi-Cal’s limit.
South Carolina is one of 10 states that has not expanded Medicaid. Its full-coverage categories focus on children, parents and caretakers, pregnancy, age and disability. A childless adult without a qualifying disability generally cannot qualify solely because her income is low.
What she can get is narrow. South Carolina’s Family Planning benefit covers men and women with family income at or below 194% of the poverty level. It’s a limited benefit, though, and it does not replace full Medicaid coverage for unrelated prescriptions or routine medical care.
How $15,000 Lands Her in the Coverage Gap
Marketplace premium tax credits generally start at 100% of the federal poverty guideline. Expansion states cover many adults below that floor through Medicaid. In South Carolina, her $15,000 income falls below the subsidy threshold and she has no full Medicaid category that fits her.
Policy analysts call this the coverage gap. A Center on Budget and Policy Priorities estimate based on 2022 data put 83,000 South Carolinians in that gap, including 40% ages 19 to 34. A raise that brings her projected annual income to at least $15,960 could make her eligible for subsidized marketplace coverage.
The practical gap hits fast. Her Medi-Cal managed care plan and pharmacy network stay in California. A refill due in her second week, a specialist appointment she already booked and a new South Carolina doctor who doesn’t take her California card can all pile up before she has any coverage.
The move can still lower everyday costs. Federal data puts South Carolina’s 2024 regional price parity at 93.749, compared with 110.72 in California. That advantage looks different, though, if the move also leaves her without comprehensive health coverage.
Which Movers Keep Coverage and Which Don’t
Plenty of low-income movers still qualify in their new state. A pregnant mover, a parent with very low income or someone with a qualifying disability may fit a South Carolina category. The new state redetermines eligibility under its own rules.
The destination matters most. A similar adult usually has a similar path in states that expanded Medicaid. Texas was the top destination for Californians moving out of state, with 82,481 people relocating there in 2022-2023. It has not expanded Medicaid. Neither have Florida or Tennessee.
Medicaid Belongs on the Moving Checklist
The families who avoid a gap check eligibility before anyone signs a lease. They find the exact category the mover would fall into in the new state, and if none fits, they price out other coverage before the truck is loaded.
Timing matters too. South Carolina’s Medicaid agency tells anyone unsure of eligibility to apply anyway or go through Healthcare.gov, which forwards Medicaid-eligible applications to the state automatically. Smart movers refill prescriptions for as long as their current plan allows, collect their medical records and line up a community health center before their last California appointment.
Parents in their 50s and 60s have one more option. A 25-year-old can often stay on a parent’s employer plan until age 26, and for this mover, that last year on the family plan could fill the gap that South Carolina’s Medicaid rules leave open.
Contact [email protected] for any questions or corrections.
Gerelyn Terzo is the author of dividend investing handbook "Dividend Investing Strategies: How to Have Your Cake & Eat It Too." A veteran financial journalist, she covers agri-finance for outlets like Global AgInvesting and the broader stock market and personal finance for 24/7 Wall Street. She began at CNBC and later helped launch Fox Business in New York. Gerelyn currently resides in Woodland Park, Colorado and dabbles in nature photography as a hobby.