He Lived in a Mobile Home With No TV, No Computer and Almost No Furniture, and Got Around Town on a Riding Mower. He Studied Financial Publications Beside a Brook. When He Died at 82, He Left $3.8 Million

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
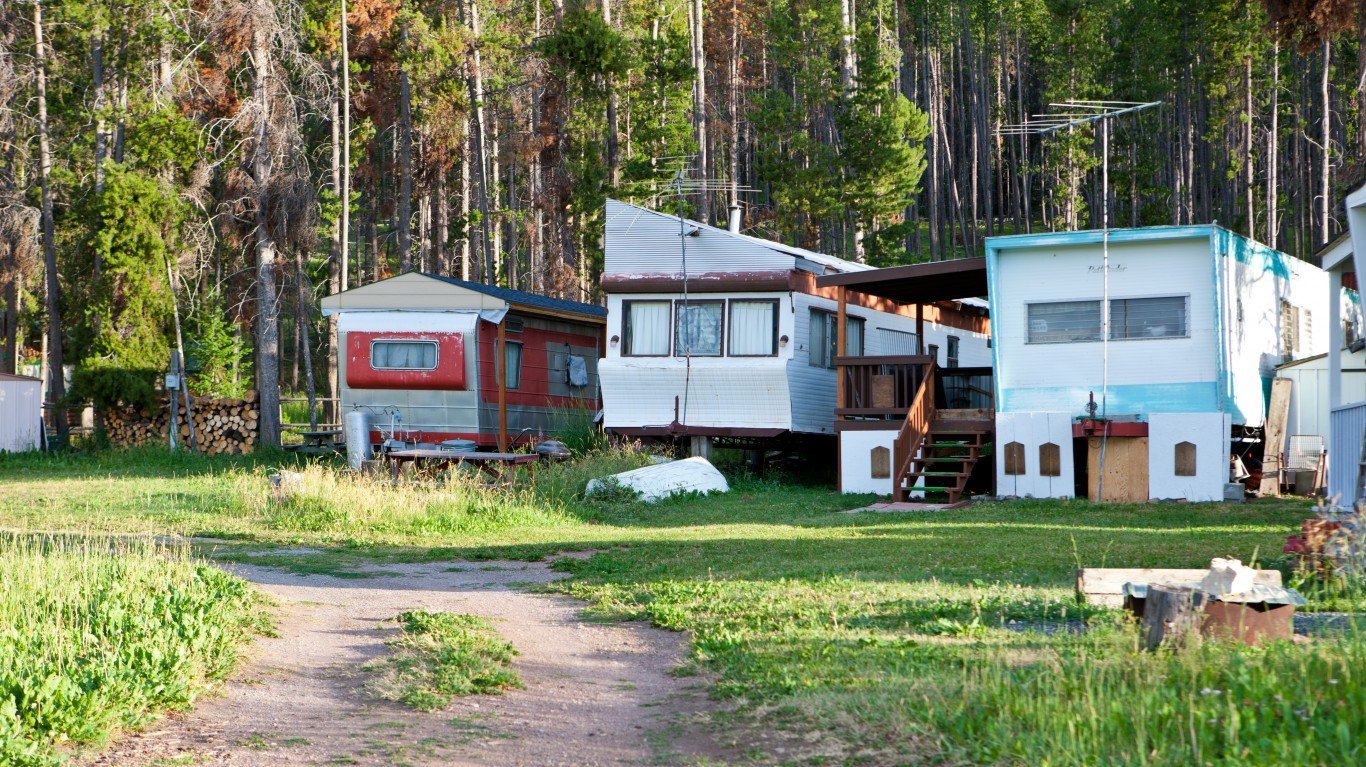
Geoffrey Holt’s mobile home in Hinsdale, New Hampshire, held almost nothing. There was no TV, no computer and hardly any furniture, and the legs of his bed had pushed through the floor. Around town he rode a riding lawn mower in threadbare clothes. He had once taught driver’s ed, then gave up driving for a bicycle and finally the mower.
He died in June 2023 at 82[1], and his will left $3.8 million to the town, according to The Associated Press, via NBC News. Most of his neighbors had no idea he had money.
An Ordinary Résumé Behind a Multimillion-Dollar Estate
Holt never earned a big salary. He worked as caretaker of the mobile home park where he lived. Before that he was a production manager at a grain mill in nearby Brattleboro, Vermont, and he once turned down a promotion that would have required relocating. He also served in the U.S. Navy and briefly taught social studies.
His sister Alison said he had dyslexia and grew up in a strict, frugal household. She said he “always told me that his main goal in life was to make sure that nobody noticed anything.”
Parts of that story will sound familiar to many retirees: a modest paycheck, low spending and decades of quiet saving. Holt’s case shows how far those habits can go.
What We Actually Know About How He Invested
The public record on his investing is thin. Holt would sit beside a creek and study financial publications. One of his first investments was a communications mutual fund. He told his best friend and estate executor, Edwin “Smokey” Smith, that his investments were doing better than he ever expected. Smith suggested he remember the town.
Nobody has released his returns, holdings or contribution schedule. Still, he clearly kept a wide, permanent gap between what he earned and what he spent, put that gap into investments, taught himself the subject, and gave compounding several decades to work. On a modest income, the size of the spending gap and the length of time matter far more than picking the perfect fund.
Where Holt’s Fortune Ranks Among American Households
According to Federal Reserve distributional data, the minimum net worth for the top 10% of households was about $2.1 million[2] in late 2022. The cutoff for the top 1% was roughly $11 million[2]. That puts Holt comfortably in the top tenth, well below the top 1% cutoff. The bottom half of households held just 2%[2] of household net worth in the second quarter of 2026.
How Hinsdale Will Turn His Savings Into Grants
His will directed the money toward education, health, recreation and culture in Hinsdale. The money sits in a trust at the New Hampshire Charitable Foundation, and grants come from the interest. The Associated Press estimated that interest at about $150,000[1] a year, so the principal stays intact and the town gets a permanent source of funding.
Real Tension: Saving Well Versus Living Well
Holt got accumulation exactly right. The open question was whether he spent too little on himself. His sister said: “I just feel so sad that he didn’t indulge himself just a little bit.” Smith saw it differently: “He seemed to have what he wanted, but he didn’t want much.”
If you’re at or near retirement with a large surplus, you face the same choice. Here are the two realistic paths.
Path One: Give It All at Death Through a Will
This was Holt’s path, and it works if leaving a legacy is your main goal. Federal estate tax won’t touch most people who take it. The basic exclusion amount is $15,000,000[3] under current law. Only 2,663[4] of the 7,195 estate tax returns filed in 2024 owed any net estate tax. This path requires a signed will. Holt’s money reached Hinsdale only because he wrote down where it should go.
Path Two: Spend and Give While You’re Alive
For most retirees with more than they will need, this is the better path. Decide on a comfortable spending level, enjoy it, and start giving while you can see the results. If you’re 70½ or older, qualified charitable distributions let you send up to $111,000 in 2026 straight from an IRA to charity without counting it as taxable income. You can still name the rest of your estate in your will.
Two Moves to Make Before Year-End
- Find out whether you’re over-saving. Compare your projected retirement assets with what you actually expect to spend. If you’re well ahead, write down a specific amount you’ll spend or give each year. Holt’s habits built the fortune. Frugality turns into regret when spending and giving are never decided.
- Write or update your will now. It’s a common mistake to assume a will can wait. If you die without one, state law decides who gets your money, and a local cause like Hinsdale gets nothing. If you want an ongoing gift, look into a community foundation trust like Holt’s, which keeps the money working long after you’re gone.
Beneficiary forms, ownership, and the order your accounts pass are what decide whether your money reaches a cause like Hinsdale or gets tangled in probate. We put the full checklist in a free guide here: Die With a Plan.
Contact [email protected] for any questions or corrections.
Jake has been been working in financial media for almost 15 years. He focuses on all things personal finance for 24/7 Wall St. with high hopes to educate and entertain. Most recently, Jake spent 12 years working various roles at The Motley Fool. He started copy editing fool.com content, worked on premium and marketing campaigns, and helped launch The Ascent, a personal finance brand.
His work has been featured on platforms like MSN, Yahoo Finance, USA Today, and more. He's written about credit cards, social security, ETFs, savings accounts, and just about anything else you can imagine when thinking about money. Jake love to cook, play golf, and tell people he's never had a cavity. (It's true!)