Her Brokerage Account Can Name a Beneficiary, Too. A Transfer-on-Death Registration Lets It Skip Probate

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
What happens to a taxable brokerage when you add a transfer-on-death registration? An IRA often has a named beneficiary on file, while a taxable brokerage account, the regular kind holding index funds and a few stocks, may have a blank beneficiary section. Most firms let owners add a beneficiary to a brokerage account through a transfer-on-death registration, and it lets the account skip probate.
Why a Blank Beneficiary Field Can Cost Months
Probate is the court process that validates a will, pays final debts, and distributes whatever’s left. It can drag on and come with court and legal fees. Retirement accounts usually avoid it because they come with beneficiary forms. A plain taxable brokerage account doesn’t automatically have a beneficiary. Without extra paperwork, it usually becomes part of the estate and waits until probate wraps up.
How a TOD Registration Moves the Account Outside Probate
Transfer on death, or TOD, is a way of registering an account so it names who gets it when the owner dies. While she’s alive, nothing changes. She can still trade, withdraw money, close the account, or switch beneficiaries whenever she wants. The beneficiaries get no access and no say. When she dies, they generally bring a death certificate to the brokerage firm, and the firm moves the assets into their names without a probate court order.
The legal basis is the Uniform TOD Security Registration Act, a model law that states can adopt. It’s available for brokerage accounts and securities across the states, and the option shows up at many major brokerages. Firms set their own policies on fees for adding it.
A Tax Break Comes Along Too
Inherited investments generally receive a stepped-up basis whether they pass through a TOD registration or probate. Under 26 U.S.C. § 1014(a)(1), that basis is generally the property’s fair market value on the date of death.
Basis is the starting figure used to calculate taxable gain. In everyday terms, the gains that built up while she was alive generally aren’t taxed to her heirs, and any later sale gets measured from the value on the day she died. People call this a stepped-up basis.
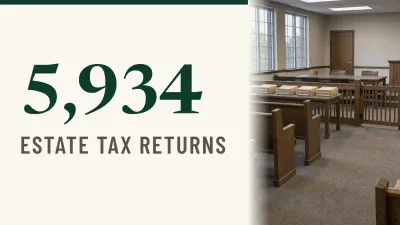
A TOD account still counts as part of her estate for estate tax purposes. Publicly traded stock showed up on 5,934 of the 7,195[1] estate tax returns filed in 2024, worth about $71.27 billion in total.
Who Can Use It and Where It Works Differently
Individual taxable accounts are the main fit. Joint accounts with right of survivorship (where the surviving co-owner automatically gets everything) go to the surviving owner first, and the TOD beneficiary inherits only after the last owner dies. When a trust owns the account, the trust document decides who gets it, so a TOD registration doesn’t apply. IRAs and 401(k)s already use their own beneficiary forms.
Steps to Set Up a TOD Registration
- Log in and check account settings, the profile page, or a beneficiaries tab. Many firms have an online form, and some ask for a signed paper or e-signed version.
- Name the primary beneficiaries and the percentage each one gets.
- Add contingent beneficiaries. They’re the backups who inherit if a primary beneficiary dies first.
- Do the same for every taxable account, because each one gets registered separately.
- Save the confirmation and update it after a marriage, divorce, birth, or death.
Mistakes That Can Undercut a TOD Registration
A will doesn’t override a TOD registration. Say the will splits everything equally among three children, but the TOD form names just one. That one child generally gets the whole account. Conflicts between the will and the beneficiary forms are generally resolved in favor of the beneficiary forms.
If the only named beneficiary dies first and nobody else is listed, the account can fall back into the estate and end up in probate after all. Naming contingent beneficiaries prevents that.
Naming a minor as a beneficiary causes a separate problem, because a child can’t legally manage an account, so a court may need to appoint someone to do it, which brings back the court involvement TOD was supposed to avoid. Some firms let owners name an adult custodian for a minor instead.
There’s also a narrow exception to the stepped-up basis. If someone gave her stock that had already gone up in value, and she died within 1 year[2] of the gift, and that stock goes back to the person who gave it (or that person’s spouse), the basis stays at her adjusted basis instead of resetting, under 26 U.S.C. § 1014(e). IRS Publication 550 describes the same rule.
Beneficiary Designations Beyond Brokerage Accounts
Beneficiary designations apply across several account types, including retirement accounts, taxable brokerage accounts, and bank accounts. 24/7 Wall St. has also covered beneficiary designations on retirement accounts and payable-on-death bank accounts, which work the same way for cash in checking and savings.
Contact [email protected] for any questions or corrections.
David Beren has been a Flywheel Publishing contributor since 2022. Writing for 24/7 Wall St. since 2023, David loves to write about topics of all shapes and sizes. As a technology expert, David focuses heavily on consumer electronics brands, automobiles, and general technology. He has previously written for LifeWire, formerly About.com. As a part-time freelance writer, David’s “day job” has been working on and leading social media for multiple Fortune 100 brands. David loves the flexibility of this field and its ability to reach customers exactly where they like to spend their time. Additionally, David previously published his own blog, TmoNews.com, which reached 3 million readers in its first year. In addition to freelance and social media work, David loves to spend time with his family and children and relive the glory days of video game consoles by playing any retro game console he can get his hands on.