At 68 With $1 Million, He’ll Hand Each Grandkid a Check Every Christmas. Giving Too Much Means Filing a Form, Not Paying a Tax

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
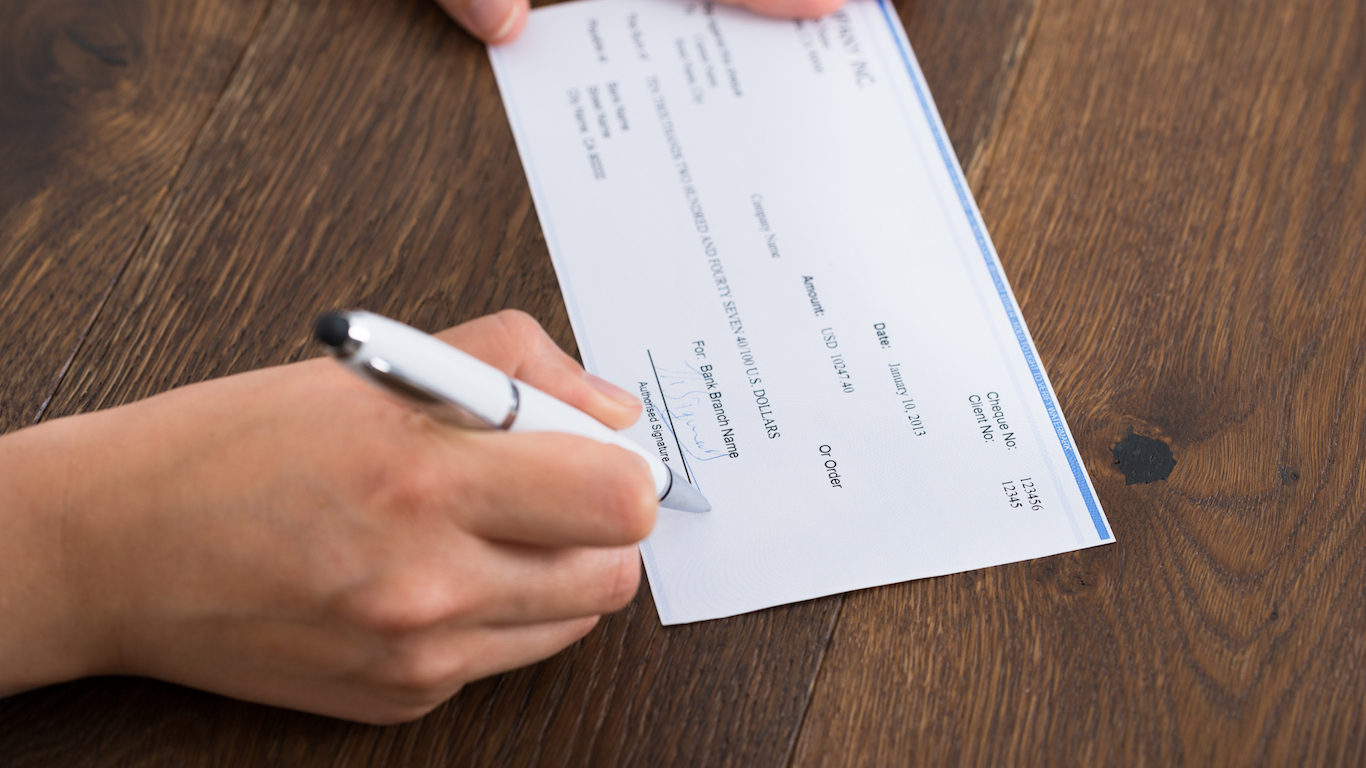
He’s 68 and has about $1 million saved. Every December, he lines up envelopes on the kitchen counter, one for each grandkid. He wants to see their faces when they open them. Giving while he’s still here to watch it land is the whole point. And every year the same worry creeps in: if he puts too much in there, will he get in trouble with the IRS?
If you’ve held back on gifts because of taxes, you’re in good company as grandparents ask this all the time, and the real answer is a lot friendlier than the worry.
One Number Covers Most Christmas Envelopes
For tax year 2026, the annual gift exclusion remains at $19,000 per recipient. That limit applies to each person separately, so every grandchild gets their own $19,000 lane. If each check stays at or under that amount, he has nothing to file and nothing to report.
The grandkids are in the clear too. Federal law says gross income “does not include the value of property acquired by gift”[1] (26 U.S.C. § 102(a)). They owe no income tax and don’t have to report the money on a return.
Giving Too Much Costs a Form and a Sliver of Exemption
The biggest problem here is that fear of a tax bill keeps people from giving, when going over the limit usually just means filing a form. Anyone who gives one person more than the annual exclusion in a calendar year has to file a gift tax return, Form 709[2]. The amount over the limit then comes off his lifetime exemption. For 2026, the basic exclusion amount that covers both lifetime gifts and your estate is $15,000,000.
With $1 million to his name, he could give away every dollar and never get close to that line. If he’s too generous one Christmas, the worst that happens is an extra form next spring.
IRS estate data shows the same thing on a bigger scale. Of 7,195[3] estate tax returns filed in 2024, only 2,663 reported any net estate tax. Filing a return and owing tax are two separate things.
A Married Couple Gets Twice the Room
The law allows a married couple to treat a gift from one spouse as made one-half by him and one-half by his spouse[4], as long as both spouses consent (26 U.S.C. § 2513(a)). That’s called gift splitting, and it allows the couple to give each grandchild up to $38,000 a year without using either lifetime exemption. The consent goes on Form 709, so if they split gifts, they should expect to file the form even though they owe nothing.
Tuition and Medical Bills Don’t Count Against the Limit
Paying tuition straight to a school or medical bills straight to a provider shall not be treated as a transfer of property by gift[5] under 26 U.S.C. § 2503(e). These payments sit on top of the $19,000 envelope and have no cap of their own.
The payment has to go directly to the school or provider. If he hands his grandson money to cover tuition, that counts against the annual exclusion. Additionally, 529 plan contributions follow the regular rules: the law treats them as completed gifts and specifically shall not treat them as a qualified transfer under section 2503(e)[6].
Why Generation-Skipping Tax Doesn’t Apply to Him
A gift to a grandchild skips a generation, and the tax code has a separate generation-skipping transfer tax for that. But a direct gift that’s already covered by the annual exclusion, or a direct tuition or medical payment, gets an inclusion ratio of zero (26 U.S.C. § 2642(c)). In plain terms, that tax is zero. Gifts made through a trust have stricter rules. If he wants to use a trust, that’s when hiring a lawyer makes sense.
Where His Generosity Really Hits a Limit
At his age with $1 million, the wiser move is to keep each check at or under $19,000 and send any bigger help straight to the school or the doctor. That way there’s no paperwork, no tracking, and no gray areas.
The real limit on his giving is his own retirement. That $1 million may have to last decades, and running out of money in his late 80s would cost the family far more than any tax. The same goes for the paperwork around what’s left: beneficiary forms, ownership, and a current will decide whether the balance lands with the grandkids or with lawyers (we put the whole checklist in a free guide here).
Your Checklist for Gifting Without Surprises
- Track each person by calendar year. The 2026 limit is $19,000 per grandchild. Add up birthday money and the Christmas check together.
- Decide on gift splitting before you write big checks. If you’re married and giving more than $19,000 to anyone, both spouses need to consent, which means filing Form 709.
- Pay tuition and medical bills directly. Send the money to the school or provider, never to the grandchild, so it stays outside the annual exclusion.
- Give directly instead of through a trust. Outright gifts within the annual exclusion avoid generation-skipping tax with no extra planning.
- Ask the grandkids to deposit December checks before New Year’s. That keeps the gift in the year you intended, so it doesn’t count against the 2027 limit of $20,000.
Fill the envelopes. If one goes over the limit, file the form and move on. Avoid giving away money your own retirement still needs.
Contact [email protected] for any questions or corrections.
David Beren has been a Flywheel Publishing contributor since 2022. Writing for 24/7 Wall St. since 2023, David loves to write about topics of all shapes and sizes. As a technology expert, David focuses heavily on consumer electronics brands, automobiles, and general technology. He has previously written for LifeWire, formerly About.com. As a part-time freelance writer, David’s “day job” has been working on and leading social media for multiple Fortune 100 brands. David loves the flexibility of this field and its ability to reach customers exactly where they like to spend their time. Additionally, David previously published his own blog, TmoNews.com, which reached 3 million readers in its first year. In addition to freelance and social media work, David loves to spend time with his family and children and relive the glory days of video game consoles by playing any retro game console he can get his hands on.