At 73 She’ll Pull $90,000 a Year From Her Roth. Medicare’s Surcharge Reads Her Tax Return, and Because a Roth Dollar Never Appears on It, Her Premium Will Stay at the Standard Rate

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
She’s 73 and plans to pull $90,000 a year from her Roth IRA, but her friends keep warning her that a withdrawal that size will trigger Medicare’s income surcharge, and she’s half convinced they’re right.
If you’ve been told the same thing, it helps to know how Medicare IRMAA treats Roth IRA withdrawals. Qualified Roth withdrawals stay out of the income Medicare uses to set your premium, so the Roth money doesn’t push her into a higher bracket. That’s the benefit of paying the tax years ago, back when she made her contributions.
What Medicare Actually Reads on Her Tax Return
Social Security sets the surcharge, called the income-related monthly adjustment amount (IRMAA), from modified adjusted gross income, or MAGI. MAGI is defined as “your total adjusted gross income and tax-exempt interest income”[1]. It generally uses the federal tax return from two years before the premium year, which means 2026 premiums are based on 2024 income. A qualified Roth distribution never goes into adjusted gross income, so it never shows up in MAGI.
Where the Law Spells Out the Roth Exclusion
The exclusion sits in 26 U.S.C. § 408A(d)(1)[2]. “Any qualified distribution from a Roth IRA shall not be includible in gross income.”[2] Roth accounts inside a 401(k) or 403(b) get the same treatment under 26 U.S.C. § 402A(d)(1)[3]. The premium side comes from 42 U.S.C. § 1395r, the Part B premium statute, and Social Security applies it using the MAGI definition above.
Who Qualifies for the Surcharge-Free Withdrawal
A Roth distribution counts as qualified when it meets two tests. It has to be taken on or after age 59½[2] (other qualifying events are death, disability, or a first-home purchase capped at a $10,000 lifetime limit). It also must come after the 5-year period beginning with the first tax year in which a contribution was made to a Roth IRA. She passes the age test easily at 73, so the five-year clock is the one to check.
A traditional IRA withdrawal gets the reverse treatment. Taking the same $90,000 from a traditional IRA would generally add the taxable portion to adjusted gross income and Medicare MAGI. Under SECURE 2.0, a traditional IRA owner’s first required minimum distribution is due for the year she turns 73. Roth IRAs have no such requirement. “The RMD rules do not apply to Roth IRAs or Designated Roth accounts while the owner is alive.” When she takes Roth money, it is completely up to her.
How to Check Your 2026 Bracket
- Find the first tax year you contributed to any Roth IRA, then confirm five tax years have passed since that year began.
- Confirm you’re 59½ or older on the date of the withdrawal.
- Total everything else that lands in MAGI: pensions, traditional IRA withdrawals and RMDs, wages, capital gains, the taxable part of Social Security, and tax-exempt interest.
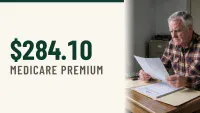
- Compare that total to the 2026 brackets. The base Part B premium is $202.90 a month for single taxpayers with MAGI of $109,000 or less and joint filers with MAGI of $218,000 or less. Surcharges start at $284.10, and the top tier is $689.90 for single taxpayers with MAGI of $500,000 or more and joint taxpayers with MAGI of $750,000 or more. Part D adds its own surcharge, ranging from $14.50 to $91.00 a month.
- Keep the two-year lag in mind. Whatever lands on this year’s return sets the premium two years out.
Traps That Can Still Raise Her Premium
Her other income still counts in full. If her pension, Social Security, and other taxable income already put her MAGI above $109,000 as a single filer, she’ll owe a surcharge no matter what the Roth does. Each bracket is a cliff. Going one dollar past $109,000 raises her monthly Part B premium from $202.90 to $284.10 (we detailed the surcharges and the other premium traps that catch retired people in a free Medicare guide here).
Roth conversions cause the most trouble. When you convert traditional IRA money to a Roth, the converted amount must be included in income for that year, which can lift MAGI and trigger IRMAA two years later. A withdrawal made before the five-year clock runs out doesn’t qualify, and part of it may become taxable income. Municipal bond interest also counts toward MAGI, even though it’s tax-exempt. If your income falls after a life-changing event such as retirement or the loss of a spouse, you can file Form SSA-44 and ask Social Security to adjust the surcharge.
Her friends would be right if the money were coming from a traditional IRA or a conversion, but a qualified Roth withdrawal never shows up on the return Medicare reads, so her premium comes down to her other income.
Contact [email protected] for any questions or corrections.
David Beren has been a Flywheel Publishing contributor since 2022. Writing for 24/7 Wall St. since 2023, David loves to write about topics of all shapes and sizes. As a technology expert, David focuses heavily on consumer electronics brands, automobiles, and general technology. He has previously written for LifeWire, formerly About.com. As a part-time freelance writer, David’s “day job” has been working on and leading social media for multiple Fortune 100 brands. David loves the flexibility of this field and its ability to reach customers exactly where they like to spend their time. Additionally, David previously published his own blog, TmoNews.com, which reached 3 million readers in its first year. In addition to freelance and social media work, David loves to spend time with his family and children and relive the glory days of video game consoles by playing any retro game console he can get his hands on.