He Worked as a Carpenter at the Same Iowa Business for 67 Years and Owned Two Pairs of Jeans, One for Work and One for Church. When He Died in 2005, He Left Nearly $3 Million to Send Strangers to College

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
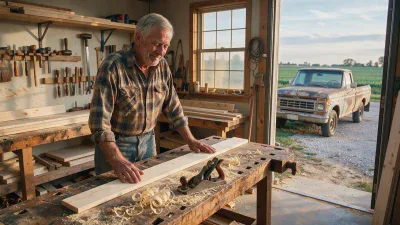
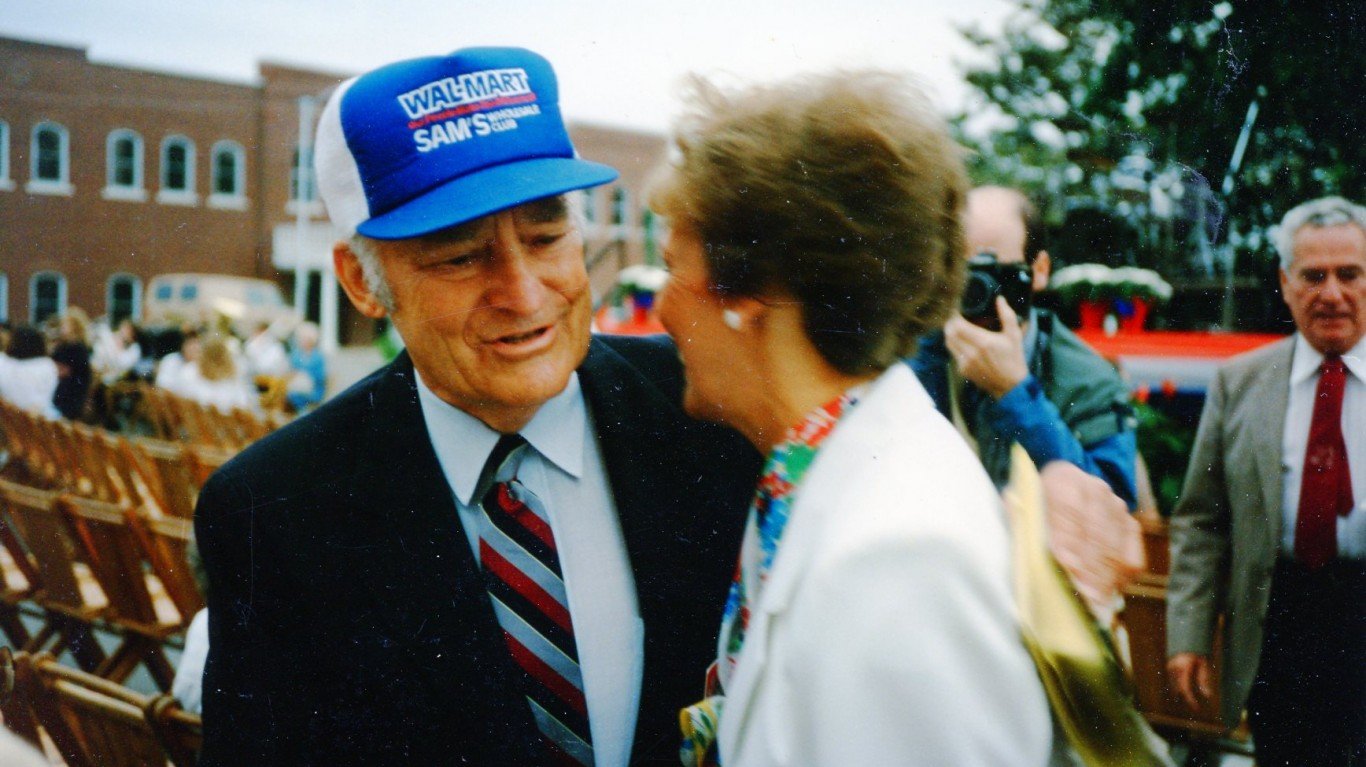
Dale Schroeder worked as a carpenter at the same Iowa business for 67 years[1], according to ABC7 New York. He grew up poor, never went to college and never married.. When he died in 2005, he had no descendants and owned a pair of work jeans, a pair of church jeans and a rusty Chevrolet truck.
ABC7 New York reported that he had also accumulated almost $3 million[1] through carpentry work and frugal living. Much of it went into a scholarship fund for small-town Iowa kids who could not otherwise afford college. ABC7 New York said the fund put 33[1] people through school free of charge.
Steve Nielsen was a friend of his. He described him this way: “He was that kind of a blue-collar, lunch pail kind of a guy. Went to work every day, worked really hard, was frugal like a lot of Iowans.”
Many retirees will see themselves in part of this story, as they live modestly, the balance keeps growing, and they have no written plan for where it ends up. Schroeder got that last part right, and it is the part most people skip.
A Carpenter Who Outsaved Most of America
Federal Reserve data put the entry point for the 90th to 99th percentile of household wealth at about $2.1 million[2] in nominal dollars. This was as of late 2022. A tradesman’s estate cleared that bar.
He did it on ordinary wages. Today, the median full-time worker earns $1,232 a week, and the average household spent $81,905 in 2025. Schroeder’s advantage was the gap between what he earned and what he spent, kept open for decades, and while two pairs of jeans is an extreme example, the math behind it applies at any income.
Who Gets the Money Matters More Than the Tax Bill
The central tension for people with seven-figure balances is that fear of running short keeps them saving, yet many will die with large amounts they never directed anywhere. In a 2025 Northwestern Mutual survey, 51% of adults said they were likely to outlive their savings.
Federal estate tax is a minor factor at this level. The basic exclusion amount is $15,000,000[3] under 26 U.S.C. § 2010(c)(3)(A). The IRS recorded just 7,195[4] estate tax returns filed nationwide in 2024. A $3 million estate owes no federal estate tax.
What decides the outcome is paperwork. Without a will, state law picks your heirs. For a single person without children, that can mean distant relatives you barely know.
Two Ways to Give Like Dale
Path 1: Leave It in Your Will and Beneficiary Forms
This was Schroeder’s route. You keep full control and keep the money available for long-term care until the end.
Match each asset to the right recipient. Heirs pay income tax on money they take from an inherited traditional IRA or 401(k). A qualifying charity pays none. Name the charity as beneficiary on pre-tax accounts and leave Roth or taxable accounts to people. Doing the reverse hands the IRS a share it never needed to collect.
Path 2: Start Giving at 70½
Once you reach age 70½[5], you can use a qualified charitable distribution (QCD). It lets you send IRA money directly to a charity without counting it as taxable income, under 26 U.S.C. § 408(d)(8). One catch: donor-advised funds are excluded[5]. The benefit is that you see the impact while you are alive, something Schroeder never did. The tradeoff is that money you give away is no longer there if your health costs spike.
If you have charitable goals and a large IRA, combining the two works best. Make modest QCDs each year after 70½ and name the charity as beneficiary on what is left. Holding everything until death and leaving cash to charity while IRAs go to family is the clearly worse setup.
What to Do Before Year-End
- Measure your spending gap. Compare last year’s spending with your income. Schroeder’s wealth came from a gap he kept open for decades, and regular saving matters more than finding the perfect investment.
- Pull every beneficiary form. IRA, 401(k) and life insurance designations override your will. A form you filled out decades ago can send money somewhere you never intended. Fix it now, for free, while you can still sign it. (We put the full beneficiary and titling checklist in a free estate guide here.)
The recipients now call themselves “Dale’s Kids.” One of them, Kira Conard, had the grades but not the money. She was about to tell friends at her graduation party she would skip college when the call came. “I broke down into tears immediately,” she said. She graduated debt-free.
The only condition was to pay it forward. Nielsen put it simply: “You can’t pay it back, because Dale’s gone, but you can remember him, and you can emulate him.”
Contact [email protected] for any questions or corrections.
Jake has been been working in financial media for almost 15 years. He focuses on all things personal finance for 24/7 Wall St. with high hopes to educate and entertain. Most recently, Jake spent 12 years working various roles at The Motley Fool. He started copy editing fool.com content, worked on premium and marketing campaigns, and helped launch The Ascent, a personal finance brand.
His work has been featured on platforms like MSN, Yahoo Finance, USA Today, and more. He's written about credit cards, social security, ETFs, savings accounts, and just about anything else you can imagine when thinking about money. Jake love to cook, play golf, and tell people he's never had a cavity. (It's true!)