‘Double Stacking the DAF at This Level Could Save You Five Grand Over Two Years’: Wes Moss to Colorado Couple Earning $208,000

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
A Colorado caller named Scott brought Wes Moss a problem that plenty of high earners share. His household AGI last year was $208,000. He owed about $4,000 when he filed. The couple’s charitable giving also lands just below the standard deduction, so itemizing gets them nothing.
Moss is chief investment strategist at Capital Investment Advisors. He told Scott, during the November 17, 2026 Ask an Advisor episode of Clark Howard’s podcast, that bunching his giving through a donor-advised fund (DAF) “could save you five grand over two years, 2,500 bucks in federal taxes.” Moss assumed the couple gives about $30,000 a year. If they take the standard deduction every year, that giving does almost nothing to lower their federal tax bill.
A Windfall Tool Moves Into a Salaried Household
Four weeks earlier, Moss described a DAF as something that “is great when you have a big income event, sold a business, big capital gains.” Scott is a W-2 earner with a regular paycheck. Moss has now expanded his own rule, and the numbers support him.
2026 Tax Math Backs Up Moss’s $5,000 Figure
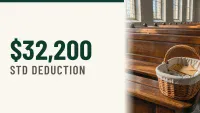
Moss rounded the standard deduction to about $34,000. The IRS figure for married couples filing jointly in 2026 is $32,200. Two new federal rules also affect the math. Itemizers can deduct charitable gifts only above a floor equal to 0.5%[1] of their contribution base. Non-itemizers, meanwhile, can deduct up to $2,000[1] of cash gifts on a joint return, but gifts to a donor-advised fund don’t count toward that deduction.
Here’s the comparison, assuming the $30,000 of giving is the couple’s only itemizable expense.
Without a DAF: Each year they take the $32,200 standard deduction plus the $2,000 cash-gift deduction, for $68,400 over two years. That leaves taxable income near $173,800.
That sits in the 22% bracket, which runs from $100,800 up to $211,400 for joint filers.
With a DAF: In year one they put $60,000 into the fund. The $1,040 floor leaves $58,960 deductible. In year two they take the standard deduction and make their usual gifts out of the fund. Over the two years they deduct $22,760 more than they would without the fund.
At 22%, that extra deduction saves about $5,007. Moss’s on-air estimate holds up even after adjusting his rounded inputs. Taxable income in the bunching year falls to about $149,040, still within the 22% bracket, so every deducted dollar is worth the same 22 cents.
Moss, who takes listener questions at wesmoss.com/ask, lays out his retirement framework in The Retire Sooner Method.
Your Distance From $32,200 Sets the Payoff
The return depends on how close your annual giving is to the standard deduction. At $30,000, it’s close. Suppose the couple gave $20,000 a year instead. Putting $40,000 into the fund adds only $2,760 of extra deductions over two years.
That’s worth about $607. Most of the bundled money simply replaces the standard deduction they would have taken anyway.
State taxes can cut into the savings too. Moss said on air that he doesn’t know how Colorado handles this. Colorado lets filers who take the federal standard deduction subtract a portion of their charitable giving on the state return. Anyone who itemizes federally loses that subtraction. Have a CPA calculate that cost for the bunching year, as Moss himself recommended.
Moss also mentioned switching 401(k) contributions from Roth to traditional in the bunching year. In this example both years fall in the 22% bracket. A traditional contribution saves 22 cents per dollar whichever year you make it. The better question is whether you expect a lower tax rate in retirement.
Steps to Take Before December 31
- Total your itemizable expenses. Add up last year’s charitable gifts, state and local taxes and mortgage interest. If the total falls within a few thousand dollars of $32,200, bunching is worth pricing out.
- Find your marginal bracket. Your marginal bracket is the tax rate on your last dollar of income. Subtract your deductions from AGI and compare the result to the IRS bracket table. Multiply your extra deductions by that rate to estimate the savings.
- Get the paperwork right. A DAF gift isn’t deductible without a contemporaneous written acknowledgment from the fund’s sponsor confirming it has legal control of the assets. The contribution must also clear the fund before year-end to count for this tax year.
- Fix the April bill separately. Moss told Scott that owing money “has nothing to do with your tax rate.” Owing only means too little was withheld during the year. Updating the couple’s W-4 forms takes care of the $4,000 bill. A DAF doesn’t.
Contact [email protected] for any questions or corrections.
Jake has been been working in financial media for almost 15 years. He focuses on all things personal finance for 24/7 Wall St. with high hopes to educate and entertain. Most recently, Jake spent 12 years working various roles at The Motley Fool. He started copy editing fool.com content, worked on premium and marketing campaigns, and helped launch The Ascent, a personal finance brand.
His work has been featured on platforms like MSN, Yahoo Finance, USA Today, and more. He's written about credit cards, social security, ETFs, savings accounts, and just about anything else you can imagine when thinking about money. Jake love to cook, play golf, and tell people he's never had a cavity. (It's true!)