Financial Advisors Debunk the Roth vs. Traditional 401(k) Myth. Here’s the Real Rule for Your Age
A viral money expert recently told his audience that traditional 401(k)s beat Roth accounts every time, claiming the Roth IRA was a George W. Bush creation designed to pull forward tax revenue during an economic downturn. His verdict: “if you…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
A viral money expert recently told his audience that traditional 401(k)s beat Roth accounts every time, claiming the Roth IRA was a George W. Bush creation designed to pull forward tax revenue during an economic downturn. His verdict: “if you do an apples-to-apples comparison of the true cost, you’re going to do better in a traditional 401(k).” Act on that claim without checking the math against your own tax bracket, and you could leave real money on the table for the rest of your working life.
This debate drew attention because the historical claim is flatly wrong and the financial claim is dangerously incomplete. Brian Preston of The Money Guy Show dissected both errors with unusual clarity, and his framing is what every saver should anchor to before selecting a contribution type on their 401(k) portal.
The History the Viral Take Got Wrong
Congress created the Roth IRA through the Taxpayer Relief Act of 1997, signed into law by President Bill Clinton on August 5, 1997. That predates George W. Bush taking office by more than three years. The account takes its name from Senator William Roth of Delaware, then chairman of the Senate Finance Committee, who championed the idea of a retirement account funded with after-tax dollars in exchange for tax-free withdrawals. What started as a modest savings vehicle with a $2,000 annual contribution cap has since grown into one of the most powerful tax-planning tools available. For 2026, the Roth IRA contribution limit stands at $7,500 for savers under age 50, and $8,600 for those 50 or older, the first year the catch-up amount has been inflation-indexed under SECURE 2.0.
There is a grain of irony in the viral advisor’s Bush attribution. The law that lifted income caps on Roth conversions was the Tax Increase Prevention and Reconciliation Act of 2005, signed by President Bush on May 17, 2006. That legislation eliminated the income limitation on converting a traditional IRA into a Roth IRA, with the change taking effect in 2010. The bill expanded access to Roth accounts rather than creating them, and its purpose was to raise near-term federal revenue, not to disadvantage savers.
The broader legislative timeline is worth knowing. The Roth 401(k), the workplace plan version most Americans encounter today, was authorized by the Economic Growth and Tax Relief Reconciliation Act of 2001 and became available to employers on January 1, 2006. The Pension Protection Act of 2006 then made the Roth 401(k) option permanent. More recently, the SECURE 2.0 Act of 2022 eliminated required minimum distributions from Roth 401(k) accounts, effective 2024, bringing the workplace Roth plan in line with the longstanding advantage Roth IRAs have always offered.
Strip out the bad origin story, and the actual question becomes a math problem about tax brackets.
The Real Rule: Tax Arbitrage, Not Account Type
The choice between Roth and traditional reduces to one comparison: your tax rate today versus your expected tax rate when you pull the money out. Everything else is secondary.
Preston put it plainly: “If you’re in a low tax bracket environment today, and it’s likely your income is going to increase and be higher in the future, Roth 100% makes sense.” On the viral advisor’s core error, he was equally direct: “They are not apples to apples. There absolutely is a better choice than the other depending on your unique circumstances.”
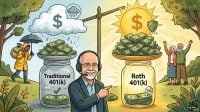
The mechanics are straightforward. A traditional 401(k) gives you a deduction at your current marginal rate and taxes every withdrawal at your future marginal rate. A Roth flips that arrangement: you pay tax now at today’s rate and owe nothing on qualified withdrawals later. If your rate today is lower than your rate in retirement, Roth wins. If today’s rate is higher, traditional wins. The math never changes. Only the inputs do.
How This Plays Out by Life Stage
Consider a 24-year-old in an entry-level role, sitting comfortably in one of the lower federal brackets. That person is almost certainly going to earn more as their career progresses. Paying tax now at today’s low rate and letting decades of compounding grow tax-free is the textbook Roth argument. Suze Orman has made this point bluntly for years: “a Roth retirement account is the best retirement account you are ever going to have, bar none. Give up the tax write offs today to have tax free access forever later on.”
Contrast that with a 52-year-old physician at peak earnings, facing a top marginal rate, who plans to retire on a portfolio drawdown that lands them in a middle bracket. The deduction available today is worth more than the one they would forgo in retirement. Traditional carries the day in that scenario.
For high earners over 50, SECURE 2.0 has already settled part of the argument by regulation. Beginning January 1, 2026, workers aged 50 and older whose 2025 FICA wages from their employer exceeded $150,000 are required to make all catch-up contributions on an after-tax Roth basis. The base 401(k) contribution limit for 2026 is $24,500 for employee salary deferrals. Workers 50 and older (excluding those aged 60 to 63) can add a regular catch-up of up to $8,000, for a combined total of $32,500. Workers aged 60, 61, 62, or 63 qualify for an enhanced catch-up of $11,250, bringing their potential annual total to $35,750. For those above the $150,000 wage threshold, every dollar of catch-up goes into the Roth bucket regardless of personal preference.
One additional detail worth tracking: even the ability to contribute directly to a Roth IRA phases out at higher incomes. For 2026, the phase-out range for single filers runs from $153,000 to $168,000 in modified adjusted gross income, per IRS Notice 2025-67. High earners above that ceiling who want Roth exposure commonly use a backdoor Roth conversion instead, the same access expansion that President Bush’s 2006 bill eventually made universal.
What to Do This Week
Stop treating this as an ideology and approach it as arithmetic. Three steps get you to the answer:
- Pull up your most recent pay stub and find your federal marginal tax bracket. Write it down.
- Estimate the bracket you expect to occupy in retirement, based on projected portfolio withdrawals plus Social Security. If you have no solid estimate, assume your income keeps climbing through your 50s and falls in retirement.
- If today’s bracket is lower than tomorrow’s, route new contributions to the Roth side. If today’s bracket is higher, route them to the traditional side. Revisit that decision every time your income crosses into a new bracket.
The Roth IRA has been available since 1998, and the Roth 401(k) has been an option in most workplace plans since 2006. That is a combined track record spanning nearly three decades. The honest answer is one rule applied to your own numbers: pay the tax in whichever year the rate is lower. When the math says Roth, use it.
Editor’s note: This article was updated to reflect the 2026 Roth IRA contribution limits of $7,500 for savers under 50 and $8,600 for those 50 and older, the first year the IRA catch-up has been inflation-indexed under SECURE 2.0. The addition of the SECURE 2.0 elimination of required minimum distributions from Roth 401(k) accounts, effective 2024, was also incorporated.
Contact [email protected] for any questions or corrections.
I've been writing about stocks and personal finance for 20+ years. I believe all great companies are tech companies in the long run, and I invest accordingly.