After 20 Years Managing a Ranch, Their Bosses Gave Them the Deed. Social Security May Count It as One Enormous Paycheck.
Two ranch managers worked 20 loyal years for aging owners who handed them the deed instead of a paycheck, and now the IRS and Social Security may treat that generous gesture as the single largest wage event of their lives.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
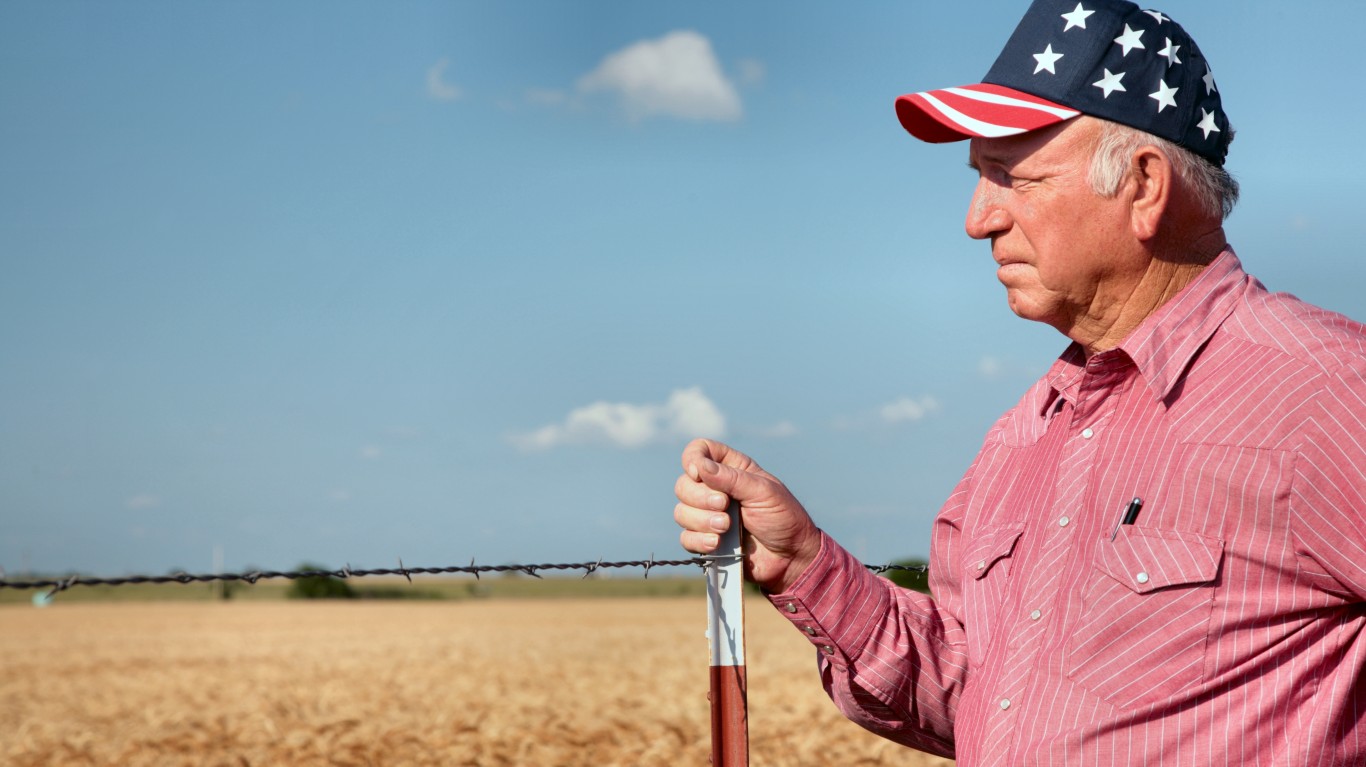
A married couple, both 64, have spent two decades living on and managing a working ranch for its aging owners. They repaired fences, helped through calving seasons, supervised crews, and kept the operation running as the owners gradually stepped back. Now the owners are ready to move on. Rather than listing the property, they transfer the deed directly to the couple. Everyone around the closing table calls it a gift, a thank-you for 20 loyal years of service.
Tax law may see something very different: 20 years of compensation arriving all at once. That distinction matters enormously because the couple claimed Social Security at 62. If the ranch transfer is treated as wages, it could stop their checks, create a substantial tax bill without producing any cash, and drive up their Medicare premiums two years down the road.
Calling It a Gift Does Not Make It One
Under Internal Revenue Code Section 102(c), transfers from an employer to an employee cannot use the ordinary gift exclusion, even when the gesture is entirely heartfelt. Property conveyed because of services performed is presumed to be compensation. The Supreme Court’s standard from Commissioner v. Duberstein asks whether the transfer flows from “detached and disinterested generosity.” A ranch handed to the very people who managed it for two decades has a difficult time clearing that bar.
If the transfer is payment for their work, its fair market value, minus anything they pay for it, generally becomes taxable income the moment their ownership is no longer subject to a substantial risk of forfeiture. Suppose the ranch is worth $1.2 million and they pay nothing. They may owe tax on $1.2 million of property income without a single dollar of cash to cover withholding, Social Security tax, or Medicare tax. The deed, correspondence, and 20-year employment history all factor into how the IRS characterizes the transaction. A transfer rooted in a close personal relationship completely independent of employment could tell a different story, but that argument faces steep headwinds when the recipients spent their careers on the payroll.
A generous closing can produce a brutal April.
Social Security Does Not Count Every Acre
If both spouses performed services and receive the property, the ranch owners and their advisers must determine how the compensation is divided between them. That allocation affects each spouse’s W-2 and each Social Security earnings record separately. In 2026, Social Security tax applies to wages up to $184,500 per worker, up from $176,100 in 2025. Medicare tax carries no comparable ceiling, and an additional 0.9% Medicare tax applies once wages cross $200,000 for a single filer (or $250,000 for a couple filing jointly).
The ranch may be worth well over $1 million, but neither spouse receives a million-dollar Social Security earnings credit. Only wages up to the annual cap count toward each worker’s record. Those covered wages could replace a lower-earning year in the 35-year benefit calculation and nudge a future monthly check upward. The size of any increase depends on each spouse’s prior earnings history, and it will fall far short of the property’s full value.
Their Current Checks Could Stop First
Because they claimed at 62 and are now 64, the retirement earnings test still applies to both of them. In 2026, someone who will remain below full retirement age for the entire year can earn $24,480 before Social Security begins withholding $1 in benefits for every $2 above that threshold. A large compensation event attributed to either spouse could suspend every remaining check for the year.
Those withheld benefits are not permanently lost. Months skipped under the earnings test eventually produce an upward adjustment to monthly payments once full retirement age arrives. That is a real consolation, but it does nothing to generate the cash needed to cover taxes now. A wage spike of this magnitude could also push up to 85% of their Social Security benefits into taxable income for the year. Then there is the Medicare dimension: because the program uses a two-year lookback on income, a large 2026 earnings event will set their Part B and Part D premiums for 2028 through the income-related surcharge known as IRMAA. For joint filers, that surcharge begins once modified adjusted gross income exceeds $218,000 (based on current bracket levels) and can add thousands of dollars per person per year in premium costs across five income tiers.
Before the Deed Changes Hands
This transfer needs careful planning before anyone signs:
- Have a tax attorney determine whether the ranch is compensation, a genuine gift, or partly both. The owners’ intent matters, but a letter using the word “gift” cannot overpower 20 years of documented employment history.
- Obtain a defensible independent appraisal and determine how any compensation should be allocated between the two spouses.
- Identify where the cash for withholding and taxes will come from. Holding title to valuable land does not help when the IRS wants dollars.
- Review any requirement that they continue working on the property. A service condition can affect when the property becomes taxable and by how much.
Receiving the ranch can still be the opportunity of a lifetime. The danger is arriving at closing land-rich and tax-blind. This couple spent 20 years keeping the operation from being sold. The transfer should not leave them with a tax bill that forces them to sell it anyway.
Editor’s note: This article was updated to note that the 2026 Social Security wage base of $184,500 represents an increase from $176,100 in 2025, and to add context on IRMAA tier surcharges, which can reach several thousand dollars per person per year depending on income level, with the two-year lookback meaning 2026 income will set 2028 Medicare premiums.
Contact [email protected] for any questions or corrections.
Gerelyn Terzo is the author of dividend investing handbook "Dividend Investing Strategies: How to Have Your Cake & Eat It Too." A veteran financial journalist, she covers agri-finance for outlets like Global AgInvesting and the broader stock market and personal finance for 24/7 Wall Street. She began at CNBC and later helped launch Fox Business in New York. Gerelyn currently resides in Woodland Park, Colorado and dabbles in nature photography as a hobby.