They Delayed Social Security Because the Lake House Was Their Safety Net. Then the Lake Dried Up.
They did everything right: enrolled in Medicare, held off on Social Security, and counted on the lake house to carry them through. Then the shoreline vanished and took their entire retirement bridge with it.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
A retired couple in their mid-sixties makes a disciplined decision. They enroll in Medicare but delay Social Security, allowing their future monthly checks to grow. If they need extra money before filing, they can sell or borrow against the lake house. The property has appreciated for two decades. Similar homes once sold within days. A home equity line seems like little more than an application and an appraisal away.
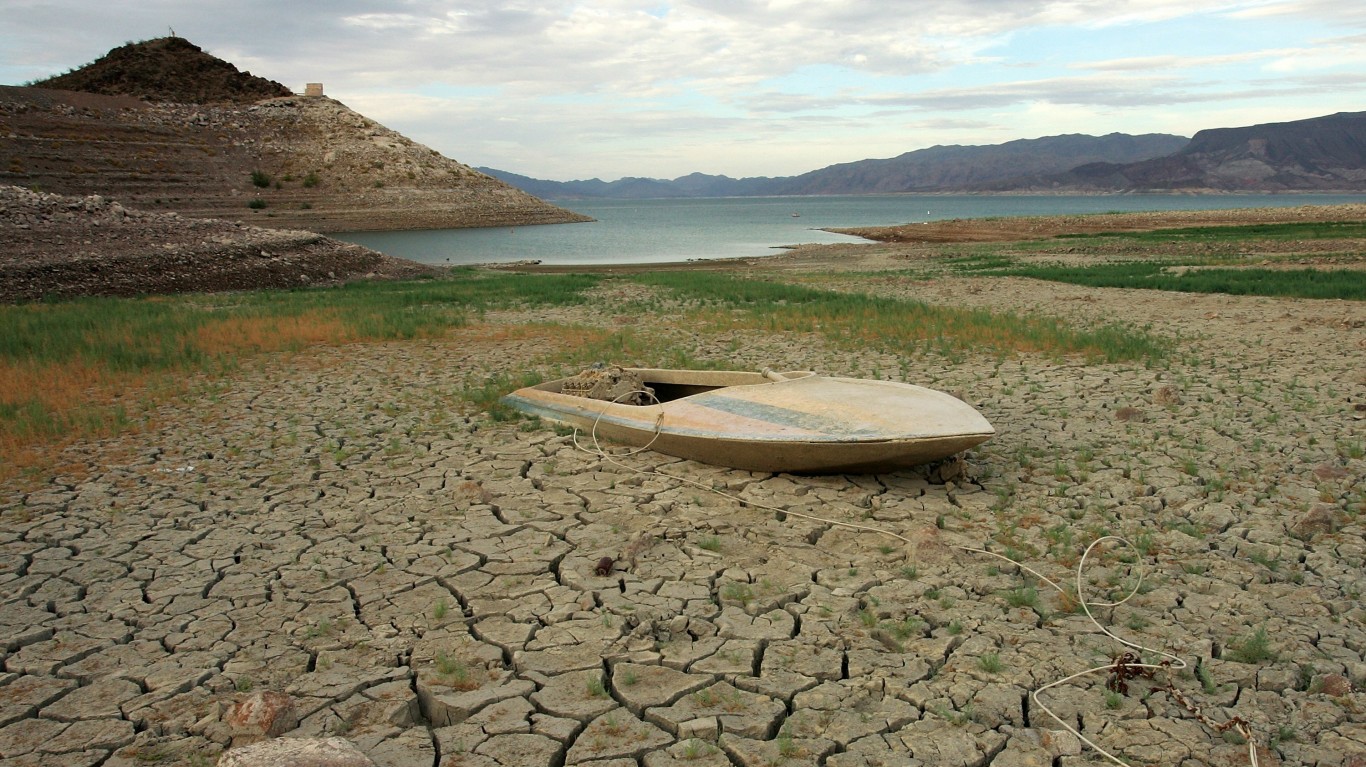
Then the water recedes. Nearby wells run dry, docks hang over cracked mud, and buyers stop calling. The house is still standing, but much of what made it valuable has disappeared with the shoreline. Their Social Security strategy did not fail. The asset funding it did.
This is not a hypothetical. In late September 2026, a broker associate with Keller Williams Realty described exactly this kind of outcome on South Carolina’s Lake Hartwell, where falling water levels have pushed some sellers to accept far less than their asking price. One property listed at roughly $700,000 closed at $580,000 after buyers could no longer see water from the backyard. The gap between what a lake home is worth on paper and what it fetches when the lake recedes can be measured in six figures.
Delaying Requires More Than a Valuable Asset
For workers whose full retirement age (FRA) is 67, claiming Social Security at 62 can cut the scheduled monthly benefit by as much as 30%. Waiting until 67 avoids that early-claim reduction entirely. From FRA through age 70, delayed-retirement credits add 8% per year, compounding into a permanent 24% boost for someone who waits the full three years. That higher benefit lasts for life and provides a larger base for future cost-of-living adjustments. For a higher-earning spouse, delaying also bolsters the survivor benefit eventually available to the other spouse.
The mathematics can be powerful. But delaying Social Security is not only a claiming decision. It is also a financing decision. The household must fund every month between the final paycheck and the first benefit check. A second home can be valuable without being liquid. Selling requires a willing buyer. Borrowing requires sufficient appraised value, acceptable income, and a lender still willing to extend credit. All three can disappear when environmental trouble changes the market.
The House Moved Before They Could Move the Money
Suppose the couple expected the lake house to produce $350,000 in a sale. After the water recedes, buyers begin discounting the cost of a deeper well, an unusable dock, higher insurance, and the possibility that the lake will not recover. Research on Lake Lanier in Georgia found that during severe low-water conditions, shallow cove properties can require price reductions of 20% to 30%, and average days on market can roughly double compared with periods of full pool. The couple could sell for much less, wait indefinitely, or keep paying taxes and maintenance on an asset that no longer fills the role assigned to it.
A home equity line may not rescue the plan. The lender will use the property’s current appraised value, not the figure from when the retirement spreadsheet was built. Retirement income can also make qualifying harder than it would have been during the couple’s working years. Even an existing credit line may not be as dependable as cash, because its terms can allow the lender to limit future borrowing after the property loses value. The lake house was wealth. It was never guaranteed spending money.
They Can Change Course, but Not Recreate the Past
The couple can file for Social Security earlier than planned. Any delay already completed still helps, because the benefit generally rises the longer the worker waits, up to age 70. Retroactive benefits are more limited. Before FRA, a worker cannot request retirement benefits for earlier months if doing so would create an early-claim reduction. At or after that threshold, the Social Security Administration will pay retroactive benefits for up to six months before the application date, but not for any month before FRA was reached. Accepting those months gives up the delayed-retirement credits attached to them, permanently reducing the monthly payment by about 4% in the case of a full six-month lookback.
If the lake deteriorates when the couple is 68, they can begin benefits instead of waiting until 70. They may also request limited retroactivity. What they cannot do is collect every check they intentionally passed up since retirement while keeping the full increase attached to waiting. The strategy bends. It does not run backward.
Build the Bridge Outside the Property
A reliable Social Security bridge should hold enough liquid or predictable assets to cover planned spending plus an unpleasant surprise. Cash, short-term Treasury securities, and certificates of deposit do not depend on a buyer appreciating the view. The couple should also model what happens if the property sells for less than expected or takes two years longer to sell. If either outcome forces an early Social Security claim, a large taxable IRA withdrawal, or expensive credit-card borrowing, the bridge was too dependent on one asset.
IRA withdrawals carry another tradeoff that often catches retirees off guard. Because Medicare’s Income-Related Monthly Adjustment Amount (IRMAA) uses a two-year lookback, a large withdrawal taken today can push a household into a higher Medicare premium bracket two years later. In 2026, the surcharge begins for single filers with modified adjusted gross income above $109,000 and for married couples above $218,000. Crossing a tier line by even one dollar triggers the full surcharge for the entire year. Once Social Security begins, higher taxable income can also pull more of those benefits into taxable income. Liquidity should be planned across the entire retirement picture, not solved account by account during a crisis.
The lake house did not become worthless when the water disappeared. It became unreliable for the one job the couple needed it to perform on demand. Delaying Social Security can strengthen a lifetime income plan, but the asset financing the wait must be dependable before it is merely valuable. A bridge that requires the weather, an appraiser, and a buyer to cooperate simultaneously is still three risks wearing the shape of a house.
Editor’s note: This article was updated to include the Lake Hartwell (South Carolina) example from September 2026, where a $700,000 listed waterfront property sold for $580,000 after water levels fell, and to add current 2026 Medicare IRMAA thresholds ($109,000 single/$218,000 joint) alongside the confirmed 24% maximum delayed-retirement-credit boost for workers with a full retirement age of 67.
Contact [email protected] for any questions or corrections.
Gerelyn Terzo is the author of dividend investing handbook "Dividend Investing Strategies: How to Have Your Cake & Eat It Too." A veteran financial journalist, she covers agri-finance for outlets like Global AgInvesting and the broader stock market and personal finance for 24/7 Wall Street. She began at CNBC and later helped launch Fox Business in New York. Gerelyn currently resides in Woodland Park, Colorado and dabbles in nature photography as a hobby.