Starbucks Will Close 250 Stores. His $20,000 401(k) Loan Won’t Count Against Social Security’s Earnings Test, but It Could Make More of His Benefit Taxable
When Starbucks closes his store, a 64-year-old barista's unpaid 401(k) loan could quietly pull thousands of dollars in Social Security benefits into taxable income, and a deadline most people miss determines whether any of it is avoidable.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
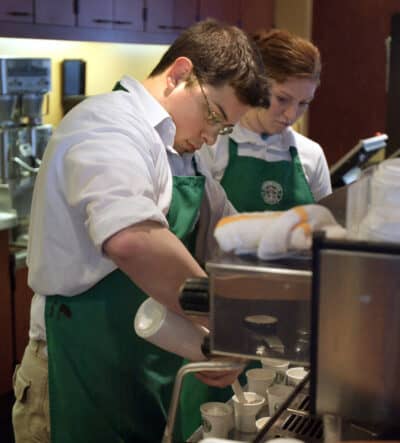
A 64-year-old barista who already collects Social Security has just found out his store is closing. Starbucks (NASDAQ:SBUX | SBUX Price Prediction) plans to shut about 250 North American retail locations in its second wave of closures. Assume he isn’t transferred, he leaves the company, and still owes $20,000 on a 401(k) loan.
His 401(k) loan adds another complication. Because he is already collecting Social Security, the same $20,000 can move through two separate calculations, with each treating it differently.
Why the $20,000 Won’t Shrink His Monthly Check
He’s under full retirement age (FRA), so his Starbucks wages fall under Social Security’s retirement earnings test. In 2026, Social Security holds back $1 of benefits for every $2 he makes above $24,480.
The test counts only wages and net self-employment earnings. Pensions, annuities and 401(k) withdrawals are excluded. If his plan offsets the loan and turns the $20,000 into a taxable distribution, it doesn’t get added to his paycheck total. Say he makes $15,000 at Starbucks this year. He remains under the limit and his benefit is untouched.
How a Store Closing Can Turn a Loan Into a Distribution
A 401(k) loan isn’t taxed as long as it follows plan rules and is being paid back. The closure changes nothing by itself. What matters is whether he leaves the company and what his plan’s loan rules say happens next.
If the plan deducts the unpaid balance from his account, that’s called a loan offset. Suppose his 401(k) held $80,000. After the offset, $60,000 is left, and the $20,000 counts as a distribution unless he rolls it over. Because he’s past 59.5, he owes no early-withdrawal penalty. Regular income tax still applies.
He may have more time than expected. If the loan was in good standing and the offset happened because he left his job, generally within 12 months of his separation, it can qualify as a qualified plan loan offset. He generally has until his tax-return due date for that year, including extensions, to roll $20,000 into an IRA or another eligible plan. With an extension, that can mean up to six months past the normal filing deadline.
Where Social Security Comes Back Into the Picture
To decide how much of his benefit gets taxed, the IRS uses combined income: half his Social Security plus his other income, including taxable retirement distributions. For a single filer, up to 50% of benefits become taxable once combined income passes $25,000, and up to 85% once it passes $34,000. That 85% is the share of benefits that counts as taxable income. His actual tax depends on his bracket.
Suppose his benefit is $24,000 a year and he makes $15,000 before leaving. His combined income is $27,000, so about $1,000 of his benefit is taxable.
His $16,100 standard deduction more than covers that, so he owes essentially no federal income tax.
Add the $20,000 he didn’t replace. His combined income rises to $47,000, and the taxable part of his Social Security grows to about $15,550. That’s an extra $14,550 of benefits on his tax return.
His taxable income comes to about $34,450, putting him in the 12% bracket. His federal tax goes from near zero to about $3,886. Part of that bill falls on Social Security income that was untaxed before the offset.
Putting the Money Back Fixes Both Problems
If he rolls the full $20,000 into an IRA before the deadline, it remains tax-deferred and never counts toward combined income. Most of the benefit stays untaxed. Partial rollover helps, but whatever he doesn’t roll over is taxed.
What to Pin Down Before His Last Shift
- Whether he leaves the company. If he transfers to another store, the loan keeps its normal repayment schedule.
- What his plan does with loans after someone leaves. Some let former employees keep repaying; others offset quickly. His plan’s summary document explains the rules.
- When the offset happens. The calendar year decides which tax return it lands on and which rollover deadline applies.
- Whether it qualifies for the longer deadline. A qualified plan loan offset gets the extended tax-return deadline, while other loan offsets generally get 60 days. A deemed distribution from an earlier default generally cannot be rolled over at all.
- How much the extra income changes the tax on his benefits. Running his combined income with and without the offset shows what replacing the money is worth.
The toughest mistake to undo is missing the deadline. After that, the $20,000 is locked into that year’s income and draws more of his Social Security into taxable income. It’s one of several IRS rules that quietly drain retirement accounts, and we mapped the rest in a free tax trap guide. If he has severance or cash savings, using them to refill the IRA protects two things: his retirement money and the tax treatment of his benefits.
Contact [email protected] for any questions or corrections.
Gerelyn Terzo is the author of dividend investing handbook "Dividend Investing Strategies: How to Have Your Cake & Eat It Too." A veteran financial journalist, she covers agri-finance for outlets like Global AgInvesting and the broader stock market and personal finance for 24/7 Wall Street. She began at CNBC and later helped launch Fox Business in New York. Gerelyn currently resides in Woodland Park, Colorado and dabbles in nature photography as a hobby.