A Sonoma, California Winery Just Filed Chapter 11 With $39M in Liabilities. At 63, His Vineyard Loss Can Offset His Wages in Social Security’s Earnings Test

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
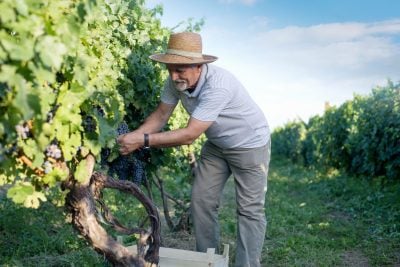
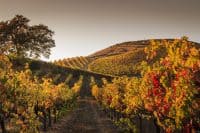
Gundlach Bundschu, California’s oldest continuously family-owned winery, filed for Chapter 11 protection on September 23, 2026, after 168 years of operation. The Sonoma Valley winery, founded in 1858 and known locally as GunBun, filed through its operating company Vineburg LLC in U.S. Bankruptcy Court for the Northern District of California. Its petition listed about $39.1 million in liabilities against $17.2 million in assets. The winery plans to stay open as it restructures, though the Bundschu family expects to lose majority ownership as part of any deal with a new investor.
The road to bankruptcy began with a debt-financed acquisition in 2020, which expanded the family’s footprint just weeks before the COVID-19 pandemic upended the hospitality business. What followed were years of falling wine demand, distributor consolidation, and excess inventory. Over three years, the family cut expenses by more than 40%, about $6 million, reduced its workforce, and ultimately closed its sibling property Abbott’s Passage before the bankruptcy filing. It still was not enough to overcome the debt load.
The winery’s struggles reflect a broader industry crisis. According to Silicon Valley Bank’s 2026 State of the U.S. Wine Industry Report, total U.S. wine revenue fell 21% from $94 billion in 2020 to $74.3 billion in 2025, a drop of nearly $20 billion. The report projects the industry won’t bottom out until 2027 or 2028.
Wine country is struggling, and small growers are feeling it acutely. Consider a hypothetical 63-year-old collecting Social Security who works a job paying wages and runs a small vineyard as a sole proprietor. This year the vineyard lost money. He assumes his paycheck alone will cause Social Security to withhold part of his monthly check. He may have missed a deduction built into Social Security’s earnings test.
His Paycheck Is Only Half of Social Security’s Math
At 63 in 2026, his full retirement age (FRA) is 67. Until then, Social Security applies an earnings test, essentially a ceiling on work income. In 2026 the annual limit is $24,480, and the agency holds back $1 of benefits for every $2 earned above it.
Say he earns $40,000 in gross wages this year. If Social Security counts only his paycheck, it would hold back $7,760, or about $647 a month.
Social Security’s rule adds wages and net self-employment earnings together, then deducts a qualifying net self-employment loss. Suppose the vineyard had a real net loss for the same year:
- Gross wages: $40,000
- Vineyard net self-employment loss: $20,000
- Countable earnings: $20,000
That leaves him $4,480 under the limit, so the annual test calls for no holdback at all. The vineyard loss wiped out the entire $7,760.
One detail trips people up. When a sole proprietor makes a profit, Social Security counts 92.35% of it, mirroring the IRS rule for self-employment tax. For a loss, the agency instructs its staff to apply the actual net loss with no adjustment. The full $20,000 gets deducted.
This example assumes he started benefits before 2026, so the annual test applies all year.
Losses That Look Similar But Won’t Reduce His Earnings
The loss has to come from a real vineyard business run to make a profit, where allowable business expenses were higher than business income. Several losses that appear similar won’t count:
- A buyer’s bankruptcy. Even if a winery that buys his grapes files Chapter 11, the filing by itself doesn’t create a net self-employment loss Social Security can use here.
- Falling land values. A lower assessment on his acreage leaves his business income and expenses unchanged.
- Investments in other companies. Money lost investing in someone else’s business stays outside his own self-employment calculation.
- S corporation losses. If the vineyard were set up as an S corporation, a loss passing through to his tax return would not count as a net self-employment loss.
Timing Rules That Can Wipe Out the Offset
The offset only works within one tax year. A 2026 vineyard loss can reduce 2026 wages. A net operating loss carried forward from an earlier year cannot, even if it lowers his taxable income on the return.
The offset also leaves two things unchanged. He does not get back the payroll taxes already withheld from his paychecks. And he still carries the permanent reduction he accepted by claiming benefits before FRA.
Any benefits that do get withheld are not simply lost. At FRA, Social Security recalculates his benefit upward to credit him for the months when checks were withheld. Still, cash held up for years has real cost when a business is bleeding money now.
Get the Paperwork in Order Before Withholding Starts
Social Security’s first withholding estimate may be based on his wages alone. Before accepting it, he should document the qualifying business loss, confirm it belongs to 2026, and submit an updated earnings estimate to the agency.
His W-2, his Schedule F (the farm income form on his federal tax return), and his underlying business records together should show how the wages and the loss fit together. He should also confirm how the loss is classified, because not every deduction on a tax return produces this result.
A Hard Harvest Shouldn’t Cost Extra
The vineyard still lost $20,000. Holding back $7,760 from his Social Security payments does nothing to improve that outcome. Counting only his paycheck, however, would make a bad harvest more expensive than the rules actually require.
The mistake hardest to undo is allowing benefits to be held back for months because of an incomplete earnings estimate. Small facts, including how the business is organized and which year a loss falls in, can change the answer entirely. Checking the numbers against actual records well before year-end is the only way to avoid that outcome.
Editor’s note: This article was updated to add that the Bundschu family is expected to lose majority ownership through the Chapter 11 process, that the cost cuts totaled approximately $6 million over three years, that a 2020 debt-financed acquisition preceded GunBun’s financial troubles, and that U.S. wine industry revenue fell 21% between 2020 and 2025 according to Silicon Valley Bank’s 2026 State of the U.S. Wine Industry Report.
Contact [email protected] for any questions or corrections.
Gerelyn Terzo is the author of dividend investing handbook "Dividend Investing Strategies: How to Have Your Cake & Eat It Too." A veteran financial journalist, she covers agri-finance for outlets like Global AgInvesting and the broader stock market and personal finance for 24/7 Wall Street. She began at CNBC and later helped launch Fox Business in New York. Gerelyn currently resides in Woodland Park, Colorado and dabbles in nature photography as a hobby.