A $2.2 Billion Texas Minerals Platform Will Control 111,000 Royalty Acres. Social Security Draws a Line Between Owning the Royalty and Working the Well
A $2.2 billion Permian Basin minerals platform is betting landowners can collect royalty checks without ever touching a drill rig, but for retirees on Social Security, the difference between owning the royalty and owning the operation can flip a clean…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
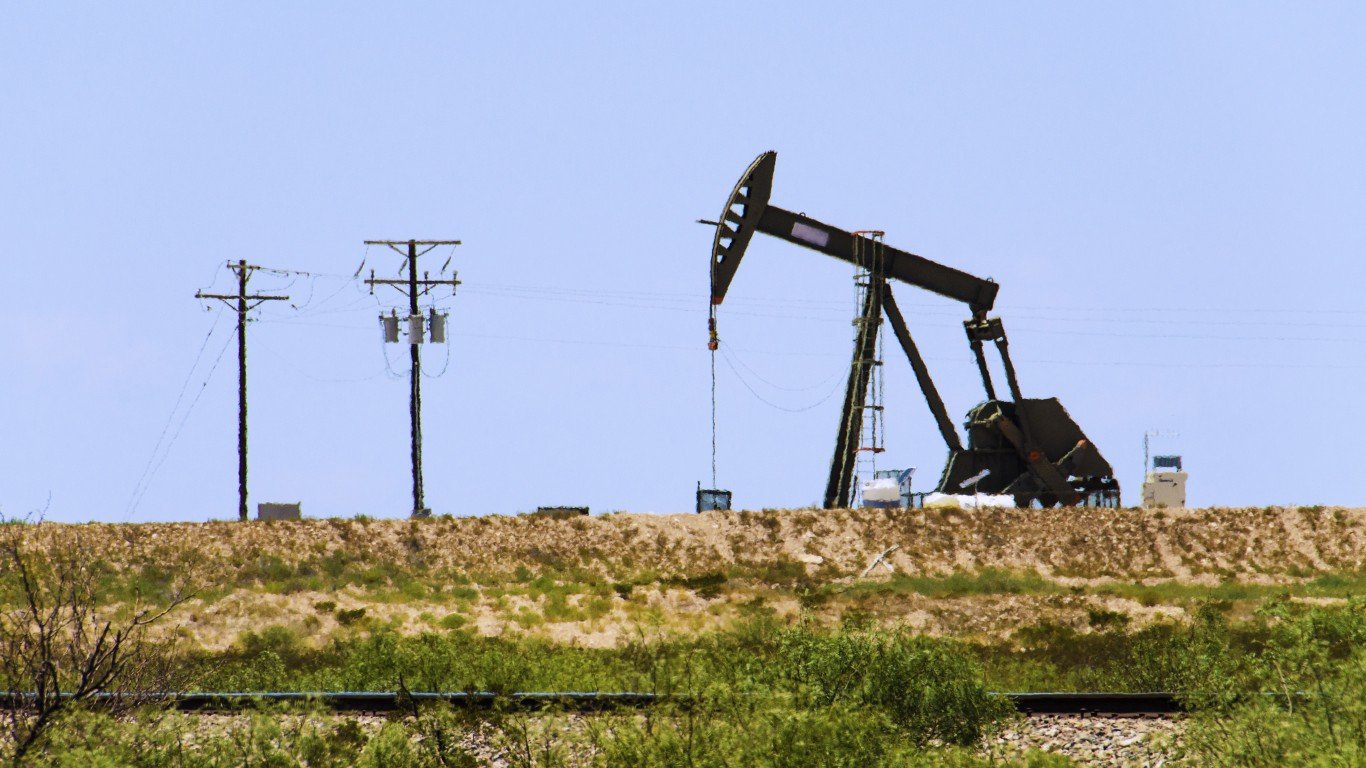
A proposed $2.2 billion combination between Permian Basin Royalty Trust (NYSE:PBT) and Blackbeard would create PBT Land and Minerals. The new platform would hold roughly 111,000 net royalty acres and 68,000 surface acres in the Permian Basin. The whole deal is built on one idea: you can collect money from minerals under the ground without ever running a drilling rig.
Imagine a 64-year-old mineral owner who collects Social Security, earns $20,000 a year from part-time work, and gets about $30,000 annually in oil-and-gas royalties. A strong production year could push him over the earnings limit and cost him benefit checks.
Whether that happens depends on what kind of interest he has. The same oil in the same ground can land him on either side of Social Security’s line.
How a $30,000 Royalty Check Can Count as $0 in Earnings
The earnings test holds back some benefits from people who claim before full retirement age and keep working. It counts only wages and net earnings from self-employment.
IRS instructions put royalties from oil, gas and mineral properties on Schedule E, the form for rental and royalty income. Royalty income on Schedule E generally isn’t subject to self-employment tax. Because the earnings test tracks work income, royalties generally add $0 toward the limit.
The money is still taxable as ordinary income, but it generally remains outside self-employment earnings for Social Security’s earnings test.
A Working Interest Puts Him on the Other Side of the Line
A working interest means he has part of the operation itself and pays his share of drilling and production costs. IRS guidance says owners with a working interest in extraction operations are subject to self-employment tax, and must file Schedule C, the form for business profit and loss. He doesn’t need to work at the well for this to apply; what determines it is how he has the interest.
| Item | Royalty Owner | Working-Interest Owner |
|---|---|---|
| Net income | $30,000 royalty | $30,000 after operating costs |
| Tax form | Schedule E | Schedule C |
| Self-employment tax | Generally none | Generally applies |
| Counts toward earnings test | Generally $0 | Yes |
Same $30,000 but Different Treatment
At 64, he hasn’t reached full retirement age (FRA). In 2026 the annual earnings limit is $24,480. Social Security withholds $1 in benefits for every $2 earned above that amount.
If the $30,000 is a royalty, his countable earnings stay at his $20,000 in wages. He still has $4,480 of room under the limit, and nothing is withheld.
If it comes from a working interest, Social Security generally counts net self-employment earnings, which are calculated using 92.35% of net profit after business expenses. That brings his countable total to roughly $47,705. After the $1-for-$2 math, about $11,600 in benefits would be withheld that year.
Withheld benefits are not simply repaid later. At FRA, Social Security recalculates his monthly benefit to credit the months benefits were withheld.
Royalties Still Raise the Tax Bill on His Benefits
The $30,000 royalty increases his adjusted gross income, which feeds the “combined income” figure that sets how much of his Social Security is taxable.
For single filers, benefits start becoming taxable above $25,000 of combined income. Above $34,000, up to 85% of his Social Security benefits can become taxable. His wages and taxable royalty income put him well past that threshold, so the royalty can count as $0 for the earnings test while still increasing the combined income used to determine how much of his Social Security is taxable.
Paperwork to Check Before He Counts the Income
- Deed or lease: Determine whether he holds a royalty or a working interest.
- Tax form: Check whether past returns reported the income on Schedule E or Schedule C.
- Operating costs: Responsibility for drilling or production expenses can signal a working interest, so check the deed or operating agreement.
- Other earnings: Add wages and side business income to see how close he is to the limit.
- Combined income: See how far above the Social Security tax thresholds he sits.
- Entity structure: Whether he holds the interest directly or through a partnership can change treatment.
What to Settle Before He Buys Into a Well
For this retiree, the key question is what kind of interest he has. A royalty can grow without impacting his benefit checks. A working interest of the same size can hold back thousands of dollars. The earnings test goes away entirely at FRA, which is 67 for anyone born in 1960 or later. Timing a working-interest purchase around that milestone may matter as much as the price.
Each mineral interest comes with its own deed and its own tax history, and one clause in a lease can put income on a different line of his return. Checking his own documents before a strong production year arrives costs a lot less than dealing with withheld benefits later.
Contact [email protected] for any questions or corrections.
Gerelyn Terzo is the author of dividend investing handbook "Dividend Investing Strategies: How to Have Your Cake & Eat It Too." A veteran financial journalist, she covers agri-finance for outlets like Global AgInvesting and the broader stock market and personal finance for 24/7 Wall Street. She began at CNBC and later helped launch Fox Business in New York. Gerelyn currently resides in Woodland Park, Colorado and dabbles in nature photography as a hobby.