He Takes a $60,000 Severance at 63 as Warehouses Fill With Robots That Never Ask for a Wage, and Fears the Payout Will Wipe Out His First Year of Social Security. Pre-Retirement Income Can Count as a Special Payment, Sitting Outside the $25,560 Earnings Limit

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
A hypothetical warehouse worker who turns 63 this year gets the call long-tenured workers dread. His job is going away, and a $60,000 severance check is on the table. A recent Fortune piece captured the background, entitled “Tesla (NASDAQ:TSLA | TSLA Price Prediction) and Amazon (NASDAQ:AMZN) are building the workforce a 1921 play imagined: One that never asks for a wage.”
Last year, Amazon sent its millionth robot into its warehouses. To be fair, Amazon’s human head count also climbed higher last year to approximately 1.58 million.
His plan is to start Social Security in January and live on the severance plus his monthly check. His fear is that the payout counts as income in his first benefit year and Social Security takes back most of his checks. That worry is common among people pushed out a few years early, and it rests on a real rule. It also misses a second rule that usually protects him.
How $60,000 Could Erase a Full Year of Checks
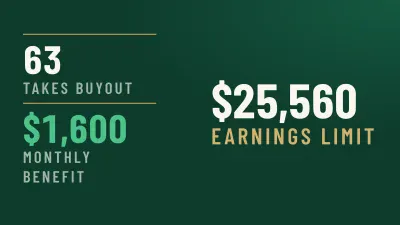
For anyone born in 1960 or later, full retirement age (FRA) is 67[1]. Until then, Social Security applies an earnings test. In 2027 the limit is $25,560[2], and the agency deducts $1 in benefits for every $2 you earn above it.
Here is what that would look like if the severance counted. Say his benefit at 67 would be $2,000 a month. Taking at 63 cuts that to about $1,500, or $18,000 for the year. Counting the severance as 2027 earnings would trigger $17,220 in withholding, which is nearly every check he expected that year.
Pay Earned Before Retirement Gets Its Own Treatment
Social Security defines earnings as wages “for services rendered in a taxable year,” so it links pay to the year the work happened, even when the check arrives later. Severance, accumulated vacation and bonuses earned before you retire are called special payments, and they aren’t counted toward the earnings test limit once you have stopped working.
If his last day on the job falls in 2026 and benefits begin in January 2027, the severance belongs to his working years. His countable 2027 earnings are zero, and he keeps all 12 checks.
A second protection covers the first year. Under a special rule[3], you receive a full benefit for any month you are considered retired, no matter what you earned earlier in the year. For 2027, that means monthly earnings of $2,130 or less and no substantial self-employment.
The risk lies in the paperwork. His employer will probably report the severance on his 2027 W-2, and the agency’s systems may read that as 2027 earnings. His former employer can be asked to file Form SSA-131, the employer report of special wage payments, while he keeps his severance agreement showing the money covers past service. That paperwork can head off withheld checks and an overpayment notice months later.
Where Severance Still Hits: Your Tax Return
The earnings test is only one part of the picture. For federal taxes, severance counts as ordinary wages, subject to income tax withholding plus Social Security and Medicare taxes. If the check lands in 2027 alongside his benefits, the extra income can make up to 85%[4] of that year’s Social Security taxable.
That raises a bigger question than the earnings test. If $60,000 can cover a year of living costs, he could live on the severance and taking at 64 instead. In the example above, that raises his check from $1,500 to $1,600 a month.
That is $1,200 more every year for life. Cost-of-living increases, like the 3.6% raise earmarked for 2027, are applied to that bigger base. He also needs to set aside part of the severance for health insurance, since Medicare usually starts at 65.
Two Decisions to Get Right Before You File
- Get the timing in writing. Find out the exact last day you are paid for work and the date the severance is paid, and get both in writing from the employer. Special-payment treatment depends on showing the money was earned before your retirement date. A severance letter that lists out the dates makes that easy to prove.
- Choose your taking age for the right reason. If you taking at 63 only because you fear the severance will cost you benefits, the reduced check stays with you for life, and that is the toughest mistake to fix. Once the earnings test is off the table, the real choice is between using the severance as a bridge to a bigger check and starting a smaller check now.
The details of each severance agreement and work history vary, so a short call with Social Security before filing can confirm how your payment will be counted.
Contact [email protected] for any questions or corrections.
Gerelyn Terzo is the author of dividend investing handbook "Dividend Investing Strategies: How to Have Your Cake & Eat It Too." A veteran financial journalist, she covers agri-finance for outlets like Global AgInvesting and the broader stock market and personal finance for 24/7 Wall Street. She began at CNBC and later helped launch Fox Business in New York. Gerelyn currently resides in Woodland Park, Colorado and dabbles in nature photography as a hobby.