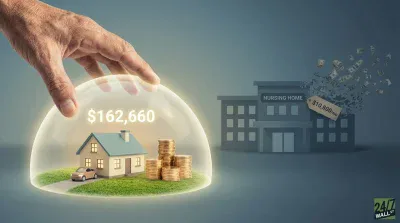
The Nursing Home Wanted $10,800 a Month. A Medicaid Rule Called the “Community Spouse Resource Allowance” Let His Wife Keep $162,660 and Every Dollar of Her Own Income
When one spouse enters a nursing home, most families assume every dollar of savings must go toward the bills before any help arrives. A federal spousal protection rule says otherwise, and the families who never hear about it in time…

The couple has a paid-off house, a checking account, two IRAs, Social Security, and a nursing home billing $10,800 a month. Their adult children Google “Medicaid nursing home” and land on pages saying Mom and Dad must spend down to $2,000 before any help arrives. Everyone panics.
Then the family meets with an elder law attorney and learns two things. First, a rule called the Community Spouse Resource Allowance (CSRA) lets the wife, still living at home, keep $162,660 of the couple’s countable savings under her state’s application of the rule. Second, and this is the part almost no one hears about until it is too late, her own Social Security check and her own small pension go untouched. She keeps every dollar of her own income while Medicaid pays the nursing home for her husband.
What the Community Spouse Resource Allowance Actually Does
Medicaid, not Medicare, pays for long-term nursing home stays once a person qualifies financially. Medicare covers only short rehab stints after a qualifying hospital admission, with a daily copay of $217 for days 21 through 100 in a skilled nursing facility in 2026, after which coverage ends entirely. Confusing the two is the single most expensive mistake families make, and it is an easy one when hospital discharge planners are moving fast.
When one spouse enters a nursing home and applies for Medicaid, that spouse becomes the institutionalized spouse. The one still living at home is the community spouse. The CSRA is a federal spousal impoverishment protection that shields a portion of the couple’s countable resources for the at-home spouse, rather than letting every dollar drain into nursing home bills. Congress built this rule specifically because too many at-home spouses were being left destitute. Today Medicaid covers roughly two-thirds of all nursing home residents in the United States, which tells you how common this planning situation is.
For 2026, the federal CSRA range runs from a minimum of $32,532 to a maximum of $162,660, up from $157,920 in 2025 after a 3% inflation adjustment. States must set their own limits somewhere within that federal band. Some states use the maximum; others use a percentage of the couple’s assets up to that ceiling; a few have their own fixed figure. Illinois, for example, uses $143,172 as its standard, while South Carolina sets its standard at $66,480. A reader’s own number can differ from the figure in this story, sometimes significantly. Confirm the current amount with your state Medicaid agency before touching a dime.
The Income Rule That Protects the At-Home Spouse
Once a spouse is institutionalized and applying for Medicaid, the community spouse’s own income is not counted toward the institutionalized spouse’s eligibility. Her Social Security, pension, and any part-time paycheck belong to her. This is sometimes called the “name on the check” rule: whichever spouse’s name is on the check keeps that income for Medicaid eligibility purposes.
But if the community spouse’s own income falls below a floor called the Minimum Monthly Maintenance Needs Allowance (MMMNA), federal rules allow some of the institutionalized spouse’s income to be diverted to her rather than paid to the nursing home. The MMMNA exists because Congress recognized that the at-home spouse still has a mortgage or rent, utilities, groceries, and a car. For 2026, the federal MMMNA ranges from $2,705 to $4,066.50 per month in most states, with the minimum tied to the federal poverty level and adjusted each July 1. When housing costs are high, states can raise the allowance toward the ceiling dollar for dollar. Ask the caseworker for the current figure in writing.
What Is Not Protected, and Where Families Get Hurt
The institutionalized spouse’s own income is not protected. His Social Security and pension flow to the nursing home each month, minus a small personal needs allowance the state sets for haircuts, phone, clothing, and toothpaste. That allowance is famously modest, typically well under $100 a month in most states.
Families also get hurt by moving too fast. Spending down before requesting a resource assessment can shrink the CSRA the community spouse is entitled to. A resource assessment is the formal snapshot Medicaid takes of the couple’s countable assets on the date of institutionalization, and its timing matters. Gifting assets to adult children inside the five-year lookback creates a transfer penalty, a period during which Medicaid will not pay even if the applicant otherwise qualifies. State rules can also shift without warning: California, for instance, reinstated its own asset limits and lookback requirements effective January 1, 2026, after operating without them for two years. Advice that worked for a neighbor in another state, or even in the same state last year, may no longer apply.
What Families Should Do at the Point of Institutionalization
Request the resource assessment on day one. Do not liquidate accounts, do not pay off the mortgage in a lump sum, and do not write checks to the kids before an elder law attorney licensed in your state has reviewed the balance sheet. Confirm the current CSRA maximum, MMMNA, home equity limit (set at $1,239,125 federally for 2026), and penalty divisor with your state Medicaid agency, because these figures reset annually.
Nursing home costs nationwide now run roughly $9,600 to $11,000 per month depending on room type, so the financial stakes are real from the first invoice. The community spouse in this story kept $162,660 and every dollar of her own Social Security and pension. She kept them because someone told her the rule existed before she started writing checks. That is the whole difference.
Editor’s note: This article was updated to add the 2026 federal CSRA minimum of $32,532, the year-over-year increase in the CSRA maximum from $157,920 in 2025 to $162,660 in 2026, the current MMMNA range of $2,705 to $4,066.50 per month, the 2026 federal home equity limit of $1,239,125, Medicare’s 2026 skilled nursing facility daily copay of $217 for days 21 through 100, and California’s reinstatement of Medicaid asset limits and lookback requirements effective January 1, 2026.
Contact [email protected] for any questions or corrections.
Jake has been been working in financial media for almost 15 years. He focuses on all things personal finance for 24/7 Wall St. with high hopes to educate and entertain. Most recently, Jake spent 12 years working various roles at The Motley Fool. He started copy editing fool.com content, worked on premium and marketing campaigns, and helped launch The Ascent, a personal finance brand.
His work has been featured on platforms like MSN, Yahoo Finance, USA Today, and more. He's written about credit cards, social security, ETFs, savings accounts, and just about anything else you can imagine when thinking about money. Jake love to cook, play golf, and tell people he's never had a cavity. (It's true!)