Suze Orman’s Top Retirement Advice You Shouldn’t Ignore
At some point, we all want to retire comfortably. But to do so, you need to plan ahead, as finance expert Suze Orman consistently emphasizes. She points to six key principles that anyone nearing retirement should take seriously, from starting…


Retirement is a goal most Americans share, but reaching it comfortably requires planning that starts long before the final day on the job. Finance expert Suze Orman has spent decades translating that planning into clear, actionable guidance, covering everything from the compounding power of early saving to the real cost of claiming Social Security before your full retirement age. Below are the six principles she returns to most often.
No. 1: Save Early and Consistently
Compound interest is the single most powerful tool available to retirement savers. It rewards patience above everything else, and every year you delay getting serious about saving is a year that compounding cannot work in your favor.
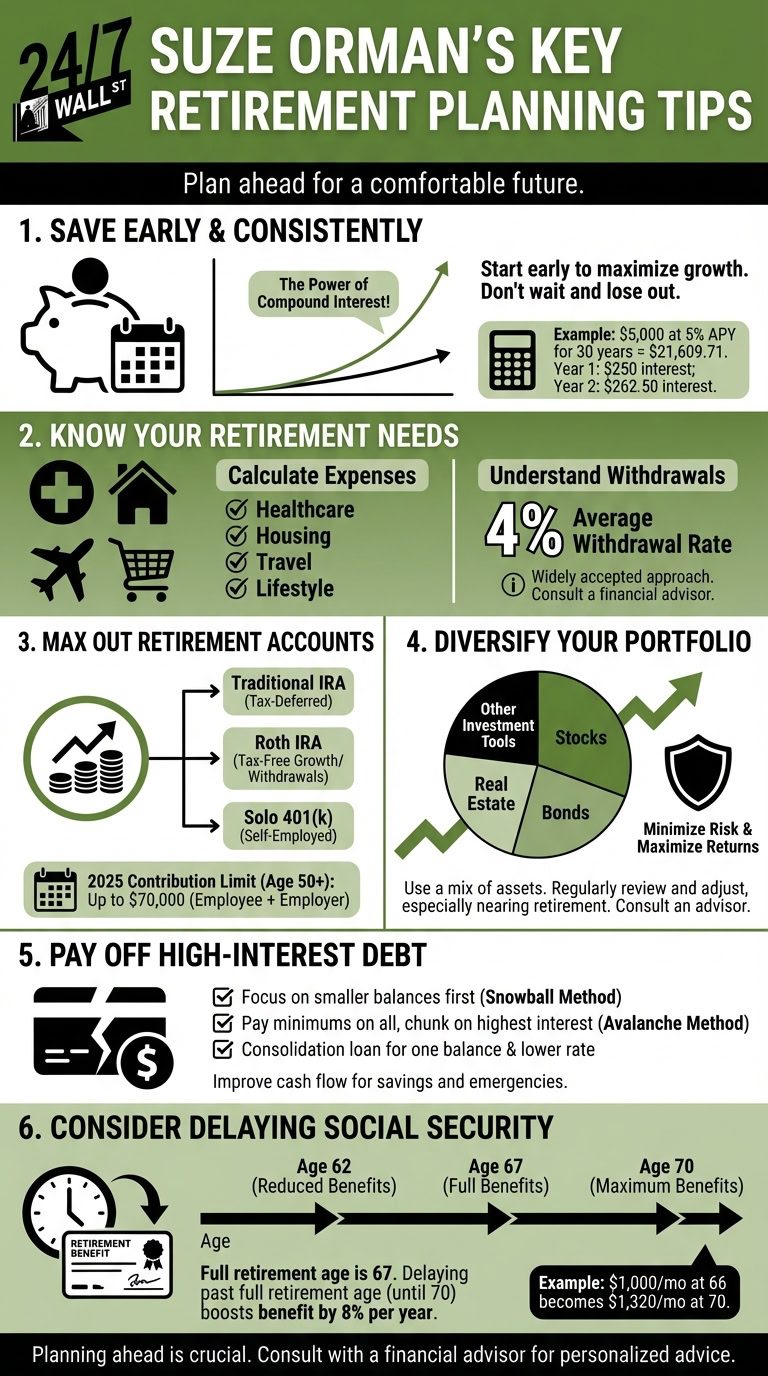
A simple example makes the case. Put $5,000 into a savings account earning 5% annually and you collect $250 in year one, leaving a balance of $5,250. In year two, that same 5% applies to the larger balance, netting $262.50, and the growth accelerates from there. Leave the original $5,000 untouched for 30 years at that rate and the account grows to $21,609.71 without a single additional deposit. Time, more than any rate of return, is what turns modest contributions into a substantial nest egg.
Orman’s broader message is consistent. As she wrote in a 2025 post on her website, “The earlier you start, the better prepared you’ll be to enjoy the retirement you deserve.” She has also emphasized a less conventional angle: investing in your physical health is itself a retirement strategy, because poor health is among the leading reasons workers are forced out of the workforce before they are financially ready.
No. 2: Know Your Retirement Needs
Before you can fund your retirement, you need to understand what it will actually cost. That means taking an honest inventory of expected expenses across healthcare, housing, and lifestyle. A globetrotting retirement looks very different on paper than one spent close to home, and projecting those costs realistically is the essential first step.
One widely used starting point is the 4% annual withdrawal rule: drawing no more than 4% of your portfolio each year gives you a high probability of not outliving your savings over a 30-year horizon. Orman has gone further, calling the rule “very dangerous” in interviews and recommending a 3% starting withdrawal rate for anyone retiring in their early 60s. Her position: if you wait until around age 70 to begin withdrawals and have guaranteed income covering most of your living costs, 4% may be workable. For most retirees, a more conservative approach is the safer starting point. Consulting a financial advisor before committing to any specific withdrawal rate is strongly recommended.
No. 3: Max Out Your Retirement Account Contributions
Tax-advantaged accounts are among the most efficient vehicles for building retirement wealth. A traditional IRA lets you invest on a tax-deferred basis, with contributions often deductible from your taxable income. A Roth IRA works differently: contributions come from after-tax dollars, but growth and qualified withdrawals are entirely tax-free. For 2026, the IRS set the annual IRA contribution limit at $7,500, up from $7,000 in 2025. Roth IRAs carry income limits: individuals must have a modified adjusted gross income below $153,000 to make a full contribution, with a phaseout range up to $168,000. For married couples filing jointly, the full-contribution threshold is $242,000, phasing out at $252,000. Your financial advisor can help determine which account structure fits your situation.
For the self-employed, the Solo 401(k) offers especially generous limits. In 2025, the combined employee-plus-employer contribution cap sits at $70,000 for those under 50. Savers aged 50 to 59 or 64 and older can add a $7,500 catch-up contribution, raising their ceiling to $77,500. Participants aged 60 to 63 qualify for a higher “super catch-up” of $11,250 under SECURE 2.0, bringing their 2025 total to $81,250. For 2026, the base cap rises to $72,000, with the standard catch-up increasing to $8,000 for those 50 and older (ceiling: $80,000). Participants aged 60 to 63 in 2026 still qualify for the $11,250 super catch-up, pushing their combined ceiling to $83,250. One wrinkle effective in 2026: savers who earned more than $150,000 in prior-year FICA wages must make catch-up contributions on a Roth basis rather than pre-tax. Orman’s core advice remains straightforward: maximize these accounts before directing money elsewhere.
Even if you have access to a workplace 401(k), Orman recommends choosing the Roth option when available. Contributing just enough to a traditional 401(k) to capture any employer match, then directing additional retirement savings into a Roth IRA, is the tax-smart combination she has consistently recommended.
No. 4: Diversify Your Portfolio
Spreading investments across multiple asset classes reduces the risk that any single holding can derail your retirement timeline. Orman recommends blending stocks, bonds, and other assets such as real estate to smooth out volatility over the long run. Stocks provide the growth needed to outpace inflation, while bonds offer stability when markets swing. The right allocation shifts as retirement draws closer, which is why Orman consistently urges savers to revisit their portfolio regularly and work with a financial advisor as the target date approaches. A portfolio calibrated for a 45-year-old will likely need meaningful adjustments by 60.
No. 5: Pay Off High-Interest Debt
Carrying a credit card balance into retirement is a serious financial hazard. Federal Reserve data shows the average credit card interest rate stood at 21.15% as of May 2026, near the record high of 21.76% reached in August 2024, and rates can run significantly higher for borrowers with lower credit scores. Paying that kind of interest on a fixed income creates a heavy and unnecessary drain on resources. The goal is to enter retirement debt-free, or as close to it as possible.
Three approaches can help accelerate payoff. First, tackle the smallest balances first: eliminating them quickly frees up cash flow that can be redirected toward larger, higher-rate accounts. Second, make minimum payments on all accounts while directing every available dollar at the balance carrying the highest interest rate. Third, consider a debt consolidation loan to roll multiple balances into one lower-rate obligation, simplifying repayment and potentially freeing up room to start building an emergency reserve.
On emergency savings, Orman is notably conservative. She recommends keeping eight months of living expenses in a dedicated savings account, separate from checking, to protect retirement investments from being tapped during an unexpected financial setback. Her guidance for those already in retirement goes further: in recent commentary, Orman has said retirees should keep three to five years of living expenses not covered by Social Security in a liquid, low-risk account. That buffer is designed to prevent forced selling of investments during a market downturn, giving a portfolio time to recover before withdrawals become necessary.
No. 6: Consider Delaying Social Security
For anyone born in 1960 or later, full retirement age (FRA) is 67. Claiming at exactly that age locks in the standard benefit. Waiting past FRA is where the meaningful upside lies. According to the Social Security Administration, benefits grow by approximately 8% for each full year you delay past FRA, up to age 70. For a retiree with an FRA of 67 who waits until 70, that translates to a 24% larger monthly check for life. Claiming as early as age 62, by contrast, permanently locks in just 70% of the earned benefit, a 30% reduction that compounds against you across every future cost-of-living adjustment.
The 2026 Social Security cost-of-living adjustment came in at 2.8%, boosting the average retired worker’s monthly benefit by $56, from $2,015 to $2,071, according to SSA estimates. Because that percentage applies to your base benefit, a smaller check from claiming early means a smaller dollar raise every single year. In a June 2026 blog post, Orman pushed back sharply on social media voices urging Americans to claim at 62, calling that advice a permanent pay cut for most people. Her position: the math favors waiting in nearly every scenario except a serious health condition or a genuine cash need.
For married couples, the calculus is even clearer. The higher earner should wait as long as possible, ideally to age 70, because the surviving spouse inherits the larger of the two benefits. Maximizing the higher earner’s check is, in effect, buying the longest-living spouse a bigger inflation-adjusted income for life.
Orman has also acknowledged that working until 70 is not realistic for everyone. The 26th Annual Transamerica Retirement Survey, covering more than 7,600 middle-class Americans, found that 48% of retirees left the workforce sooner than they had planned, with a median exit age of 63. Among those who retired early, more than half cited employment-related reasons. Just 10% of surveyed retirees made it to age 70 or older before leaving the workforce. If an exit in your early or mid-60s is likely, Orman recommends a bridge strategy: draw from IRA or 401(k) assets during those early retirement years to avoid tapping Social Security, preserving the larger future benefit. Part-time income during the bridge period can reduce how much you need to pull from savings. One firm rule: do not delay past 70. The 8% annual credit stops accruing at that point, so there is no financial reason to wait any longer.
Editor’s note: This pass updated the Transamerica retirement survey figures to reflect the 26th Annual survey (April 2026), which found a median exit age of 63 (not 62) and 48% of retirees departing sooner than planned. The 2026 IRA contribution limit of $7,500 (up from $7,000 in 2025) was added per IRS IR-2025-244. Orman’s cash-reserve guidance for retirees was refreshed to reflect her more recent recommendation of three to five years of living expenses in liquid reserves, per August 2026 commentary.
Contact [email protected] for any questions or corrections.
Ian Cooper is a veteran market analyst and investment strategist with more than 20 years of experience covering stocks, commodities, and macro trends. Since 1999, he has helped investors identify market opportunities using a blend of technical analysis, fundamental research, and market sentiment.
He is the creator of the ADD News Flow Strategy, which focuses on trading market reactions to major news events and investor psychology. Cooper was also among the analysts who warned about the 2008 financial crisis and major financial institution collapses ahead of the broader market.
Before joining 247 Wall St., Cooper wrote extensively for InvestorPlace and other financial publications, covering market trends, trading strategies, and investment opportunities.