Big Salesforce Price Target Cuts Ahead of Q4 Earnings
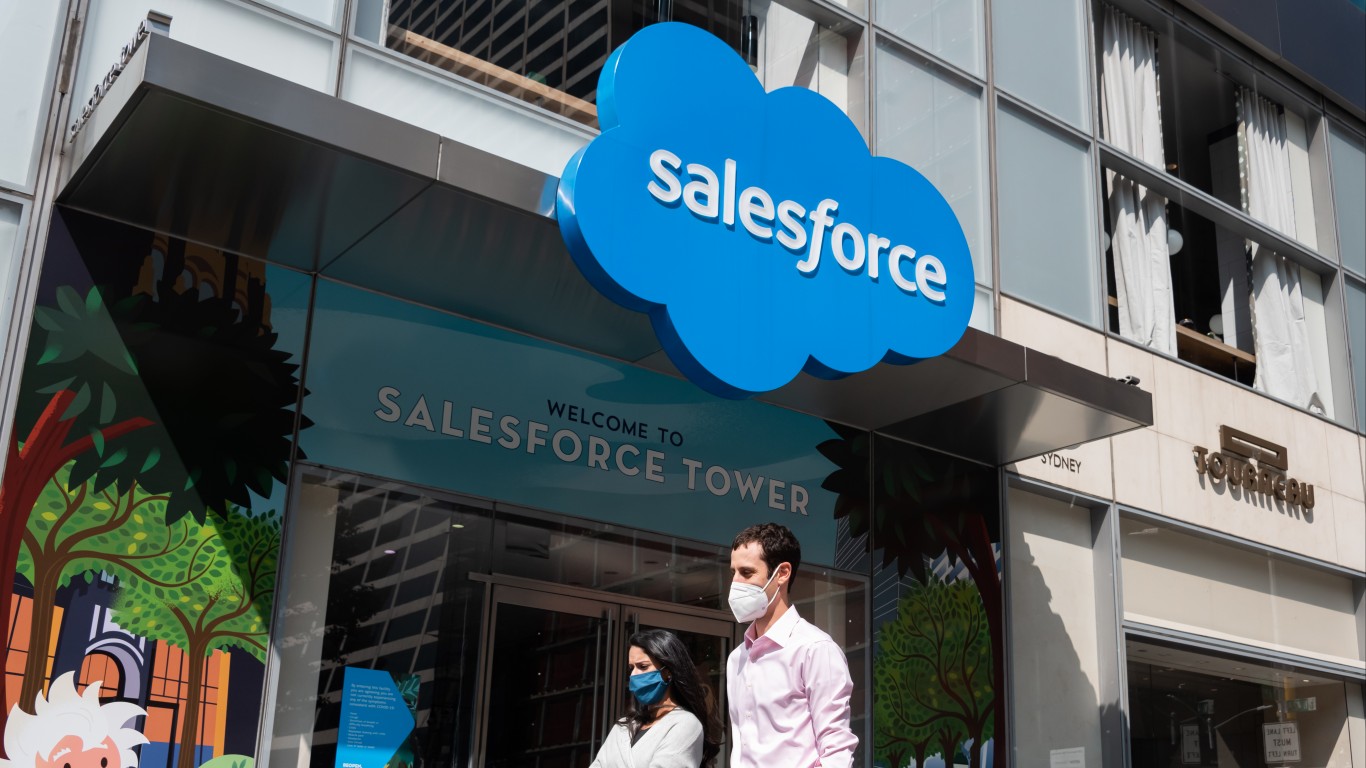
With Salesforce’s (NYSE: CRM | CRM Price Prediction) Q4 FY2026 earnings due February 25, three major Wall Street firms slashed their price targets on the stock Monday morning, raising a pointed question for investors: is it a stock that’s dangerous…

With Salesforce’s (NYSE: CRM | CRM Price Prediction) Q4 FY2026 earnings due February 25, three major Wall Street firms slashed their price targets on the stock Monday morning, raising a pointed question for investors: is it a stock that’s dangerous to overlook, or simply dangerous to own?
Salesforce stock has shed 30.1% year-to-date, sitting at $185.16 as of Friday’s close. The cuts this morning were steep:
- Barclays: To $265 from $338 (still Overweight)
- Evercore ISI: To $260 from $340 (still Outperform)
- Jefferies: To $250 from $375 (still Buy)
Though these three major Wall Street firms cut their price targets significantly, they maintained bullish ratings, suggesting the selloff has been overdone rather than fundamentally justified. Separately, Mizuho lowered its target to $280 from $340, also keeping an Outperform rating, citing broad AI disruption fears across enterprise software. BMO Capital, Citigroup, and UBS also cut targets last week.
The underlying numbers tell a complicated story. Q3 revenue grew 9% year-over-year to $10.26 billion, modest for a mega-cap tech company. But net income surged 36.61% to $2.09 billion, and Agentforce ARR hit nearly $1.4 billion, up 114% year-over-year. The company also returned $4.2 billion to shareholders in Q3 alone.
The tension is real. Top-line growth is incremental, AI competition risks are genuine, and Reddit sentiment has turned bearish with a score of 28 out of 100. But every analyst who cut targets this morning still sees 35% to 50% upside from current levels. Wednesday’s earnings report will be the first real test of whether Agentforce momentum can reignite the growth narrative or confirm the market’s skepticism.
Contact [email protected] for any questions or corrections.
Trey has been an editor and author at 24/7 Wall St. for more than a decade, where he has published thousands of articles analyzing corporate earnings, dividend stocks, short interest, insider buying, private equity, and market trends. His comprehensive coverage spans the full spectrum of financial markets, from blue-chip stalwarts to emerging growth companies.
Beyond 24/7 Wall St., Trey has created and edited financial content for Benzinga and AOL's BloggingStocks, contributing additional hundreds of articles to the investment community.
Trey's editorial expertise extends across multiple publishing environments. He served as production editor at Dearborn Financial Publishing and development editor at Kaplan, where he helped shape financial education materials. Earlier in his career, he worked as a writer-producer at SVE. His freelance editing portfolio includes work for prestigious clients such as Sage Publications, Rand McNally, the Institute for Supply Management, the American Library Association, Eggplant Literary Productions, and Spiegel.
Outside of financial journalism, Trey writes fiction and has been an active member of the writing community for years, moderating workshop sessions at regional conventions.