Jackson Couple Pays Off $154,000 in 23 Months, Ramsey Highlights the Math: ‘You Paid $75,000 a Year and Paid Taxes’
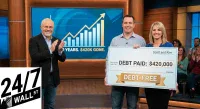
Roman and Jennifer from Jackson, Tennessee, made $148,000 to $154,000 over two years and still eliminated $154,000 in debt in 23 months. That means they directed roughly $6,700 a month toward debt repayment while also paying taxes, buying groceries, and…


Roman and Jennifer from Jackson, Tennessee, earned between $148,000 and $154,000 over two years and still wiped out $154,000 in debt in 23 months. That pace required directing roughly $6,700 every month toward debt while simultaneously covering taxes, groceries, and utilities. Dave Ramsey captured exactly why that is remarkable: “You made $150,000, but you paid off $75,000 a year and paid taxes. And ate food and stuff.”
That single observation contains the most important lesson in personal debt math that most people never fully absorb. Your real budget is whatever survives after taxes, and by the time those deductions clear your paycheck, the dollars available for debt, food, housing, and everything else are far smaller than the figure on your offer letter.
The After-Tax Math Most People Ignore
At a household income of roughly $150,000, a married couple filing jointly faces a federal marginal rate of 22% to 24% on earnings above certain thresholds, plus Social Security and Medicare payroll taxes. Tennessee levies no state income tax on wages, which kept more of each paycheck intact for Roman and Jennifer. Worth noting: Tennessee does carry one of the highest combined sales tax rates in the country, around 9.61%, so the couple still faced a meaningful consumption tax burden that most out-of-state observers tend to overlook.
Even with the wage-tax advantage, a household earning $150,000 gross takes home a substantially smaller figure once federal taxes and FICA deductions are applied. From that reduced take-home pay, Roman and Jennifer redirected roughly $75,000 per year to debt, which represents both a large share of their gross income and an even larger share of their actual after-tax dollars. Whatever remained had to cover housing, food, transportation, and utilities.
The math only works if you treat debt payoff as a fixed, non-negotiable line item and compress every other expense around it. Roman described their approach plainly: “We cut our expenses to the bone.” Jennifer added: “He was DoorDashing and I worked at a tea restaurant.” They also sold furniture. Every dollar freed from spending became a dollar applied directly to the debt stack.
What $154,000 in Debt Actually Costs Over Time
The Jackson couple was carrying one car payment, one credit card, and 11 student loans. That combination is common and expensive. The Federal Reserve raised its benchmark interest rate by 25 basis points on September 16, 2026, bringing the target range to 3.75%–4.00%, the first increase since 2023. Credit card rates bear little relationship to the benchmark in practice, but the hike will push them higher still. According to Federal Reserve data, the average APR on accounts that carry a balance reached 22.15% in the second quarter of 2026, and broad card-database averages sit closer to 25%.
At a blended interest rate of even 7% across all their debt, carrying $154,000 for years rather than paying it off aggressively adds up to tens of thousands of dollars in interest. Credit card balances within that stack, charged at rates several times higher and now set to climb further, compound that cost quickly. The interest clock runs every single month you hold the balance.
Who Can Realistically Replicate This
Pulling off what Roman and Jennifer did requires a household income high enough to generate meaningful surplus after taxes and basic living costs, along with the flexibility to add secondary income streams. Earning between $148,000 and $154,000 placed them well above the national median. According to the Bureau of Economic Analysis, per capita disposable income in the United States was $66,871 in 2025, meaning a dual-income household at that per-person level would have far less margin to work with.
Consider a couple earning $80,000 combined: after federal and payroll taxes and a modest $3,000 a month in housing, food, and transportation, there is almost nothing left to throw aggressively at debt. The Jackson approach works at their income level because the math creates enough surplus to compress. At lower incomes, the same intensity requires either additional income generation, a dramatic reduction in fixed costs such as housing, or both.
The income profile where this strategy becomes viable: a dual-income household with combined gross above $120,000, manageable childcare costs, willingness to take on temporary second jobs, and a debt load that is painful but not so large it would require a decade of effort regardless of intensity.
The Psychological Shift Ramsey Identified
After paying off the debt, Roman said something Ramsey found telling: “We almost don’t even know how to make decisions based on what we want to do. It’s always been what we had to do.” Ramsey replied: “That’s interesting. Using a different part of your brain.”
Years of constrained decision-making leave a mark. Roman and Jennifer now face a genuinely new problem: building a life around choice rather than obligation. That transition is where financial planning shifts from debt elimination to wealth accumulation, and the discipline built during the payoff phase carries directly into building long-term savings. The habits that made 23 months of sacrifice possible are the same habits that build a retirement account.
Running the Numbers on Your Own Situation
The Jackson story works best as a stress test to run against your own numbers, not as a blueprint to copy without adjustment. Start with your actual take-home pay, not your gross salary. Subtract fixed non-negotiable expenses. What remains is your realistic debt payoff ceiling. If that number is small, the levers are income (second jobs, overtime, side income) or fixed costs (housing, car payments, subscriptions).
List every debt with its current balance and interest rate. The gap between a minimum-payment schedule and an aggressive payoff schedule is the real cost of inaction, and with credit card rates near 22% on balances carried month to month, that gap is substantial enough to motivate the kind of intensity Roman and Jennifer sustained for nearly two years.
Ramsey’s observation was a reminder that an income statement is not a cash flow statement. A family that earns $150,000 and still retires $75,000 in debt annually, while covering taxes and living expenses, is doing the arithmetic correctly. Most people never bother to run those numbers at all.
Editor’s note: This article has been updated to reflect the Federal Reserve’s September 16, 2026, rate hike, which brought the federal funds target range to 3.75%–4.00% from the prior 3.50%–3.75%, and to note that the average APR on credit card accounts carrying a balance was 22.15% in Q2 2026 per Federal Reserve data, with the Fed’s rate increase likely to push that figure higher in coming months.
Contact [email protected] for any questions or corrections.
Austin Smith is a financial publisher with over two decades of experience as an investor, analyst, and advisor. He covers stocks, ETFs, Artificial intelligence and personal finance for 24/7 Wall St. Previously, he spent over a decade at The Motley Fool as a senior editor for Fool.com, portfolio advisor for Millionacres, and launched The Ascent to help reader take control of their personal finances.
His work has been featured on Fool.com, NPR, CNBC, USA Today, Yahoo Finance, MSN, AOL, Marketwatch, and many other publications. He is as an advisor to private companies, and co-hosts The AI Investor Podcast with Eric Bleeker.
When not looking for investment opportunities, he can be found skiing, running, or playing soccer with his children. Learn more about Austin's investment approach here.