SoFi’s Wild Ride: $19 Price Target, Hold for Now
Few fintech stocks have whipsawed investors like SoFi Technologies (NASDAQ:SOFI | SOFI Price Prediction) over the past year. After ripping from $10.94 in April 2025 to a 52-week high of $32.73, shares have given back a chunk of those gains.…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.

Few fintech stocks have whipsawed investors like SoFi Technologies (NASDAQ:SOFI | SOFI Price Prediction) over the past year. After ripping from $10.94 in April 2025 to a 52-week high of $32.73, shares have given back a chunk of those gains.
Our 24/7 Wall St. price target for SoFi is $19, implying just 1.26% upside from the current quote. Our recommendation is hold, and our confidence in this base case is high at 90%.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $18.76 |
| 24/7 Wall St. Price Target | $19.00 |
| Upside | 1.26% |
| Recommendation | HOLD |
| Confidence Level | 90% |
A Round Trip Back to Fair Value
SoFi has traveled a remarkable arc. Shares are up 45.65% over the past year but down 28.34% year to date and 17.76% since the Q4 2025 earnings filing on January 30, 2026.
That sell-off came despite a clean print: adjusted EPS of $0.13 versus $0.11 expected and SoFi’s first-ever billion-dollar quarter at $1.025 billion in revenue. Members hit 13.7 million (+35% YoY), and Q4 loan originations reached a record $10.49 billion. Investors balked at the net interest margin compression of 19 basis points and personal loan charge-offs ticking to 2.80%.
The Case for $25+
Bulls have a credible path. Management is guiding 2026 adjusted revenue to $4.655 billion (~30% growth), adjusted EBITDA to $1.6 billion, and adjusted EPS to $0.60, with a medium-term EPS CAGR of 38% to 42%. The Financial Services segment grew 78% YoY, fee revenue jumped 53%, and the Loan Platform Business is running at a $15 billion annualized pace.
CEO Anthony Noto framed the setup directly: “This combination of scale, innovation, and profitability positions SoFi to drive durable, compounding growth.”
Polymarket traders assign a 91.5% probability SoFi beats the upcoming quarterly print. The Wall Street consensus target sits at $23.48. Our bull case projects $24.91 within 12 months if crypto, stablecoin, and Galileo monetization compound.
The Risks Worth Watching
The bear case starts with valuation. A forward P/E near 49x leaves no margin for error. Net income fell 47.8% YoY in Q4, though that decline reflects a prior-year tax benefit rather than operating performance.
Personal loan charge-offs at 2.80% and Technology Platform accounts down 23% YoY on a single client transition are real concerns, even if the platform headcount loss is largely lapped. With a beta of 2.25, any macro wobble hits SoFi harder than peers. Our bear scenario points to $15.95 over 12 months.
Bottom Line
The franchise is genuinely scaling, but the stock is already pricing in flawless execution. The mid-$15s would mark a level where forward P/E becomes more defensible, while a move above $24 without extended membership and Loan Platform momentum in the Q1 print would test the thesis.
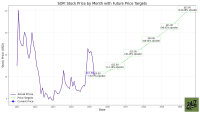
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $19.00 |
| 2027 | $18.41 |
| 2028 | $20.06 |
| 2029 | $20.87 |
| 2030 | $21.84 |
These projections assume SoFi delivers on its 30%+ revenue CAGR through 2028 with gradual multiple compression. Significant upside could emerge if crypto and Galileo scale faster, while a credit cycle break would push prices toward the bear path.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.