After Falling 28% YTD, SoFi Offers Limited Upside to Our Price Prediction
SoFi Technologies (NASDAQ:SOFI | SOFI Price Prediction) has whipsawed investors over the past six months, riding from the low teens to a 52-week high of $32.73 before sliding back to the high teens. With Q1 2026 earnings on deck, our…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.

SoFi Technologies (NASDAQ:SOFI | SOFI Price Prediction) has whipsawed investors over the past six months, riding from the low teens to a 52-week high of $32.73 before sliding back to the high teens. With Q1 2026 earnings on deck, our proprietary model points to a stock that has already done most of the work of finding fair value.
Our 24/7 Wall St. price target for SoFi is $18.97, which sits roughly 2% above the current price of $18.62. The recommendation is hold, with a confidence reading of 90%. In plain English: SoFi looks fairly priced after the recent correction, and the next leg likely waits on Q1 results.

24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $18.59 |
| 24/7 Wall St. Price Target | $18.97 |
| Upside | 2% |
| Signal | HOLD |
| Confidence | 90% |
From $32 to $18: How SoFi Reset This Spring
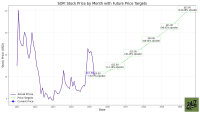
The chart tells the story. SoFi has fallen 28% year-to-date after peaking near $27 last September, yet still sits up 46% over the trailing year and 23% over the past month as buyers stepped in below $16.
The fundamentals behind that volatility are strong. Q4 2025 produced $1.025 billion in revenue, SoFi’s first billion-dollar quarter, with adjusted EPS of $0.13 beating the $0.11 consensus. Members hit 13.7 million, up 35% YoY, and FY 2025 revenue grew 38% to $3.61 billion. The drag has been credit-related: the personal loan charge-off rate ticked up to 3%, and net interest margin compressed 19 bps YoY to 6%.
The Case for $25+
Bulls have a clean thesis. Management guided FY 2026 to $4.65 billion in adjusted revenue, $1.6 billion adjusted EBITDA at a 34% margin, and $0.60 in adjusted EPS. Medium-term EPS CAGR is targeted at 38% to 42% through 2028.
Financial Services revenue grew 78% YoY in Q4, fee-based revenue jumped 53%, and the Loan Platform Business is now running at a $15 billion annualized origination pace.
New crypto, stablecoin, and remittance rails widen the optionality. Wall Street’s average target of $23.48 reflects that view, with 8 buy-side ratings. Our internal bull case puts SoFi at $24.89 within 12 months if execution holds.
What Could Go Wrong
The bear case rests on credit and multiple compression. The personal loan charge-off rate moving from 3% to 3% sequentially deserves attention, asset yields fell 74 bps YoY, and Technology Platform accounts dropped 23% YoY as a large client transitions off.
Bulls would counter that the platform decline is one client-specific, charge-offs remain below 2024 levels, and SoFi is investing through cycle to capture share. Still, at a P/E near 48x and beta of 2.25, any FY 2026 stumble could pull SoFi to our bear case of $15.93.
Holding Through the Earnings Report
The data points to a fairly valued setup here with high conviction. The 24/7 Wall St. price target of $18.97 sits within a percent of where the stock trades, and the 90% confidence reflects how cleanly the data converges.
I would get more constructive on a clean Q1 2026 earnings report that hits the $0.12 adjusted EPS bar with credit metrics stable. I would step back if charge-offs climb above 3% or 2026 guidance gets trimmed. Polymarket traders are nearly split at 48% odds of an earnings beat, which is the right way to think about the setup.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $18.97 |
| 2027 | $19.65 |
| 2028 | $20.35 |
| 2029 | $21.08 |
| 2030 | $21.83 |
These projections extend the model’s base-case 4% annualized return path, which lands SoFi at $22.18 by April 2031. Significant upside or downside could come from credit normalization, Galileo client wins, or interest-rate shifts.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.