History Says This Unstoppable Cash Cow Is the Single Best “Set-It-and-Forget-It” Stock on the Planet
If you are building a portfolio you intend to never touch again, Berkshire Hathaway (NYSE:BRK-B) warrants a central role, because it is engineered to compound capital across decades regardless of who is in the White House, what the Federal Reserve…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
If you are building a portfolio you intend to never touch again, Berkshire Hathaway (NYSE:BRK-B | BRK-B Price Prediction) warrants a central role. The company is engineered to compound capital across decades regardless of who is in the White House, what the Federal Reserve is doing, or which sector is in fashion. Few businesses in history have been built so deliberately around a single principle: survive everything, then buy when others cannot.
Pillar One: A Business Built to Outlast Cycles
Berkshire operates more like a privately run economy than a single stock. Its wholly owned subsidiaries span nearly every corner of the real economy: GEICO, BNSF, Berkshire Hathaway Energy, Duracell, Dairy Queen, Lubrizol, Fruit of the Loom, Helzberg Diamonds, Long & Foster, FlightSafety International, Pampered Chef, Forest River, and NetJets. Two acquisitions completed in 2026 extended that list in meaningful directions. On January 2, Berkshire closed its purchase of OxyChem from Occidental Petroleum for $9.7 billion, adding a top-three U.S. manufacturer of polyvinyl chloride, chlor-alkali chemicals, and calcium chloride with operations across the U.S., Canada, and Latin America. Then on July 24, the company acquired homebuilder Taylor Morrison for $72.50 per share in cash, representing roughly $6.8 billion in equity value and approximately $8.5 billion in enterprise value, planting a flag in residential construction at a moment when the U.S. housing shortage continues to underpin demand.
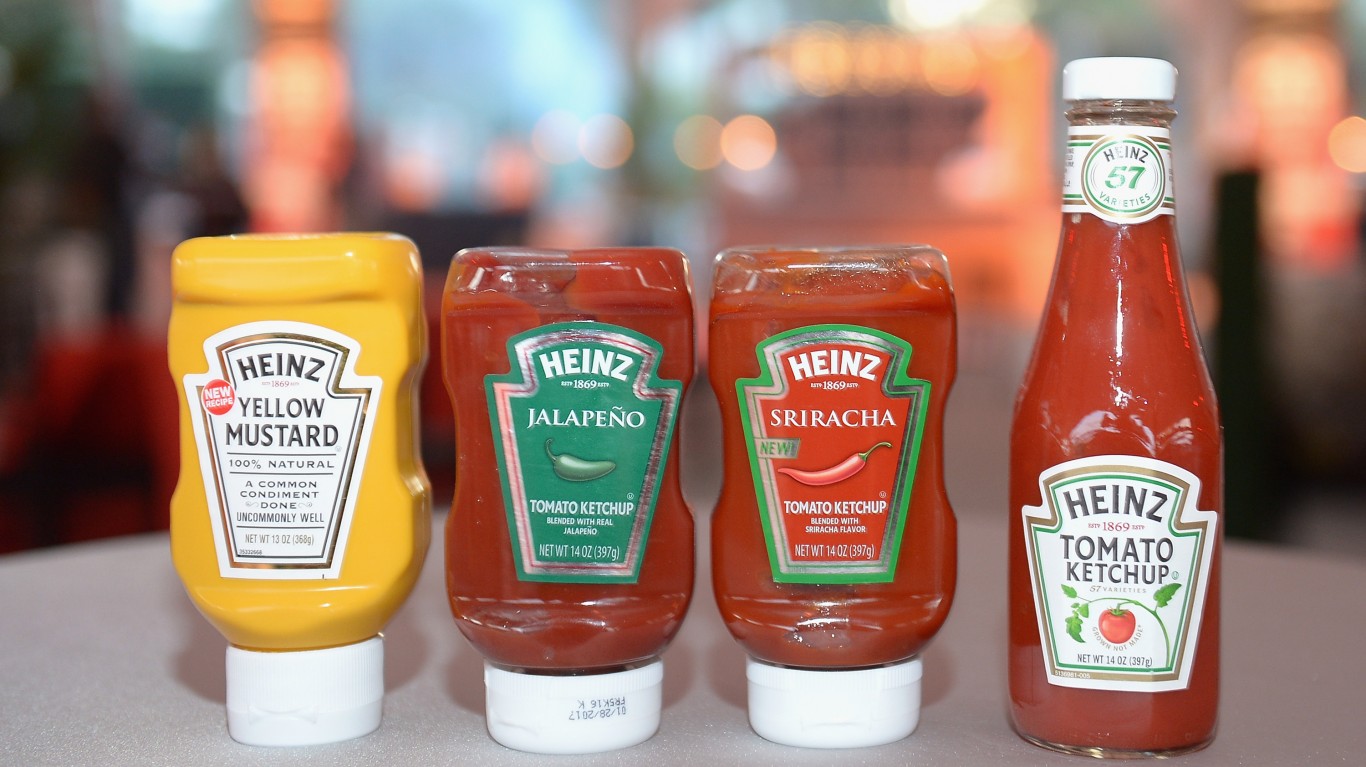
Beyond those wholly owned businesses, Berkshire holds equity-method stakes in Kraft Heinz (approximately 27.5%) and Occidental Petroleum (approximately 28%), along with large publicly traded positions in American Express (approximately 22% of outstanding shares) and Coca-Cola (9.3%). The equity portfolio’s composition shifted noticeably in Q2 2026: Alphabet emerged as Berkshire’s third-largest holding by market value at roughly $36.6 billion, after the conglomerate added approximately $17 billion to its stake during the quarter. The structural bias remains exactly what a long-horizon investor wants, because insurance, railroads, utilities, and basic industrials are primed to benefit from a fundamental reality: the U.S. and global economies spend far more time expanding than contracting. BEA data confirms the pattern, with only two negative-GDP quarters across the last 20.
Pillar Two: Compounding Without a Dividend Check
Berkshire pays no dividend, and that is deliberate. Rather than distributing income, management reinvests every dollar at high rates of return and runs a disciplined capital return program through buybacks. Operating cash flow has been substantial and durable: $30.6 billion in 2024, $45.97 billion in 2025. In Q2 2026, operating earnings climbed 16% year over year to $12.98 billion, with broad strength across BNSF (up 6% to $1.56 billion), Berkshire Hathaway Energy (up 27% to $891 million), and the manufacturing, service and retailing segment (up 24% to $4.47 billion). Insurance was the one soft spot, with underwriting earnings falling 13% to $1.73 billion as market conditions tightened.
The capital allocation story under Greg Abel has evolved quickly. After 14 consecutive quarters as a net seller of equities, Berkshire reversed course in Q2 2026, accumulating nearly $20 billion in net equity purchases, with the Alphabet stake expansion accounting for a large share of that activity. Share repurchases accelerated sharply to $4.5 billion in the second quarter, up from $235 million in Q1. Every buyback quietly enlarges each remaining shareholder’s claim on the entire conglomerate.
The balance sheet’s scale reinforces all of it. Shareholders’ equity stood at $750.2 billion as of June 30, 2026. The company held $365.5 billion in cash, cash equivalents, and short-term U.S. Treasury bills at quarter-end, down from a record $397.4 billion at the close of Q1 after Abel put capital to work. That stockpile is not simply idle. It is strategic patience kept liquid and ready to deploy when other buyers are forced to sell.
Pillar Three: Designed to Survive What Kills Other Stocks
The balance sheet is the moat beneath the moat. Debt-to-equity sits at 0.19, interest coverage at 11.6 times, and beta at 0.617, meaning the stock moves materially less than the broad market by design. Even in the 2022 mark-to-market storm that produced a $22.06 billion net loss, operating cash generation held at $37.2 billion. The company’s insurance float amplifies that advantage further: at the end of Q2 2026, float stood at $177.5 billion, up $1.1 billion from year-end 2025 and up from $171 billion a year earlier. Because overall underwriting remained profitable in recent quarters, the effective cost of that float is negative, meaning Berkshire gets paid to hold, and deploy, other people’s money at a time when capital is most expensive everywhere else.
When It Lags, and Why That Is Fine
Berkshire will underperform during speculative bull markets driven by narrow technology rallies. Berkshire shares gained roughly 3% year to date in 2026 against an S&P 500 advance of about 13% over the same span. Over a full decade, though, the gap has essentially closed: BRK-B has returned approximately 257% against the S&P 500’s roughly 251%, with materially less drawdown risk along the way. The conservatism that causes short-term lag is the same conservatism that leaves Berkshire standing, and buying, when the cycle turns.
One area of portfolio evolution under Abel deserves particular attention. In January 2026, Berkshire registered its entire 27.5% stake in Kraft Heinz with the SEC, preserving optionality for a potential divestiture. Kraft Heinz shares have fallen roughly 70% since the 2015 merger, weighed down by shifting consumer tastes, rising costs, and sluggish brand growth. When Kraft Heinz paused its planned split into two companies in February 2026 and committed $600 million to a turnaround effort instead, Abel signaled no immediate plans to alter the stake. The position remains on the books as of the Q2 2026 13F filing, and the SEC registration simply keeps options open rather than mandating a sale. How Abel ultimately resolves this legacy holding will be one of the more closely watched capital allocation decisions of his tenure.
With a trailing P/E of roughly 15 and diluted EPS of $33.58, the valuation remains rational relative to the quality and breadth of the underlying businesses. For investors willing to think in decades rather than quarters, the structure continues to reward patience.
Editor’s note: This pass corrects Berkshire’s end-of-Q2-2026 cash and Treasury position to $365.5 billion (from $359 billion stated previously) and updates shareholders’ equity to $750.2 billion as of June 30, 2026. It adds the Alphabet stake expansion, which grew to roughly $36.6 billion by quarter-end to become the portfolio’s third-largest equity holding, and incorporates the Taylor Morrison enterprise value of $8.5 billion alongside the $6.8 billion equity price. The Q2 insurance underwriting decline of 13% has also been added to give a fuller picture of segment-level earnings.
Contact [email protected] for any questions or corrections.
Alex Sirois is a financial writer with experience spanning both retail and institutional investing. He has written for InvestorPlace and held roles at BNY Mellon and Bernstein, giving him a perspective that bridges Main Street portfolios and Wall Street analysis.
Alex holds an MBA from George Washington University and has built his career across multiple industries, including e-commerce, education, and translation — a breadth of experience that informs how he breaks down complex financial topics for everyday investors. His writing is conversational, actionable, and grounded in long-term, buy-and-hold investing principles.
At 247 Wall St., Alex focuses on delivering analysis that is both accessible and useful, with a clear emphasis on helping readers make more informed decisions with their money.