Famous Short-Seller Says We’re In an AI Energy Bubble. Will Bloom Energy Prove Him Wrong?
The AI infrastructure boom has created a new class of market winners. Chipmakers, data center operators, and power suppliers have all benefited as hyperscalers race to build the computing capacity needed to train and run artificial intelligence models. Yet every…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
The AI infrastructure boom has created a new class of market winners. Chipmakers, data center operators, and power suppliers have all benefited as hyperscalers race to build the computing capacity needed to train and run artificial intelligence models. Yet every boom attracts skeptics.
This time, famed short-seller Jim Chanos is challenging one of Wall Street’s hottest investment themes: the idea that alternative energy companies will enjoy years of pricing power from an AI-driven electricity shortage. His argument deserves attention. But Bloom Energy (NYSE:BE) may be one company that doesn’t fit neatly into his bearish framework.
Chanos Says This Is a Bottleneck, Not a Shortage
Chanos argues investors are confusing a temporary infrastructure problem with a permanent energy shortage.
His thesis is straightforward. The U.S. has enough generation capacity to meet demand over time, but permitting delays, transmission constraints, and turbine shortages have created temporary grid bottlenecks. If AI demand remains as large as forecasts suggest, economic incentives will force regulators and utilities to accelerate solutions.
There is evidence supporting that view. The Federal Energy Regulatory Commission recently approved measures aimed at speeding up data center grid connections. If interconnection queues begin moving faster, some of today’s scarcity premium could disappear. Investors paying 50x, 60x, or 70x earnings for energy-related stocks may discover they were pricing in conditions that don’t last forever.
That said, Chanos is talking about a world two or three years from now. In the AI era, that is practically an eternity.
Bloom Energy Benefits From Today’s Crisis
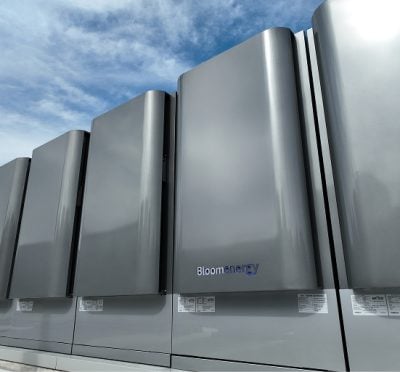
Bloom Energy’s opportunity isn’t dependent on what the grid looks like in 2029. The company’s solid oxide fuel cells provide behind-the-meter power generation directly at data centers. Instead of waiting years for utility connections, operators can deploy Bloom’s Energy servers and begin generating electricity on-site.
Here’s what makes the value proposition compelling:
| Bloom Energy Advantage | Benefit to Data Centers |
| 90-120 day deployment | Accelerates time-to-power versus 3-5 year grid connections |
| Instant response capability | Handles AI workload spikes without large battery systems |
| Quiet, low-emission operation | Faces less community opposition than diesel generators |
| 99.999% reliability | Protects against blackouts and grid instability |
| 30% federal tax credit eligibility | Reduces project costs under Inflation Reduction Act incentives |
Those advantages are key because many AI projects cannot afford to wait years for electricity. BloombergNEF projects data center power demand could exceed 106 gigawatts by 2035. Whether the problem is a shortage or a bottleneck, operators still need power today.
Bloom’s solution effectively monetizes that urgency and the market has noticed. Bloom Energy stock has climbed roughly 267% year to date and more than 1,300% over the past 12 months as investors embraced the company’s role in solving data center power constraints. The company has also reported rapid growth tied to hyperscaler demand and expects record revenue in 2026.
The Risks Investors Can’t Ignore
Granted, Chanos may be right about one thing: valuation. Bloom’s stock performance has dramatically outpaced the growth of its underlying business. Several analysts have warned that expectations now assume years of flawless execution. Some valuation metrics have expanded to levels rarely seen outside high-growth software companies despite Bloom operating in a capital-intensive energy industry.
Investors should also watch several key risks:
- Customer concentration remains elevated.
- AI infrastructure spending could slow.
- Insider selling has increased in recent months.
- Future multiple compression could pressure shares even if revenue continues growing.
In short, Bloom Energy may be a great business but still become an expensive stock.
Key Takeaway
Chanos could ultimately be correct that today’s AI energy scarcity is temporary. If grid bottlenecks ease over the next few years, many alternative energy stocks trading at premium valuations could face a painful reset.
Bloom Energy, however, occupies a unique position. The company isn’t merely betting on future power demand. It is helping data centers solve an immediate problem by bypassing grid delays altogether.
For sharp investors, the debate isn’t whether Chanos is right or wrong. It’s whether Bloom can grow fast enough over the next several years to justify a stock that has already risen more than 1,300% in a year. Ultimately, Bloom’s business model appears stronger than the broad alt-energy sector Chanos is criticizing, but the valuation leaves little room for mistakes.
Contact [email protected] for any questions or corrections.
After two decades of patrolling the dark corners of suburbia as a police officer, Rich Duprey hung up his badge and gun to begin writing full time about stocks and investing. For the past 20 years, he’s been cruising the markets looking for companies to lock up as long-term holdings in a portfolio while writing extensively on the broad sectors of consumer goods, technology, and industrials. Because his experience isn’t from the typical financial analyst track, Rich is able to break down complex topics into understandable and useful action points for the average investor. His writings have appeared on The Motley Fool, InvestorPlace, Yahoo! Finance, Money Morning, and, of course, 24/7 Wall St. He has been featured in both U.S. and international publications, including MarketWatch, Financial Times, Forbes, Fast Company, and USA Today.