Prediction: Palantir Will End The Year at This Price

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Our Palantir (NASDAQ:PLTR | PLTR Price Prediction) call is straightforward heading into the back half of 2026: after a brutal drawdown, the stock has room to run, but not as much as the loudest bulls think.
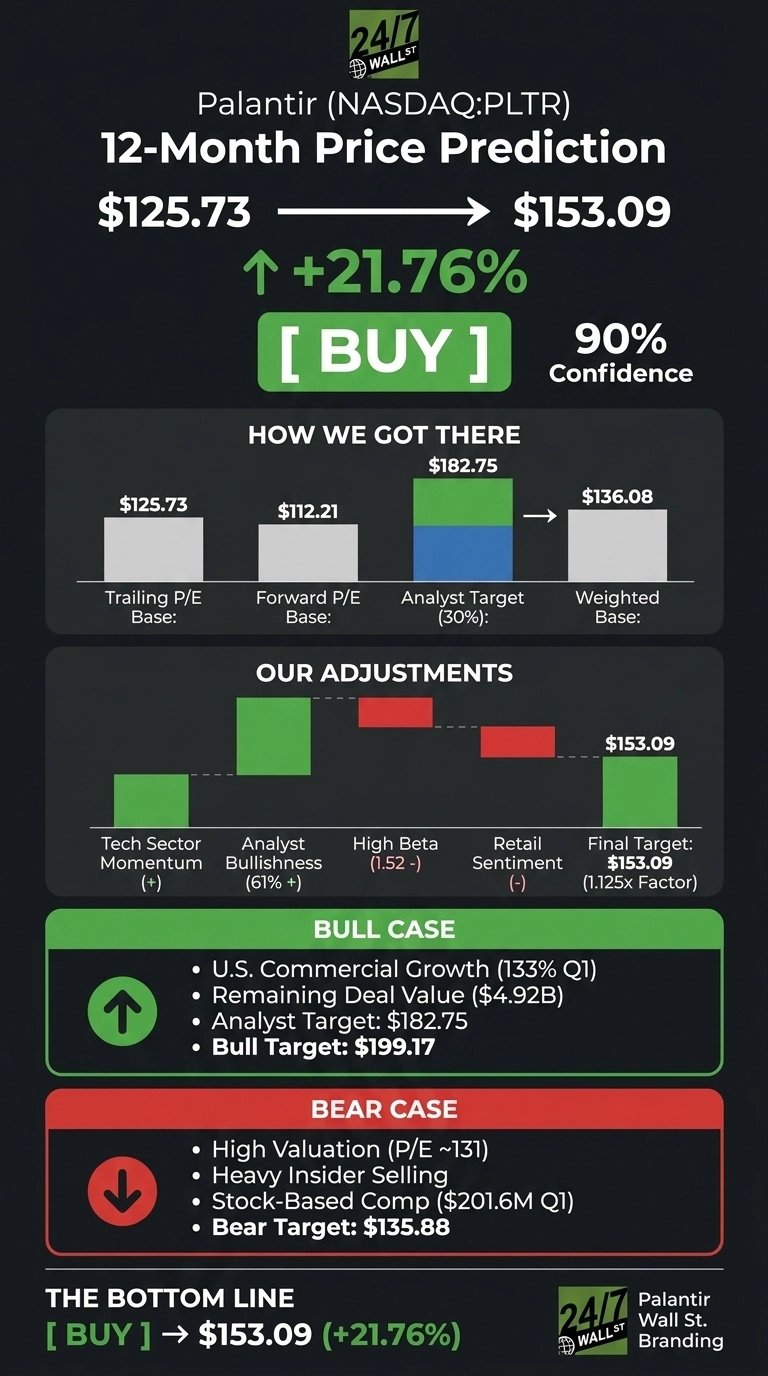
The 24/7 Wall St. price target for Palantir is $153.09, implying roughly 21.76% upside from the $125.73 close on July 1. Our recommendation is buy, with a confidence level of 90%. In plain terms: high conviction that Palantir grinds back toward the low $150s by year-end, driven by fundamentals rather than a return to speculative frenzy.
| Metric | Value |
|---|---|
| Current Price | $125.73 |
| 24/7 Wall St. Price Target | $153.09 |
| Upside | 21.76% |
| Recommendation | BUY |
| Confidence Level | 90% |
A Painful First Half Sets Up the Setup
Palantir enters July down 29.27% year to date, with a 21.74% slide over the past month alone. Yet the operating story has never been stronger.
Q1 2026 revenue hit $1.63 billion, up 84.71% year over year, with adjusted EPS of $0.33 topping consensus by 18.07%. GAAP operating income of $754 million produced a 46% margin, and management raised FY 2026 revenue guidance to $7.650 to $7.662 billion, roughly 71% growth.
The recent NVIDIA sovereign AI partnership and Cathie Wood’s continued accumulation have helped the stock claw back 10.78% in the last week.

Why Bulls See a Breakout Ahead
The bull case rests on U.S. commercial acceleration. That segment grew 133% in Q1 2026, and remaining deal value swelled to $4.92 billion, up 112%. Bank of America maintains a Buy with a $181 target, and the sell-side consensus sits at $182.75.
Our own bull-case model projects $199.17 over the next twelve months if AIP adoption compounds and margins hold near 60%. Morningstar’s recent 4-star upgrade and Ark’s fresh buying add institutional validation.

What Could Go Wrong
The bear case starts with valuation. A P/E of 131 leaves zero room for a guidance miss. Insider selling has been heavy: CEO Alex Karp disposed of 397,744 Class A shares on May 20, with President Shyam Sankar and Director Stephen Cohen selling large blocks the same day.
Bulls will counter that these were largely planned 10b5-1 sales tied to option exercises and RSU vesting. Our bear-case model points to $135.88 if multiple compression accelerates. Stock-based compensation of $201.6 million in Q1 alone also dilutes shareholders meaningfully.

Palantir Price Prediction 2026-2030
The 24/7 Wall St. price target of $153.09 reflects a buy at 90% confidence. The tipping factor is the guidance raise: management added 10 points of growth in a single quarter, a signal earned by execution.
I’d be a buyer here if Q2 2026 results confirm the U.S. commercial acceleration and adjusted operating margin holds above 55%. I’d stay on the sidelines if the next report shows any deceleration in U.S. commercial TCV or a slip in Rule of 40 back below 120%.
Looking further out, here is where our model projects Palantir could trade, assuming current growth trajectories moderate gradually and multiples compress toward large-cap software norms.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $153.09 |
| 2027 | $175.00 |
| 2028 | $195.00 |
| 2029 | $212.00 |
| 2030 | $227.67 |
These projections assume Palantir continues converting AIP momentum into commercial revenue and government contracts. Meaningful upside or downside could come from sovereign AI wins, a slowdown in defense spending, or a broader repricing of premium-multiple software names.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.