Price Prediction: ON Semiconductor’s Rally May Be Far From Over
ON Semiconductor has already staged one of the semiconductor sector's wildest comebacks of 2026, but the bigger question is whether the forces driving it are just getting started or already priced in.


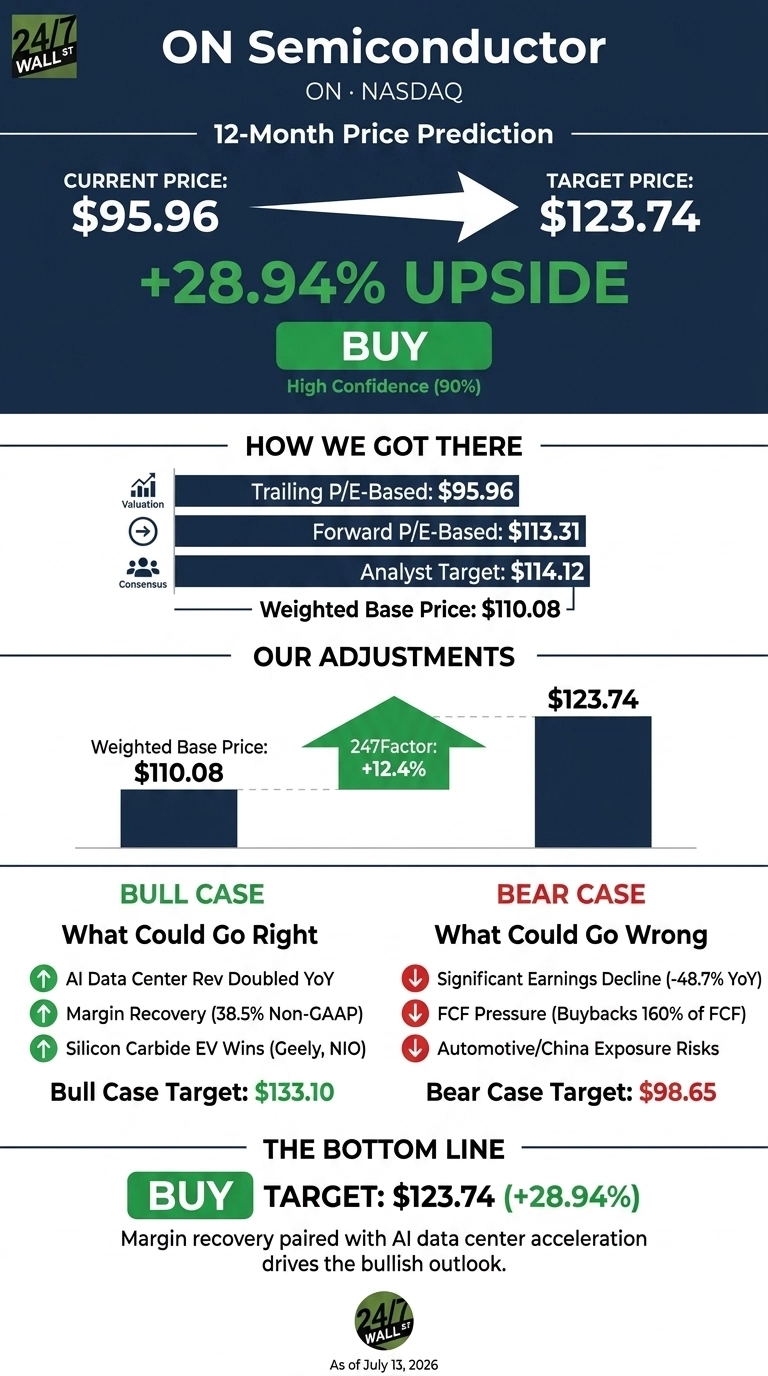
ON Semiconductor’s (NASDAQ:ON | ON Price Prediction) rebound has been one of the semiconductor sector’s more dramatic stories of 2026, and our proprietary model still sees room to run. The stock trades at $95.96 after a 77.21% year-to-date rally that cooled from a $134.92 52-week high.
Our 24/7 Wall St. price target for ON Semiconductor is $123.74, implying 28.94% upside over the next 12 months. The model’s rating is buy, with high confidence at 90%.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $95.96 |
| 24/7 Wall St. Price Target | $123.74 |
| Upside | 28.94% |
| Recommendation | BUY |
| Confidence Level | 90% |
From Cyclical Trough to AI Data Center Breakout
ON has whipsawed investors. Shares sat at $48.11 last September and ripped to $125.90 by mid-June before pulling back 12.9% over the past month.
Q1 2026 confirmed the inflection: revenue of $1.513 billion topped expectations by 1.72%, non-GAAP EPS of $0.64 exceeded expectations by 4.03%, and non-GAAP gross margin recovered to 38.5% from a depressed 20.3% a year earlier.
CEO Hassane El-Khoury said the business has “moved beyond the cyclical trough on a path to recovery”, with AI data center revenue more than doubling year over year.
Why Bulls See a Breakout Above $133
The bull thesis rests on the AI data center curve and the silicon carbide EV cycle. Q1 AI data center revenue more than doubled YoY and grew more than 30% sequentially, while Power Solutions climbed 14% to $736.6 million.
EliteSiC design wins with Geely, NIO, and Xiaomi position ON for the 900V EV architecture shift, and PineBridge estimates data center equipment demand growing around 25% annually for the next four to five years. Under our bull case, ON reaches $133.10 in 12 months, a 38.7% total return.

What Could Go Wrong
The bear case starts with valuation. ON’s trailing P/E of 71 and forward multiple of 31 leave no cushion. Free cash flow fell 52.23% YoY in Q1, yet ON spent $345.7 million on buybacks, roughly 160% of free cash flow.
Barclays initiated with equal-weight and a $75 target, flagging automotive and China exposure. Bulls counter that the $329.3 million restructuring charge is non-recurring and non-GAAP margins already run near 38.5%. Our bear case still points to $98.65, roughly flat with today’s price.

How ON Compares to NXPI and TXN
NXP Semiconductors (NASDAQ:NXPI) is the cleanest automotive-analog comp. NXPI trades at a forward P/E of 20 with a 27.7% operating margin and 12.2% revenue growth. ON’s forward multiple of 31 looks rich against that, but ON’s AI data center exposure is scaling faster.
Texas Instruments (NASDAQ:TXN) sets the industrial-analog benchmark. TXN’s forward P/E of 41 and operating margin of 37.8% show what mature scale looks like. ON sits between the two on multiples, which makes our $123.74 target look reasonable rather than aggressive.
| Company | Forward P/E | Operating Margin |
|---|---|---|
| ON Semiconductor | 31 | 18.2% |
| NXP Semiconductors | 20 | 27.7% |
| Texas Instruments | 41 | 37.8% |
Verdict: Model Rates ON a Buy
The 24/7 Wall St. price target for ON Semiconductor is $123.74, a buy with 90% model confidence. The tipping factor is margin recovery paired with AI data center acceleration. The bullish setup holds if Q2 delivers within the $0.65 to $0.77 EPS guide. The thesis weakens if free cash flow keeps deteriorating while buybacks continue at 160% of FCF.

| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $123.74 |
| 2027 | $129.27 |
| 2028 | $155.71 |
| 2029 | $184.89 |
| 2030 | $199.89 |
These projections assume ON keeps executing on silicon carbide EV design wins and AI data center power. Meaningful upside or downside could come from automotive cycle turns or China policy shifts.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.