I Can’t Stop Buying Microsoft Because It’s Turning This AI Bottleneck Into a Moat
Microsoft is down big, capex is exploding, and critics are calling AI infrastructure the fastest-depreciating asset in tech history. So why does every dip feel like an invitation to buy more?

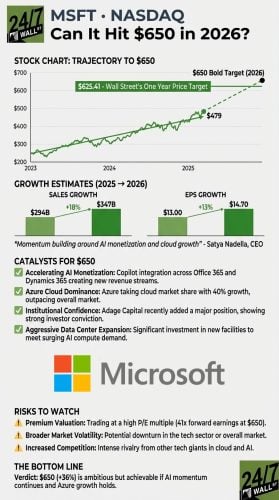
I keep buying Microsoft because it is the only hyperscaler I trust to own both ends of the AI supply chain: the software everyone already pays for, and the electrons that will decide who actually gets to run the models. That combination is why my finger keeps hitting the buy button, and it is why the recent drawdown feels like a gift rather than a warning.
Here is the setup. Microsoft (NASDAQ:MSFT | MSFT Price Prediction) is down 17.39% year to date and 21.39% over the past year, yet the business underneath it just posted its fourth consecutive EPS beat with $4.27 against a $4.07 estimate. Revenue climbed 18.3% year over year to $82.89 billion. The market is punishing capex. I am accumulating.
The Three Data Points That Keep Me Buying
First, the demand signal. Commercial remaining performance obligations reached $627 billion, up 99%. That is contracted, signed, non-cancellable future revenue that nearly doubled in a year. Azure grew 40%, and the AI business alone crossed a $37 billion annual run rate, up 123% year over year. Satya Nadella framed it plainly on the call: “Our AI business surpassed an annual revenue run rate of $37 billion, up 123% year-over-year.”
Second, the quality of the compounding. Return on equity sits at 33.28%, operating margin at 45.62%, gross margin at 68.82%. Debt to equity is 0.176 and interest coverage runs 53.89x. This is a fortress funding a build-out. Shareholders got $12.7 billion returned in a single quarter, up 32% year over year.
Third, and this is the part that turns a good business into a moat: energy. By aggressively funding nuclear restarts, SMRs, and grid-permitting AI, Microsoft turns energy from an external existential risk into a proprietary moat, ensuring its data centers stay powered while turning the energy transition into a software-driven profit center. The LBNL projection has data centers consuming between 6.7% and 12% of U.S. electricity by 2028. Power is the bottleneck now. Microsoft is buying its way to the front of that line.
Why Not Amazon, Alphabet, or NVIDIA
Amazon and Alphabet run capable clouds. Neither owns a roughly 27% stake in OpenAI worth about $135 billion, with IP rights extended through 2032 and a $250 billion incremental Azure services commitment from the counterparty. That is a structural revenue lock the other hyperscalers cannot replicate by writing a check. NVIDIA is the pick-and-shovel play, and I own picks and shovels elsewhere. I would rather own the landlord collecting the rent under a contracted backlog than the supplier selling into a replacement cycle.
The Real Risk
Capex is the real concern. It hit $30.88 billion in a single quarter, up 84.39% year over year. A widely shared r/investing post argues AI infrastructure depreciates faster than railroads or fiber, with chips obsolete in about two years, and it landed hard because it is partly true. My answer: the $627 billion RPO is contracted revenue against those assets. If the backlog stops growing, I will reassess. It is still doubling.
Why I Keep Buying From Here
Over ten years, Microsoft returned 695.26%. Long-term compounders tend to reward holders who look past single-quarter noise. I keep buying Microsoft because it is quietly building the one thing the AI era cannot manufacture on demand: guaranteed power under a signed contract.
Contact [email protected] for any questions or corrections.
Alex Sirois is a financial writer with experience spanning both retail and institutional investing. He has written for InvestorPlace and held roles at BNY Mellon and Bernstein, giving him a perspective that bridges Main Street portfolios and Wall Street analysis.
Alex holds an MBA from George Washington University and has built his career across multiple industries, including e-commerce, education, and translation — a breadth of experience that informs how he breaks down complex financial topics for everyday investors. His writing is conversational, actionable, and grounded in long-term, buy-and-hold investing principles.
At 247 Wall St., Alex focuses on delivering analysis that is both accessible and useful, with a clear emphasis on helping readers make more informed decisions with their money.