1 Reason Wall Street Is Obsessed With This Tech Stock
Marvell Technology just dropped nearly 21% in a month, and one analyst with skin in the game is treating that selloff as a buying opportunity. The reason comes down to a single business segment that could make every other AI…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
I keep hitting the buy button on Marvell Technology (NASDAQ:MRVL | MRVL Price Prediction), and the pullback from the July high has only made me more aggressive. What pulls me back is simple: this is the picks-and-shovels supplier for the custom silicon and optical plumbing that every hyperscaler needs to make AI actually work at scale.
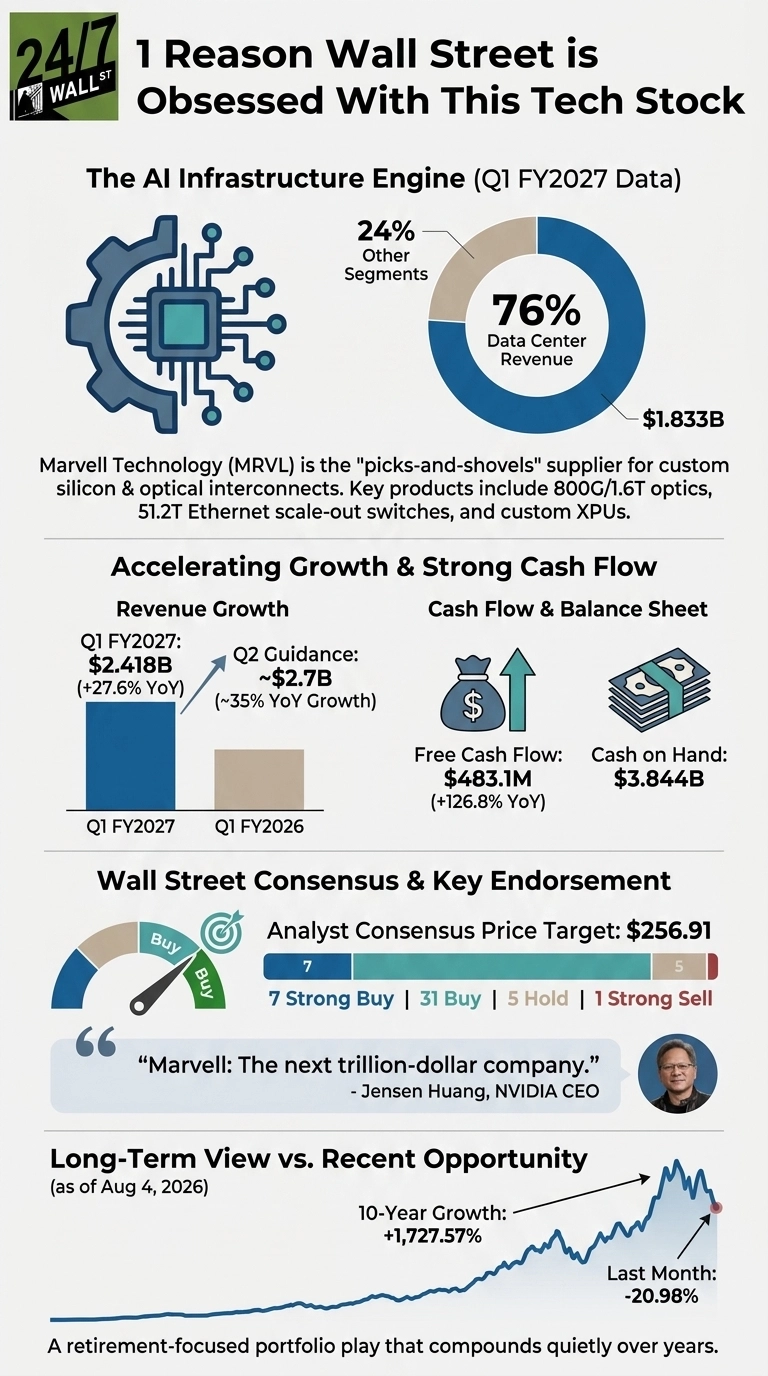
Marvell sells the 800G and 1.6T optics, the 51.2T Ethernet scale-out switches, and the custom XPU designs that sit inside data centers I will never visit but whose economics I want to own for the next decade.
The receipts back the story. Q1 FY2027 revenue came in at $2.418 billion, up 27.6% year over year, with the Data Center segment doing $1.833 billion, or 76% of revenue.
Management guided Q2 to $2.7 billion at the midpoint, implying roughly 35% year-over-year growth, and CEO Matt Murphy said plainly, “We expect revenue growth to continue accelerating each quarter throughout fiscal 2027.” That is a company riding the wave with visibility into accelerating growth.
Second, the cash flow tells the truth. Q1 free cash flow was $483.1 million, up 126.8% year over year, and cash on the balance sheet sits at $3.844 billion. Marvell repurchased $2.0401 billion of stock in FY2026 and another $200 million in Q1. For a retirement-focused portfolio, that combination of growth and self-funded buybacks is what compounds quietly over years.
Third, the Street is aligned with what I am seeing. The consensus analyst target sits at $256.91, with 7 Strong Buy, 31 Buy, 5 Hold and 1 Strong Sell ratings. NVIDIA CEO Jensen Huang called Marvell “the next trillion-dollar company“. The call only needs to be directionally correct; what matters is that the AI infrastructure spending it implies keeps flowing.
Why Marvell Instead of the Obvious Names
The reflex pick is NVIDIA (NASDAQ:NVDA), and I own it too. But NVIDIA sells merchant GPUs to everyone at merchant pricing. Marvell designs the custom ASICs that hyperscalers use specifically to escape merchant GPU economics. Both benefit. Marvell is the smaller, more concentrated bet on that shift.
Broadcom (NASDAQ:AVGO) plays the same custom-silicon game, but the AI ASIC business is diluted inside a much larger software and networking conglomerate. And Advanced Micro Devices (NASDAQ:AMD) is a GPU story chasing NVIDIA. I want the interconnect story, because every accelerator anyone builds needs to talk to every other accelerator.

The Risk I Cannot Wave Away
Customer concentration is real. Data center is 76% of revenue, and a handful of hyperscalers drive most of it. If one of them decides to vertically integrate a design Marvell currently supplies, a quarter can turn ugly fast. The stock is already down 20.98% over the last month.
I keep buying anyway because the bookings commentary from Murphy pointed to “exceptional AI-related bookings” and a raised outlook for both fiscal 2027 and 2028. Design wins that take years to displace are the moat.

Over ten years, MRVL is up 1,727.57%. I bought the recent drawdown, I will buy the next one, and I will keep buying every quarter the data center number grows faster than the total.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.