I’m Hitting Buy On $20,000 of ServiceNow Stock Despite The Melt Down | NOW Stock
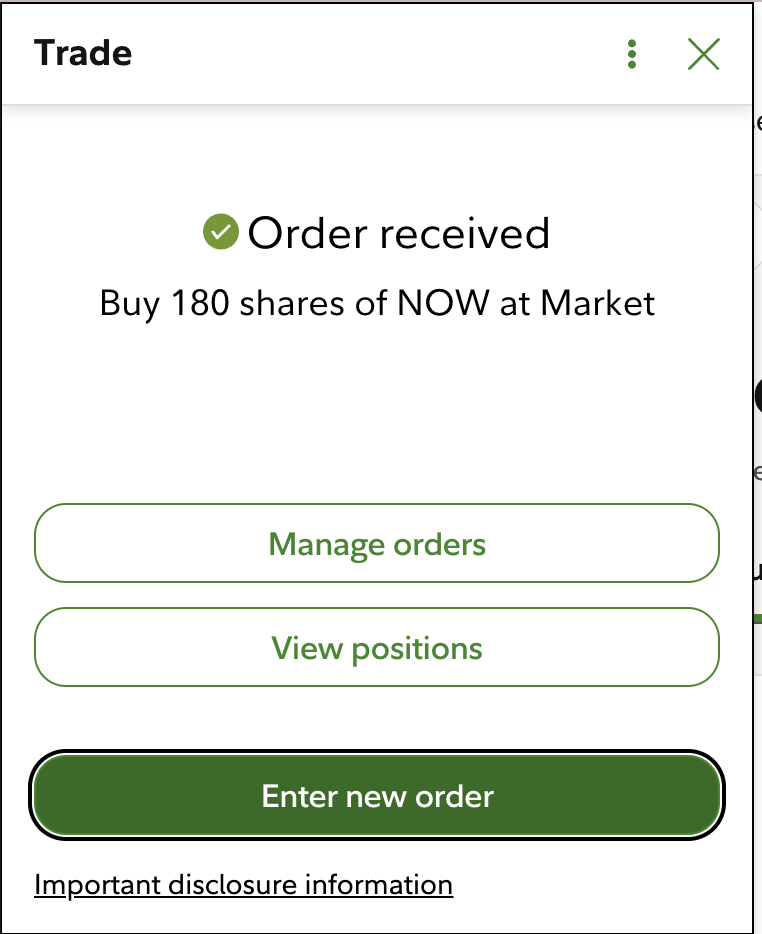
ServiceNow stock has been cut nearly in half while its rivals panic over AI disruption, and one investor just put $20,000 on the line betting the market has it completely wrong.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.

I’ve been co-hosting The AI Investor Podcast with Eric Bleeker since 2024, and worked with him as an investor for far longer. He’s one of the best technology investors today, so when he issues a buy alert it’s worth paying attention
He recently announced a $20,000 buy of ServiceNow (NYSE: NOW) stock, and after doing my own due diligence through AlphaSpace, Yahoo Finance’s research platform, I’m making the same decision. The stock has been cut in half while the underlying business has become more profitable than ever. At today’s price, it’s too hard to ignore. The stock has been cut in half while the underlying business has become more profitable than ever. At today’s price, it’s too hard to ignore.
SaaS Takes A Beating
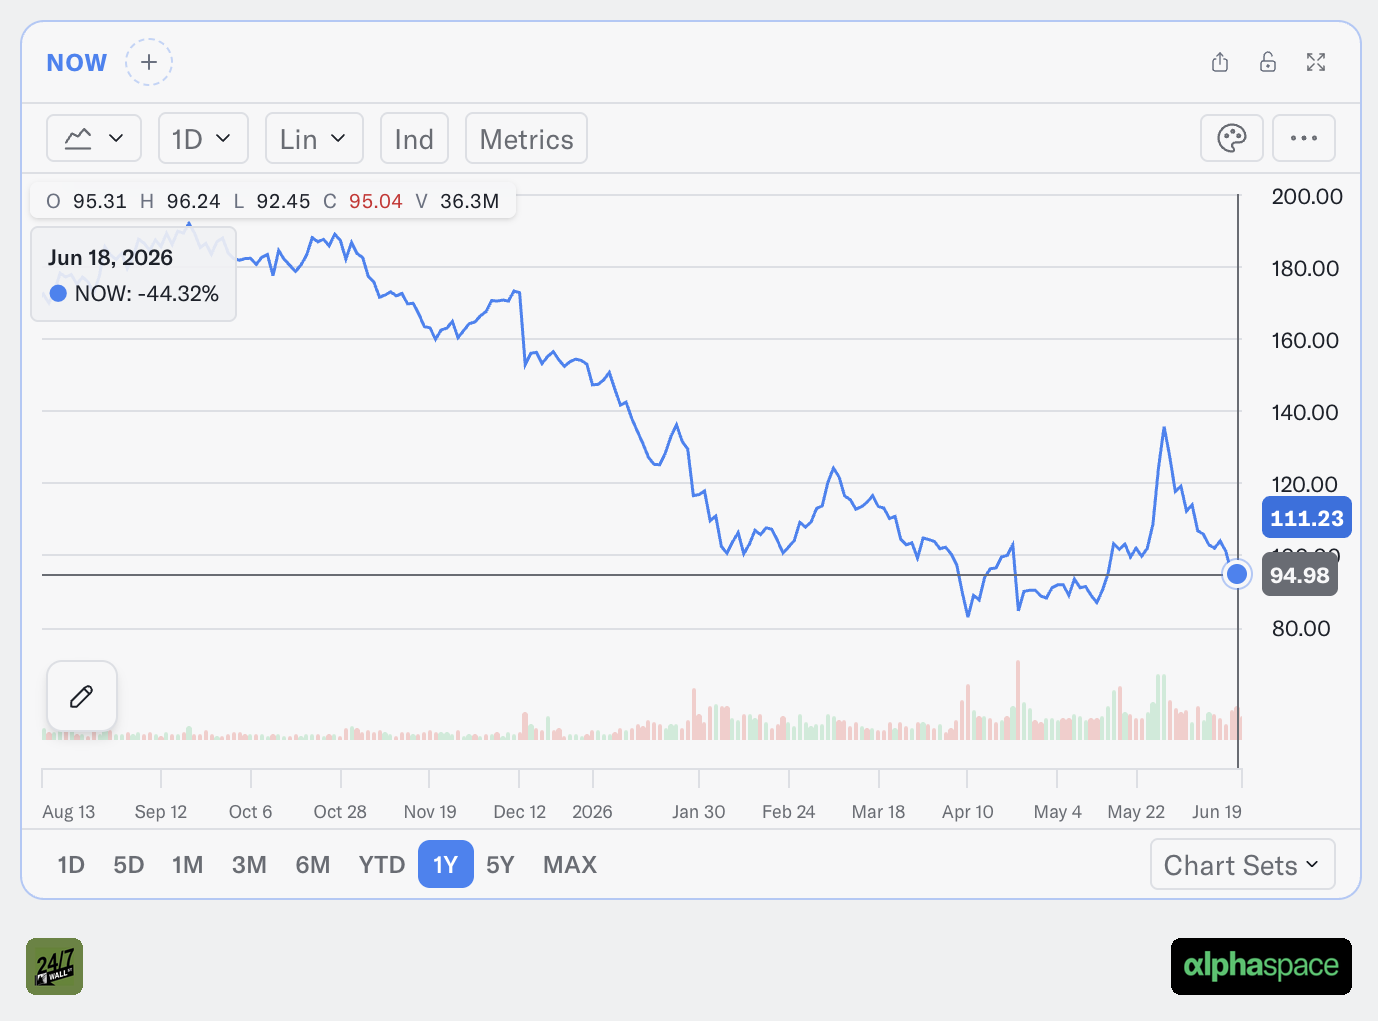
NOW is down over 40% over the last year and 27% year to date. Reddit commenters have labeled the summer sell-off the ‘SaaS meltdown’, others have called it ‘The SaaSpocalypse”. The fear is rooted in the idea that after a decade of printing money at eye watering margins, AI will eat enterprise SaaS revenue growth. There is some truth to this. Coding tools from OpenAI and Anthropic make it easier than ever for companies to build their own custom solutions to previously complex problems. Companies like Salesforce (NYSE: CRM), ServiceNow, and Atlassian (Nasdaq: TEAM) have been put in the line of fire.
But in ServiceNow’s Case, the rumors of their demise have been greatly exaggerated.
The Market’s Blind Spot
The market is partially correct and are pricing in a fading growth story, but they’re also underpricing the developing profit and valuation story. As you can see in AlphaSpace’s dashboard, revenue growth may be slowing but it’s still blisteringly fast. Meanwhile, EBITDA and Free Cash Flow are hitting the accelerator, outpacing revenue growth since 2025.
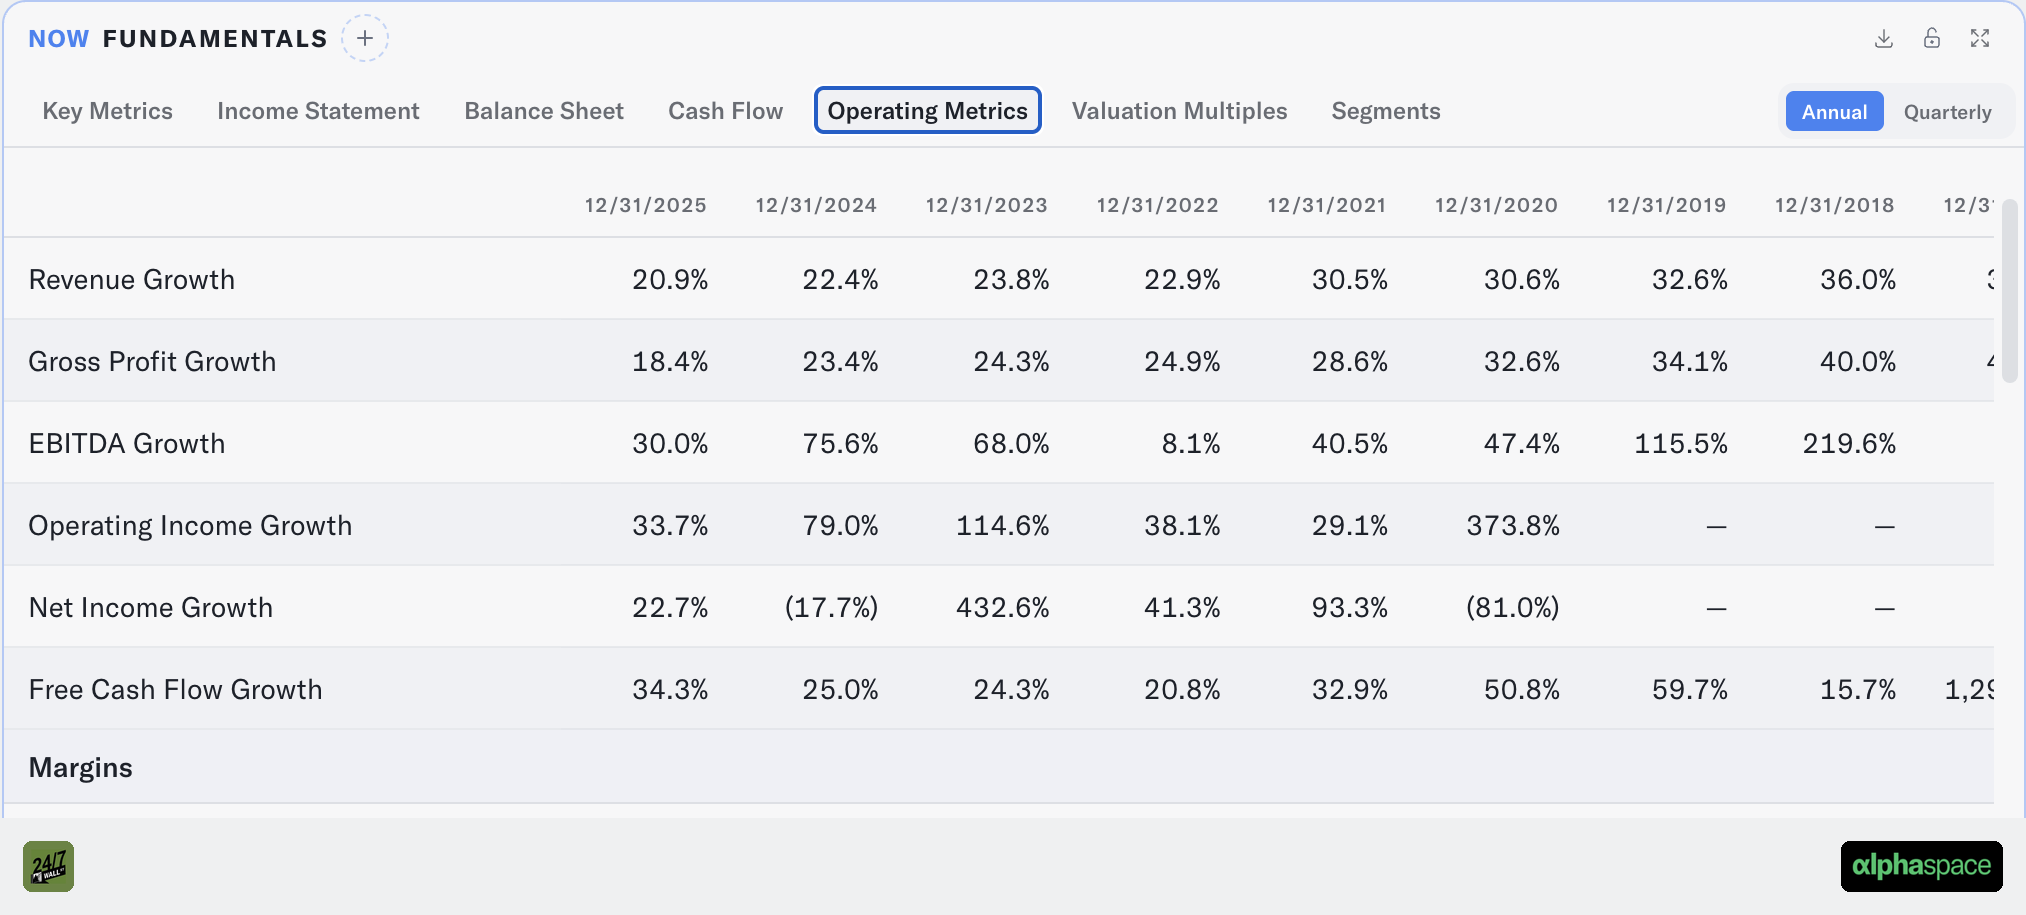
This is because margin has expanded every year, climbing from 10.9% in 2022 to 22.8% today. Free cash flow was $634 million in Q2, up more than 20% YoY. Even better, guidance calls for a 35% full-year free cash flow margin. CEO Bill McDermott said on the most recent earnings call that
“operating to the Rule of 56, well on our way to the Rule of 60.”
Rather than being eaten alive by AI, ServiceNow is deploying AI across it’s platform to become even more valuable to customers. ServiceNow AI just crossed $1.00 billion in annual contract value, agentic deployments increased 9x in less than a year, and there are now more than 650 customers with more than $5 million in annual contract value. Truly remarkable stuff, and not the sort of figure you see from a dying company.
And It Gets Better
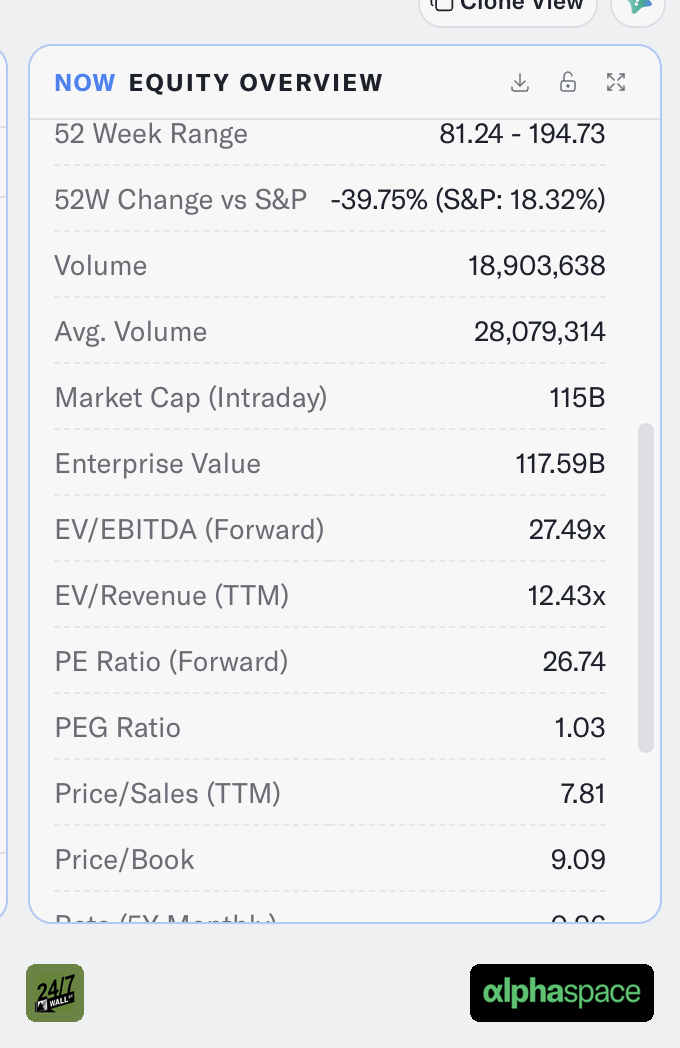
Today the forward P/E today sits at 27. That may seem expensive, but recall that ServiceNow has consistently had retention rates in excess of 97%, and net dollar retention figures that exceed 120%. This is very high quality, and durable revenue that is worth a premium. In recent years that number ran 42 in 2022, 88 in 2021, and 98 in 2020. Forward EV/revenue is 10x, versus the 16.3x to 19.2x range during 2021 to 2024. On forward multiples this is the cheapest NOW has ever traded as a public company.
the company sees the same disconnect, and announced an additional $5 billion in share repurchases in January, with over $4b of that remaining today.
Can’t Ignore The Risks
There are real risks you can’t dismiss. Growth is decelerating. If subscription growth reliably breaks below 15% even the better multiples we’re paying today won’t save the share price. Operating income has fallen in Q2 on integration costs from Armis and Veza. If ServiceNow continues an acquisition spree, this would continue and may change my thesis. Today, i want to see them executing on the core business.
The growth story is fading at the same time the profit engine is picking up speed. My next $20,000 is betting that things are brighter tomorrow than today, and am including the receipts here to prove it.
Data Sources:
- Yahoo Finance’s AlphaSpace service
- ServiceNow’s most recent annual and quarterly SEC filings
- ServiceNow’s conference call.
Contact [email protected] for any questions or corrections.
Austin Smith is a financial publisher with over two decades of experience as an investor, analyst, and advisor. He covers stocks, ETFs, Artificial intelligence and personal finance for 24/7 Wall St. Previously, he spent over a decade at The Motley Fool as a senior editor for Fool.com, portfolio advisor for Millionacres, and launched The Ascent to help reader take control of their personal finances.
His work has been featured on Fool.com, NPR, CNBC, USA Today, Yahoo Finance, MSN, AOL, Marketwatch, and many other publications. He is as an advisor to private companies, and co-hosts The AI Investor Podcast with Eric Bleeker.
When not looking for investment opportunities, he can be found skiing, running, or playing soccer with his children. Learn more about Austin's investment approach here.