This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Live coverage has ended. The full story is below.
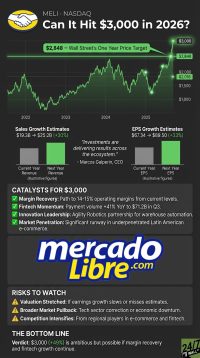
MercadoLibre (NASDAQ:MELI | MELI Price Prediction) reports Q2 2026 results tonight after the market closes at 4:00 PM ET. The Latin American commerce and fintech leader enters an earnings report with just under a $100 billion market cap, where the company will be tested to see whether its aggressive investment is producing the promised operating leverage.
Growth Machine, Margin Question
Q1 2026 set a high bar. Revenue jumped 49.03% to $8.845 billion, beating consensus by 6.27%, while EPS landed at $8.23. Fintech revenue rose 51%, the credit card portfolio expanded 104% YoY to $6.6 billion, and Brazil unique buyer growth hit its fastest pace in five years at +32%.
Operating income fell 19.92% to $611M, adjusted free cash flow ran negative $56M, and provisions for doubtful accounts more than doubled to $1.244 billion. Shares are down 21.18% over the past year and down 6.24% YTD, though up 7.1% in the last month into the report.
Consensus Estimates
| Metric |
Q2 2026 Estimate |
YoY Change |
FY 2026 Context |
| Revenue |
$9.74B |
+43.5% |
FY 2025 base: $28.893B |
| EPS (Normalized) |
$8.69 |
-15.9% |
FY 2025 base: $39.40 |
The setup captures the trade-off cleanly: revenue accelerating past 40% growth while EPS forecasts have been cut 22.4% over the past three months.
What I’m Watching Tonight: Margins, Credit, and the New CEO Take Center Stage
Tonight, I’ll be watching operating margin closely. Management signaled in Q1 that the margin dial would not change materially near term, so a tone shift here would move the stock. Credit is the second lever. NIMAL slipped 4.9 percentage points to 17.8% in Q1, and Brazil loan book quality remains the analyst focal point.
Investors will also focus on Brazil shipping economics. Unit shipping costs there fell 17% YoY in local currency in Q1, accelerating from 11% in Q4 2025. Continued progress would validate the reset of the free-shipping threshold. I’ll also parse Argentina, where growth decelerated to +23% against Mexico’s +62%.
Finally, this is the first Q2 with Szarfsztejn as CEO. His framing of the investment cadence, AI productivity, and the China fulfillment corridor will shape the narrative into year-end.
Earnings History
| Quarter |
EPS Surprise |
Day-Of Move |
1-Week Move |
30-Day Move |
| Q1 2026 |
+0.35% |
-12.7% |
-5.25% |
-2.71% |
| Q4 2025 |
-6.92% |
-8.05% |
+0.07% |
-9.51% |
| Q3 2025 |
-10.51% |
+2.82% |
-9.85% |
-10.37% |
| Q2 2025 |
-13.26% |
+0.51% |
-2.37% |
+0.39% |
On average, shares moved -2.02% one week after earnings over the past year.
Contact [email protected] for any questions or corrections.