This is One of the Cheapest Magnificent Seven Stocks Right Now
AWS just posted its fastest growth in 18 quarters, yet Amazon shares have cooled off while its fundamentals have raced ahead. One corner of its valuation tells a very different story from what the stock price suggests.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Amazon (NASDAQ:AMZN | AMZN Price Prediction) has quietly become one of the most reasonably priced names in the Magnificent Seven, trading at a forward multiple that looks modest against the pace of AWS reacceleration.
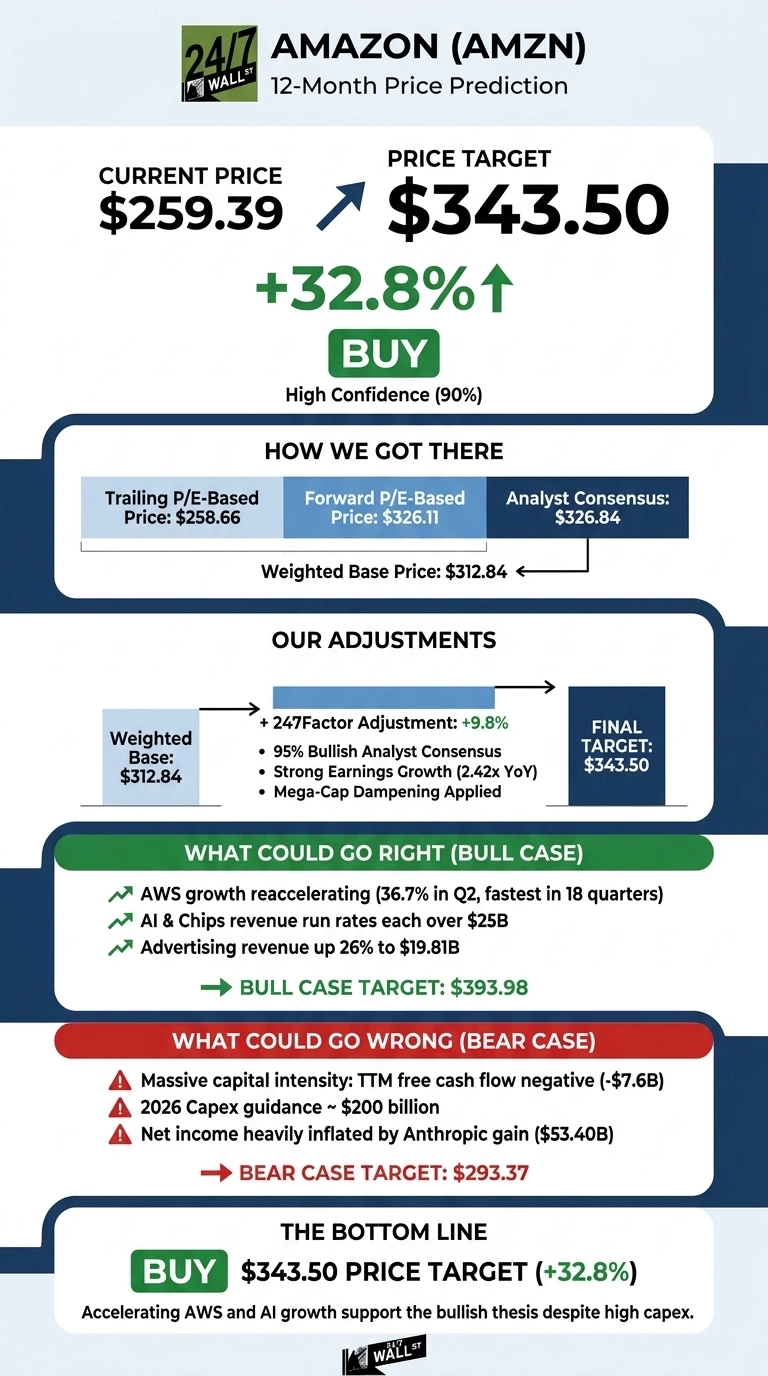
Our 24/7 Wall St. price target for Amazon is $343.50, roughly 32.8% above the current quote of $259.39. Our recommendation is buy with a high confidence reading of 90%.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $259.39 |
| 24/7 Wall St. Price Target | $343.50 |
| Upside | 32.8% |
| Recommendation | BUY |
| Confidence Level | 90% |
AWS Reaccelerates While the Stock Lags the Story
Amazon shares are up 12.69% year to date and 16.22% over the past year, but the stock has cooled 1.89% in the past week even as the fundamentals accelerated.
In Q2 FY2026, revenue reached $200.61 billion, up 19.62% year over year, and operating income jumped 43.24% to $27.46 billion. AWS grew 36.7%, its fastest pace in 18 quarters, with backlog swelling to $496 billion. CEO Andy Jassy went further, telling investors AWS could “very possibly be a trillion dollar annual revenue business” over time.

Why Bulls See a Path to $394
The bull case rests on AWS operating leverage and AI monetization. AWS ran a 39.4% operating margin in Q2, and Jassy disclosed that Amazon’s AI and Chips businesses each cleared a $25 billion annualized run rate growing triple digits.
Anthropic and OpenAI have committed to multi-year, multi-gigawatt Trainium deployments, and Amazon is on track to double power capacity by the end of 2027. Advertising grew 26% to $19.81 billion. If demand keeps pulling forward, our bull scenario points to $393.98, a 52.32% return.

What Could Go Wrong
Capital intensity is the obvious risk. Q2 capex hit $54.21 billion, up 68.44% YoY, pushing trailing free cash flow to negative $7.6 billion, and management is guiding to roughly $200 billion of 2026 capex.
Reported net income is also inflated by a $53.40 billion Anthropic mark, so comparable EPS is roughly $1.88. Bulls would counter that servers break even in under three years and monetize for 30-plus years, making today’s spending a duration trade. Our bear scenario lands at $293.37.

How Amazon Compares to Alphabet and Microsoft
Alphabet (NASDAQ:GOOGL) is the sharpest peer on cloud plus ads and trades at a forward P/E of just 17, versus Amazon at 23. That gap looks defensible given Alphabet’s 54.8% profit margin, but Amazon’s 37% AWS growth is outrunning the Google Cloud story.
Microsoft (NASDAQ:MSFT) trades at a forward P/E of 24 with an operating margin of 45.1%, richer than Amazon on both counts.
| Company | Forward P/E | Operating Margin |
|---|---|---|
| Amazon | 23 | 13.7% |
| Alphabet | 17 | 34.0% |
| Microsoft | 24 | 45.1% |
Amazon sits between the two, and given AWS growth is the fastest of the three hyperscalers, the peer group makes our target look reasonable, not aggressive.
Amazon Price Prediction 2026-2030
The 24/7 Wall St. price target of $343.50 and buy rating at 90% confidence reflect a rare setup: accelerating AWS growth, a stock that has lagged its own fundamentals, and a forward multiple that looks fair versus peers.
The setup looks constructive if AWS holds a 30%-plus growth trajectory into 2027, and the thesis weakens if capex runs past $220 billion without visible ROIC improvement. On balance, the risk-reward skews positive on the numbers in hand.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $279.80 |
| 2027 | $338.41 |
| 2028 | $412.77 |
| 2029 | $490.48 |
| 2030 | $535.25 |
These projections assume Amazon continues to convert AI capex into AWS revenue and margin. Meaningful upside or downside could come from Anthropic monetization, Trainium adoption, or a slowdown in cloud consumption. The whole buildout also has to be powered, cooled, and networked by somebody, and we pulled together seven companies doing exactly that in a free AI infrastructure report.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.