Coca-Cola Is No Longer Just a Dividend Stock
Five straight earnings beats and a 35% one-year rally have investors questioning whether KO still belongs in the dividend stock category, and the answer reshapes how you should value it today.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Coca-Cola (NYSE:KO | KO Price Prediction) is evolving from a bond-proxy dividend aristocrat into a growth compounder. After five consecutive quarters of EPS beats, raised full-year guidance, and a 33.35% year-to-date rally, KO behaves like a growth stock in dividend clothing.
My price target reflects that shift.

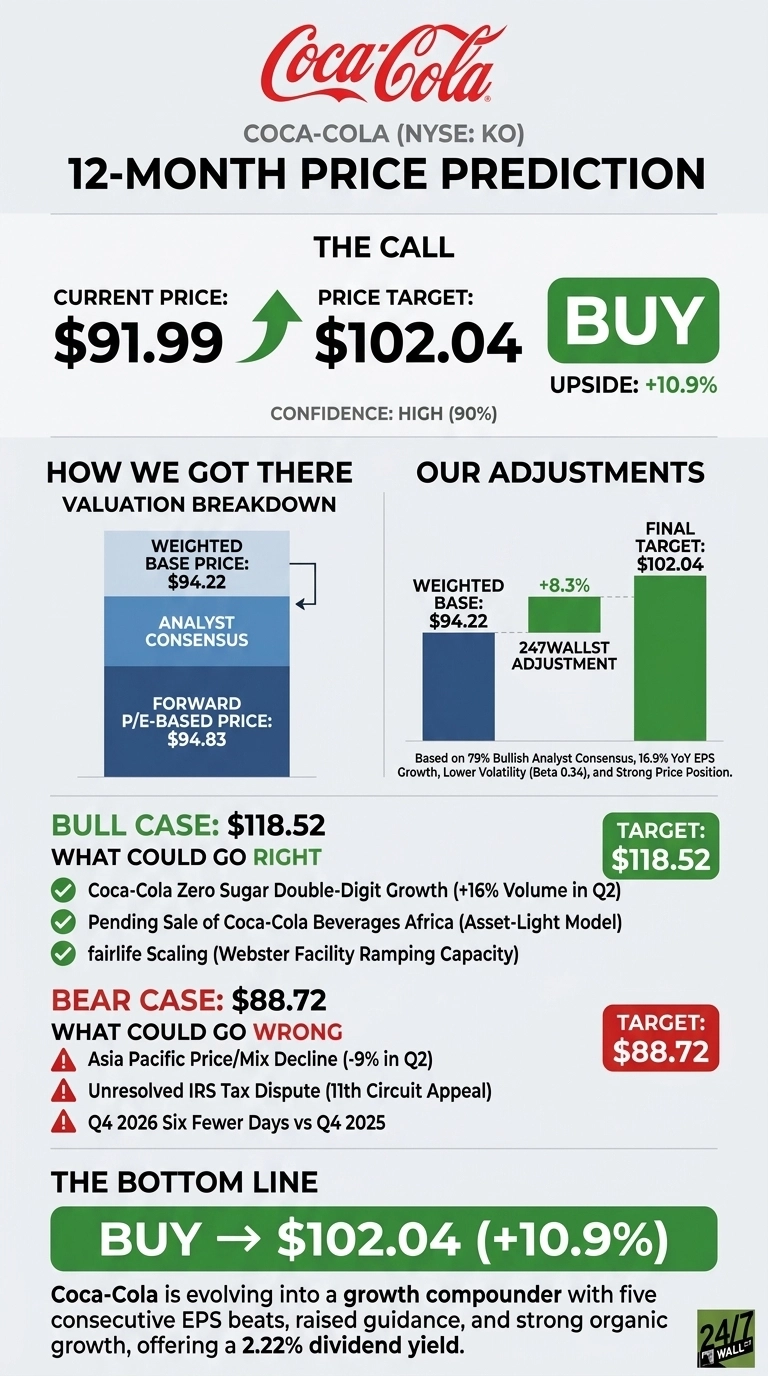
The 24/7 Wall St. price target for Coca-Cola is $102.04, implying meaningful upside from a stock near its 52-week high. My recommendation is buy, with high confidence.
| Metric | Value |
|---|---|
| Current Price | $91.99 |
| 24/7 Wall St. Price Target | $102.04 |
| Upside | 10.93% |
| Recommendation | BUY |
| Confidence Level | 90% |
Coca-Cola is compounding earnings again. My model rewards that with a premium multiple.
Rally That Changed the Narrative
KO has climbed 11.84% in the past month and 34.91% over the past year, trading roughly 2% below its 52-week high of $92.49. The catalyst was Q2 2026, reported July 28:
- EPS of $0.97 beat by 4.04%
- Revenue of $13.38 billion grew 6.74%
- Global unit case volume rose 5%
- Operating margin expanded to 34.9%
- Management raised full-year comparable EPS growth guidance to 9% to 10% and free cash flow guidance to approximately $12.4 billion
- FIFA World Cup 2026 activation spanning more than 180 markets and 20 million retail outlets drove Trademark Coca-Cola volume up 5% and Powerade up 8%

Bull Case: $118
My bull case takes KO to $118.52, a 28.84% total return. Three levers drive this path:
- Coca-Cola Zero Sugar compounds at double digits (+16% volume in Q2)
- Pending sale of Coca-Cola Beverages Africa, expected to close toward the end of Q3 or during Q4 2026, tightens the asset-light model and lifts Q4 operating margin
- fairlife scales after cybersecurity disruption, with the Webster facility ramping capacity through year end
Analyst consensus already sits at $94.70, with 19 Buy or Strong Buy ratings against just one Strong Sell.

Risks Worth Watching
My bear case takes KO to $88.72, a 3.56% loss. Asia Pacific price/mix declined 9% in Q2, KO recorded a $960 million BODYARMOR impairment in Q4 2025, and the 11th Circuit IRS appeal remains unresolved. Q4 2026 will also have six fewer days versus Q4 2025.
Bulls counter that Asia Pacific weakness reflects deliberate affordability investment (mini-cans in India, entry price points in China), and that KO owns seven of the top 10 brands in India. These are deliberate growth investments.
Coca-Cola vs. PepsiCo and Monster
PepsiCo (NASDAQ:PEP) is the direct competitor. Its Q2 2026 organic revenue growth of just 2.4% against KO’s 6% highlights the growth gap. PEP trades at a P/E near 24 with a 3.87% dividend yield, cheaper on both metrics, but the discount reflects genuinely slower growth.
Monster Beverage (NASDAQ:MNST) is the pure-growth comp, with 20.2% Q2 revenue growth and a P/E near 50.
| Company | P/E | Dividend Yield |
|---|---|---|
| Coca-Cola | 30 | 2.22% |
| PepsiCo | 24 | 3.87% |
| Monster | 50 | None |
KO sits between them on valuation, where the growth profile deserves to sit. My 24/7 Wall St. price target looks reasonable given the growth profile.
Coca-Cola Price Prediction 2026 to 2030
My 24/7 Wall St. price target is $102.04, recommendation buy, confidence 90%. Management raised comparable EPS growth to 9% to 10% after delivering five straight beats.
The setup suits investors seeking a defensive growth compounder with a $2.12 forward dividend attached. Investors seeking a bargain multiple will find KO no longer trades like one.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $95 |
| 2027 | $102 |
| 2028 | $110 |
| 2029 | $119 |
| 2030 | $126 |
These projections assume Coca-Cola executes on its asset-light refranchising strategy and sustains mid-single-digit organic revenue growth. Significant upside or downside could result from the IRS ruling or a sharper-than-expected consumer downturn in Asia.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.