This Warren Buffett Favorite Still Has Room to Run
Warren Buffett has held Coca-Cola since 1988, and after a 35% run over the past year, most investors assume the opportunity has passed. Our model disagrees, and the reason comes down to one number buried inside the latest earnings report.

Coca-Cola (NYSE:KO | KO Price Prediction) has been Warren Buffett’s largest and longest-held equity position since 1988, and the beverage giant is finally getting the market’s attention again. Shares have climbed 28.24% year to date and 35.86% over the past year. My proprietary model still sees more room to run, though the easy money has already been made.
| Metric | Value |
|---|---|
| Current Price | $87.94 |
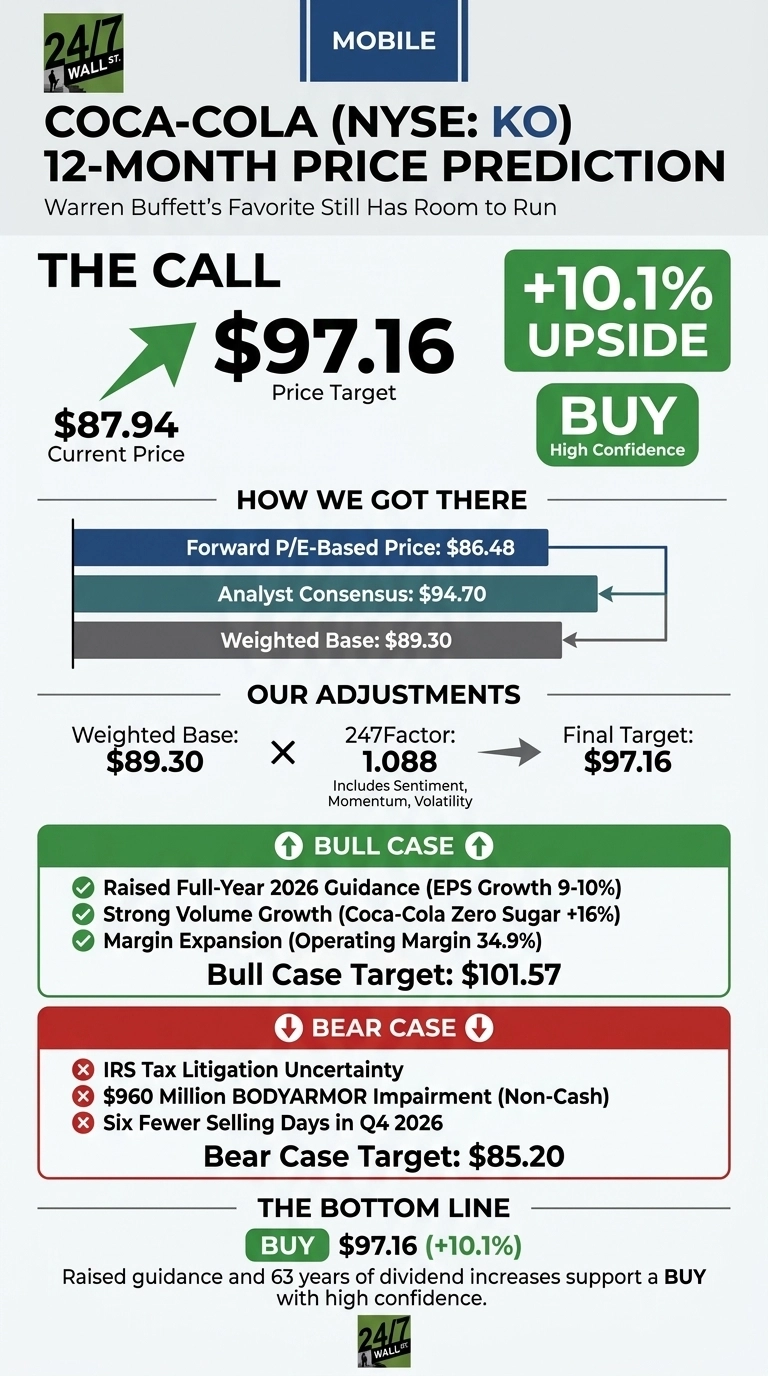
| 24/7 Wall St. Price Target | $97.16 |
| Upside | 10.1% |
| Recommendation | BUY |
| Confidence Level | 90% |
Our 24/7 Wall St. price target for Coca-Cola is $97.16 over the next 12 months. That is a buy call with high confidence, driven by durable brand strength, expanding margins, and a raised full-year guide.
The upside is modest at roughly 10%, but layered on top of a 2.31% dividend yield, total return still looks compelling for a mega-cap defensive.

World Cup Momentum and a Raised Guide
KO trades just below its 52-week high of $91.94 and well above the 52-week low of $63.66. Shares are up 0.2% over the past week but down 2.09% in the past month as the stock consolidates recent gains.
Q2 2026 was the fifth straight EPS beat, with adjusted EPS of $0.97 versus $0.9323 estimated on revenue of $13.38 billion (+6.74% year over year). Global unit case volume rose 5%, aided by a FIFA World Cup activation spanning 180+ markets. Management raised full-year comparable EPS growth guidance to 9% to 10% and free cash flow to roughly $12.4 billion.

Why Bulls See a Breakout Ahead
The bull case leans on Coca-Cola Zero Sugar volume up 16%, Latin America revenue growing 16%, and operating margin expansion to 34.9%.
Trademark Coca-Cola volume delivered its strongest growth in 17 years excluding COVID recovery. Our bull-case scenario points to $101.57, a 15.1% total return, if the raised guide holds and fairlife capacity ramps at Webster.

Risks Worth Watching
Bears will point to the $960 million BODYARMOR impairment booked in Q4 2025, ongoing IRS tax litigation, value-share loss in India, and six fewer selling days in Q4 2026.
The bear case forecast is $85.20, a 3.46% pullback. That said, the impairment was non-cash, and the concentrate-shipment lag is a timing issue rather than a demand problem.

How Coca-Cola Compares to PepsiCo and Keurig Dr Pepper
PepsiCo (NASDAQ:PEP) is the direct rival. PEP trades at a forward P/E of 14x with a 4.3% dividend yield, materially cheaper than KO’s 28 trailing P/E. However, PEP’s quarterly revenue growth of 6.4% trails KO, and PepsiCo lacks the margin expansion story.
Keurig Dr Pepper (NASDAQ:KDP) trades at a forward P/E of 12x with an operating margin of 12.9%, well below KO’s 28.71%.
| Company | Forward P/E | Dividend Yield |
|---|---|---|
| Coca-Cola | 26 | 2.31% |
| PepsiCo | 14 | 4.3% |
| Keurig Dr Pepper | 12 | 2.93% |
Coca-Cola Price Prediction 2026-2030
The 24/7 Wall St. price target of $97.16 supports a buy at 90% confidence. The tipping factor is the raised guidance combined with 63 consecutive years of dividend increases. KO fits a defensive compounding profile at a fair premium, while PEP offers double-digit growth at a value multiple.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $90.43 |
| 2027 | $97.26 |
| 2028 | $104.59 |
| 2029 | $111.77 |
| 2030 | $119.75 |
These projections assume Coca-Cola sustains its 4% to 6% long-term growth algorithm. Meaningful upside or downside could come from the IRS tax ruling and fairlife’s ramp.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.