The Market May Be Underestimating This AI Chip-Design Stock
Synopsys just posted explosive revenue growth that dwarfs its closest EDA rival, yet the market prices it at a fraction of that rival's multiple. Something in that gap tells a story most investors are missing.

Synopsys (NASDAQ:SNPS | SNPS Price Prediction) delivered one of the cleanest earnings reports in the electronic design automation (EDA) space, and the market is discounting how much AI-driven design complexity favors the incumbent.
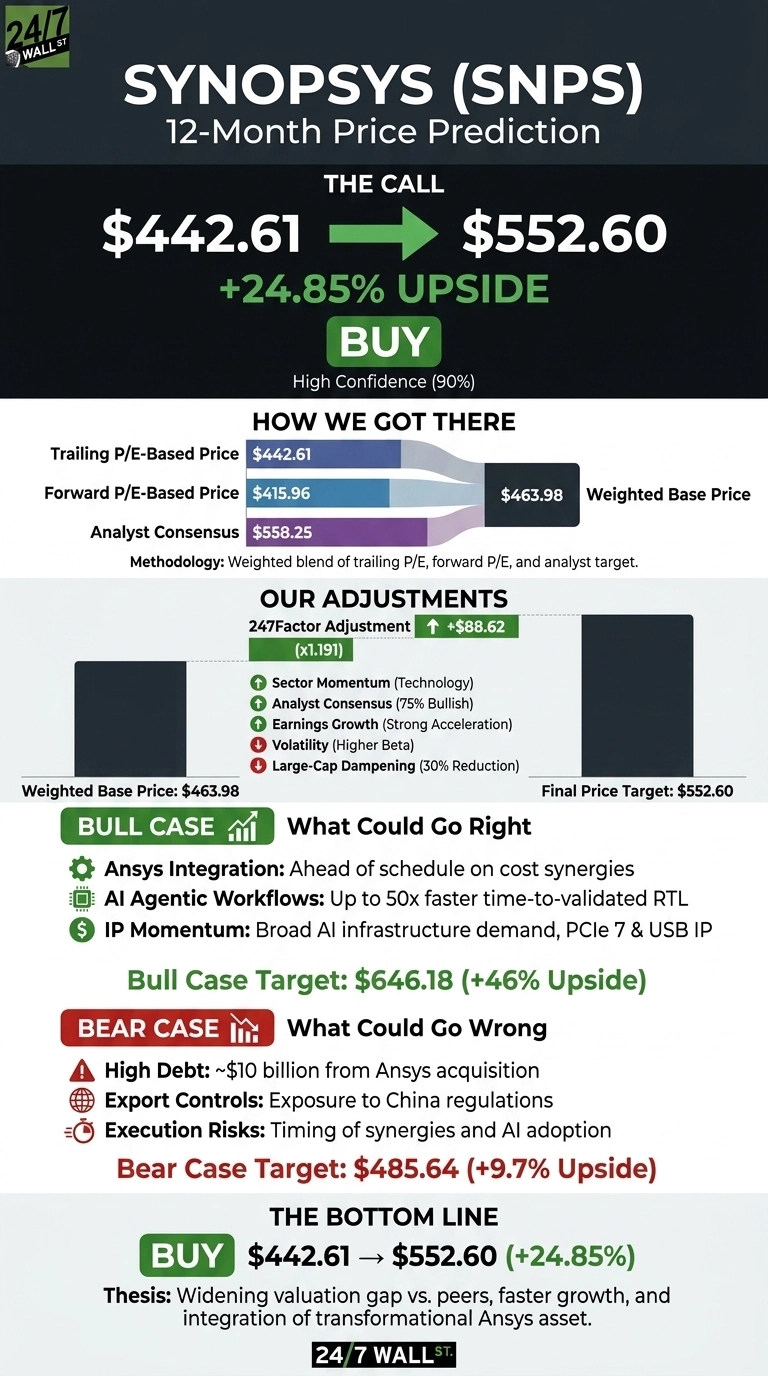
My 24/7 Wall St. price target for Synopsys is $552.60 over the next 12 months, implying +24.85% upside from $442.61. The recommendation is buy with a 90% confidence reading.
| Metric | Value |
|---|---|
| Current Price | $442.61 |
| 24/7 Wall St. Price Target | $552.60 |
| Upside | +24.85% |
| Recommendation | BUY |
| Confidence Level | 90% |

Post-Earnings Reset Changes the Setup
Shares jumped roughly 13% after the Q3 FY26 report on August 26, up 11.24% over the past week and 18.44% over the past month. Year to date it remains down 5.77%, well below the 52-week high of $615.79.
Q3 revenue came in at $2.477 billion, up 42.37% year over year, with non-GAAP EPS of $3.91 beating the Street by 6.44%. Management raised full-year revenue guidance to $9.690 billion to $9.740 billion and non-GAAP EPS to $15.04 to $15.10.

Bull Case for $600+
Three pillars support the bull thesis. First, the Ansys integration is ahead of schedule on cost synergies, with first joint solutions expected to contribute to EDA growth in fiscal 2027.
Second, agentic AI workflows co-developed with NVIDIA showed up to 50x faster time-to-validated RTL, and CEO Sassine Ghazi noted agents “orchestrate our underlying EDA tools at a significantly higher rate,” creating a consumption-based revenue kicker.
Third, IP momentum is broadening: more than 95% of PCIe 7 opportunities, die-to-die IP on pace to double, and USB IP crossing $2 billion in lifetime bookings. Our bull scenario points to $646.18, roughly +46%.

Risks to Consider
Bears cite approximately $10 billion of total debt from the Ansys deal, export-control exposure to China, and Morgan Stanley’s prior deceleration concerns. Q3 EDA growth of 8.5% cleared a tough 16% compare, so the reacceleration story must materialize.
Management repaid term loans early, and Q2 GAAP profitability was compressed by Ansys purchase accounting, a non-operating factor. Our bear scenario still lands at $485.64, above today’s price.
Synopsys vs. Cadence and Autodesk
Cadence Design Systems (NASDAQ:CDNS) is the direct EDA duopoly partner and trades at a forward P/E of 43 with 24.2% quarterly revenue growth. Synopsys is growing revenue 42% against Cadence’s 24.2%, yet trades at a much lower forward P/E of 27. That gap is the crux of our target: on Cadence’s multiple, SNPS would price well north of our number.
Autodesk (NASDAQ:ADSK) is the closest simulation-plus-design analog post-Ansys, trading at a forward P/E of 21 on 16.1% revenue growth. Synopsys is growing faster with higher operating margins, making the 27x forward multiple look fair-to-cheap. The peer set makes our 24/7 Wall St. price target reasonable, if anything conservative versus Cadence.
| Company | Forward P/E | Rev. Growth YoY |
|---|---|---|
| Synopsys | 27 | 42.4% |
| Cadence | 43 | 24.2% |
| Autodesk | 21 | 16.1% |
Buy It Here
My verdict is buy at $442.61 with a 24/7 Wall St. price target of $552.60 and 90% confidence. The tipping factor is the widening valuation gap versus Cadence while Synopsys is growing faster and integrating a transformational asset.
Conviction would build if Q4 EDA delivers double digits organically as guided (the same early-signal pattern we cataloged in a free playbook on spotting the next Nvidia-scale winner). Caution would rise if China export controls tighten materially or if the Investor Day walks back FY27 expectations.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $475.98 |
| 2027 | $556.07 |
| 2028 | $653.12 |
| 2029 | $724.11 |
| 2030 | $802.80 |
These projections assume Synopsys executes on Ansys synergies and agentic AI monetization. Significant upside or downside could come from custom-silicon royalty adoption or export-control policy shifts.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.