Synopsys Price Prediction: The AI Play With Big Upside This Year
Synopsys (NASDAQ:SNPS | SNPS Price Prediction) has staged one of the more dramatic comebacks in semiconductor software, climbing 21.78% in the past month after a brutal stretch through late 2025. With the Ansys integration now showing up in the numbers…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.

Synopsys (NASDAQ:SNPS | SNPS Price Prediction) has staged one of the more dramatic comebacks in semiconductor software, climbing 21.78% in the past month after a brutal stretch through late 2025. With the Ansys integration now showing up in the numbers and AI-driven chip design demand intact, our model points to further upside.
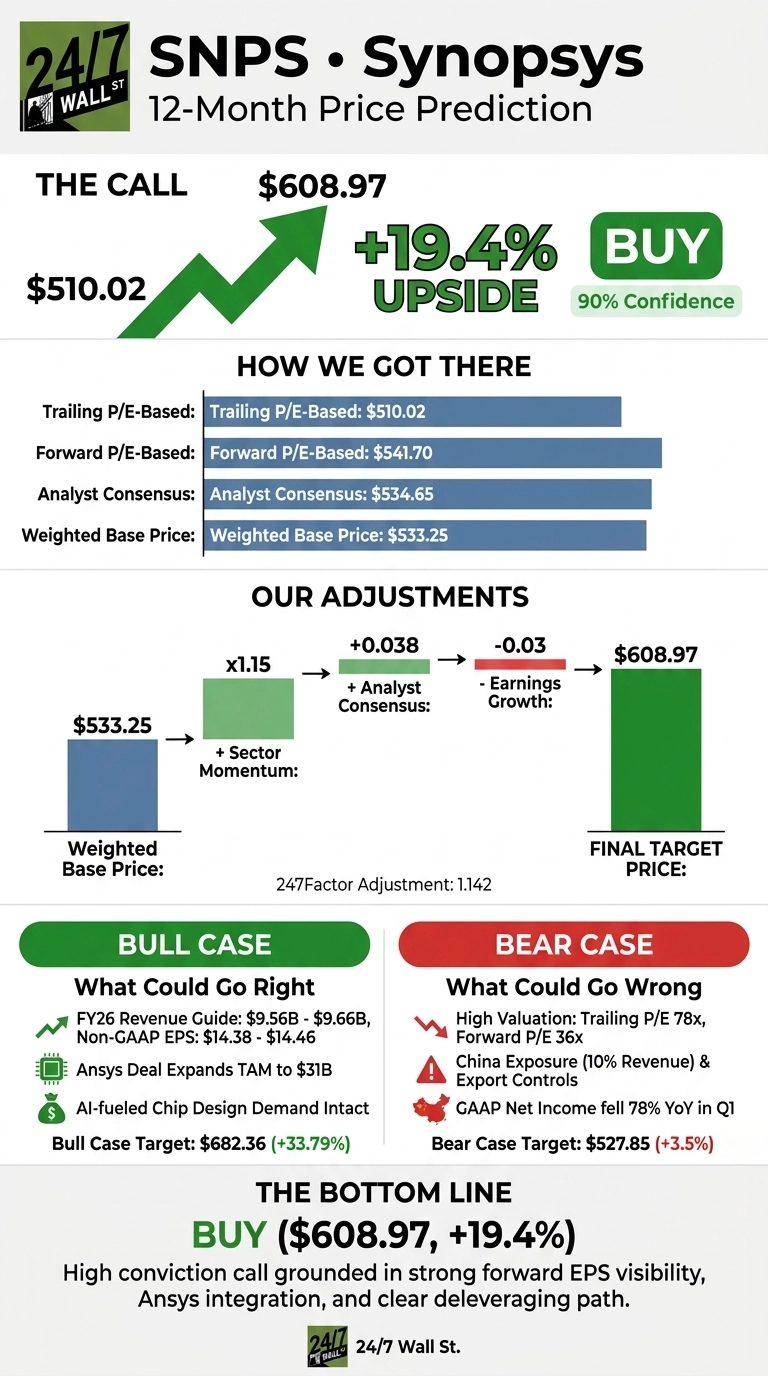
Our 24/7 Wall St. price target for Synopsys is $608.97, implying 19.4% upside from the current $510.02. We rate it a buy with 90% confidence, a high conviction call grounded in forward EPS visibility and a clear deleveraging path.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $510.02 |
| 24/7 Wall St. Price Target | $608.97 |
| Upside | 19.4% |
| Recommendation | BUY |
| Confidence Level | 90% |
From Q3 Selloff to a 22% One-Month Rally
Synopsys has whipsawed investors. The stock collapsed to $389.83 by November 2025 after a brutal Q3 FY25 miss, then clawed back to $510.02. Year to date, shares are up 8.58%, with the one-month surge of 21.78% reflecting renewed confidence in the Ansys story. The 52-week range runs from $376.18 to $651.73.
Q1 FY26, reported February 25, delivered revenue of $2.41 billion (up 65.4% YoY) and non-GAAP EPS of $3.77 against a $3.55 consensus, a 5.98% beat. Operating cash flow swung to $856.83 million from negative $67 million a year earlier, and management paid down $3.45 billion in long-term debt during the quarter.

Why Bulls See a Breakout Ahead
The bull case rests on FY26 guidance of revenue between $9.56 billion and $9.66 billion and non-GAAP EPS of $14.38 to $14.46, including roughly $2.9 billion in Ansys revenue.

CEO Sassine Ghazi said Synopsys has “the most compelling roadmap in our history” as AI fuels chip design R&D. The Ansys deal expanded the addressable market by 63% to $31 billion. Wells Fargo raised its target to $505 from $450 on May 14. Our bull scenario points to $682.36, a 33.79% total return.

The Risks Worth Watching
The bear case starts with valuation. Trailing P/E sits at 78, with forward P/E at 36. China accounts for roughly 10% of revenue and remains exposed to U.S. export controls. Morgan Stanley flagged growth deceleration, and Piper Sandler holds a Neutral rating with a $430 target.

GAAP net income fell 78.03% YoY in Q1, though bulls would argue this reflects $404 million in acquired intangible amortization and $118 million in restructuring, non-cash and non-recurring items that obscure underlying cash generation. The bear scenario lands at $527.85.
Synopsys Price Prediction 2026-2030
The 24/7 Wall St. price target of $608.97 reflects a buy rating at 90% confidence. The factor tipping the scale is cash flow visibility: $2.2 billion in expected FY26 operating cash flow plus a $2 billion repurchase replenishment.
The thesis strengthens if Q2 results land within the $2.225 to $2.275 billion revenue guide. It weakens if China export restrictions tighten further or Design IP margins fail to recover.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $608.97 |
| 2027 | $687.48 |
| 2028 | $745.00 |
| 2029 | $801.45 |
| 2030 | $880.97 |
These projections assume Synopsys continues executing on Ansys integration and AI-led EDA demand holds. Significant upside or downside could result from China export policy shifts or accelerated margin expansion through cost synergies.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.