Elon Musk Says ‘Enormous, Free Fusion Reactor in the Sky’ Will Supply 100% of Energy Needs

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Tesla (NASDAQ:TSLA | TSLA Price Prediction) CEO Elon Musk used his X account on September 11, 2026, to restate what has become the philosophical spine of Tesla’s energy strategy: the sun does the fusion, so humans should stop trying to replicate it. “The Sun is an enormous, free fusion reactor in the sky,” Musk wrote, calling it “super dumb to make tiny fusion reactors on Earth” and dismissing terrestrial alternatives as “puny little reactors” and “pet science projects.” In the same thread, he added that “solar energy over time will round up to 100% of energy harnessed (obviously).” The post drew 33.2 million views.

Quote Meets the Income Statement
The rhetoric shows up in the P&L. In Q2 2026, Tesla’s Energy Generation and Storage segment posted revenue of $3.139 billion, up 13% year over year, with storage deployments of 13.5 GWh, a 41% jump from the same period a year earlier. That followed a record Q4 2025 in which Tesla deployed 14.2 GWh of energy storage, and Q3 2025 energy revenue of $3.415 billion, up 44% year over year. On the Q2 earnings call, CFO Vaibhav Taneja said the energy business should “normalize at a gross margin rate in the mid to low 20% range” after gross margin compressed from 39.5% in Q1 to 20.4% in Q2, partly on a $240 million warranty true-up and the lapse of tariff benefits. Q2 also marked Tesla’s first quarter with more than $100 billion in trailing twelve-month revenue, a milestone the company highlighted in its shareholder letter.
A $20 Billion Bet on Panels, Cells, and Megapacks
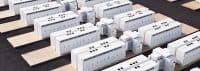
Musk is pairing the vision with capital. As of Q3 2026, Tesla has updated its full-year capital expenditure guidance to approximately $20 billion, down from the earlier projection of more than $25 billion, with Taneja describing the revised figure as efficient deployment funded primarily from operating cash flow. The buildout spans solar manufacturing, Megapack production, semiconductor fabs, and AI compute. Musk framed the effort as “the fastest industrial scale up since World War II in America,” covering silicon refinement through solar cell and panel production, and argued that “the solar battery combination will be how the vast majority of energy in the world is produced in the future.”
The scale of that ambition became clearer when Tesla filed a tax-incentive application in Texas for a $10.1 billion vertically integrated solar cell factory in Fort Bend County, roughly 40 miles southwest of Houston. Internally codenamed “Project Crystal Sun,” the 3,050-acre facility would run from raw polysilicon ingot manufacturing through finished cells and panels under one roof, targeting commercial operations in early 2029. The filing projects 9,712 permanent jobs at the site. Since the original filing, the project has advanced through local approvals: Lamar Consolidated ISD trustees voted 7-0 in September 2026 to approve a property tax incentive, and Fort Bend County commissioners followed with a unanimous 4-0 approval of a broader tax-break package in late October 2026. Tesla has not yet made a final site-selection decision, however, and has told Texas officials it is still weighing Fort Bend County against at least one out-of-state location offering a competing incentive package.
Cost Showing Up in the Numbers
Investors absorbed the cost of the Q2 buildout sprint directly. Capital expenditures that quarter reached $5.789 billion, up 142% year over year. Operating income fell 57% to $398 million, and free cash flow swung to negative $1.092 billion. Non-GAAP EPS of $0.33 missed the $0.51 Wall Street consensus by a wide margin.
The picture shifted somewhat in Q3. Capital expenditures fell sequentially to $4.73 billion, and free cash flow recovered to positive $1.5 billion. Non-GAAP EPS of $0.48 beat the $0.45 consensus, though it was still down 4% from $0.50 a year earlier. Total gross margin expanded 160 basis points to 19.6%, and operating income rose to $718 million from Q2’s $398 million, though it still fell 56% year over year as research and development spending surged 69%. As of early November 2026, TSLA trades near $360, down about 20% year to date on a trailing P/E above 420x.

The Energy Segment’s Complicated Quarter
Energy results in Q3 came with a large asterisk. Revenue fell 16% to $2.881 billion, a counterintuitive drop given that deployments actually rose 10% to 13.7 GWh. Tesla attributed the revenue decline partly to tariff-related refunds issued to customers. Gross margin jumped to 33.1% from Q2’s 20.4%, but that rebound owed heavily to $526 million in non-recurring tariff refunds recognized in the quarter. Stripping out those one-time items, the underlying margin picture remains closer to management’s normalized guidance of the low-to-mid 20% range. Energy gross profit came in at $954 million, below the $1.073 billion recorded in Q3 2025. On a brighter note, Tesla reported its highest-ever energy storage order rate and backlog during Q3, suggesting demand pressure ahead, even if near-term revenue recognition remains uneven.
Doubts the Bull Case Has to Answer
The “100% solar” framing runs into grid realities that no single post on X can resolve. The EIA’s Annual Energy Outlook 2026 baseline projects solar at roughly 20% of U.S. generation by 2050 in its Counterfactual Baseline scenario, with natural gas at about 40% and wind at 20%. Combined, those three sources supply around 80% of generation in most modeled cases, but fossil fuels still command the largest single share. Utility-scale solar farms consume large tracts of land, depend on polysilicon and silver supply chains that remain concentrated outside the United States, and face environmental permitting friction that no social media thread addresses. Project Crystal Sun’s own filing notes that the Fort Bend County site’s economics are “not competitive” without state and local incentives, illustrating the gap between Musk’s vision and market reality. Whether Tesla’s storage-heavy answer can bridge that structural gap is the multi-year test sitting behind every capex line.
What to Watch Next
With Q3 results now in hand, the near-term focus shifts to energy margin normalization. The 33.1% Q3 gross margin was flattered by one-time tariff refunds, and whether the segment can sustain margins in the mid-to-low 20% range on a clean basis will be a central question heading into Q4. Progress at the Brookshire, Texas, Megapack Megafactory and a final site-selection decision for Project Crystal Sun are the two manufacturing milestones most likely to move sentiment on Tesla’s energy narrative. And with TSLA down roughly 20% for the year, trading at a valuation that prices in decades of growth, the gap between Musk’s solar-dominant vision and the company’s near-term financials remains as wide as ever.

Editor’s note: This article has been updated to incorporate Tesla’s Q3 2026 financial results (released October 21, 2026), including energy revenue of $2.881 billion (down 16%), energy storage deployments of 13.7 GWh, an energy gross margin of 33.1% boosted by $526 million in tariff refunds, and a full-year 2026 capex guidance revision to approximately $20 billion. It also adds the Fort Bend County commissioners’ 4-0 approval of Project Crystal Sun tax incentives in late October 2026, alongside the clarification that Tesla has not made a final site-selection decision; the current TSLA share price near $360 and trailing P/E above 420x; and Q4 2025’s record 14.2 GWh energy storage deployment figure.
Contact [email protected] for any questions or corrections.
After two decades of patrolling the dark corners of suburbia as a police officer, Rich Duprey hung up his badge and gun to begin writing full time about stocks and investing. For the past 20 years, he’s been cruising the markets looking for companies to lock up as long-term holdings in a portfolio while writing extensively on the broad sectors of consumer goods, technology, and industrials. Because his experience isn’t from the typical financial analyst track, Rich is able to break down complex topics into understandable and useful action points for the average investor. His writings have appeared on The Motley Fool, InvestorPlace, Yahoo! Finance, Money Morning, and, of course, 24/7 Wall St. He has been featured in both U.S. and international publications, including MarketWatch, Financial Times, Forbes, Fast Company, and USA Today.